Back Economics

Core PCE follow-up: another month of benign inflation data

Published on October 26, 2025

∙ Download the PDF Report

By

Gerard MacDonell

The main relevance of the CPI is that it allows us to update our best guess for the core PCE and associated detail for the same month.  Once the PCE data are released, the CPI and its detail become irrelevant, except for TIPS and other issues related to indexing, such as Social Security Payments. (The need for indexing, incidentally, is why the CPI was even produced this month.) Normally, we would supplement the CPI with additional data from the PPI and (secondarily) IPI to get a tighter sense of how the core PCE and related will print.  But this month will be different because the PPI and IPI are not going to be released until after the government shutdown ends.  And who knows when the PCE price data themselves will be released. In the meantime, we need to guess what the Fed is probably guessing about what the PCE will probably show.  We can probably do that well enough, with help from the informed consensus.  In that spirit, the news from Friday’s CPI was benign and perhaps more so than is appreciated in two regards:

  • The weak reading in rent inflation during August has to some extent (let’s not overstate the point) been dismissed as an unwind of a measurement distortion during July, when rents spiked at some price points in the South.  But that would have no effect on the 3- or 12-month rate of change, which looked better. More importantly, marginal rents matter more than average rents (reflected in the government data) and the recent news on marginal rents has been quite constructive.
  • People may not fully appreciate that the informed consensus’ mapping of the CPI detail to estimates of the Core PCE and related detail includes an add from an assumed rise in portfolio management and advisory fees, which are basically a noisy lagging measure of how the stock market has performed. And this month, this appears to be a moderately important issue for guesses of the Core PCE and (with greater importance) the services component of it.  Just because it is fun, I like to point out that equity types can’t get bearish equities because of the effect on the surging stock market on measured PCE inflation.  That argument is self-defeating. 

My single best measure of underlying inflation, whatever its other merits or demerits, effectively brackets these issues and is on track to print at 19 bps on the month.  The single best measure ignores non-market prices, which reduces noise, which is particularly valuable right now.  But the costs of that is that it has a — hopefully stable — downward bias of about 20 bps (ar). So when looking at the implied 3-, 6- and 12-month rates in the presentation below, just add back 20 bps to get a ballpark sense of what that measure implies for progress towards the Fed’s 2% inflation target — around which the Fed has expressed some lack of urgency, for good or ill. (Putting on my normative hat just briefly, I would say good.)

Core goods inflation is on track to print at +10 bps, which is highish, given that the pre-Covid globalization-adjacent trend there would be -10 or -20 bps.  But it is widely recognized that globalization is being reversed and that the Trump tariffs imply upward pressure on goods prices.  So, we need to assess “high” relative to what. Six months ago, I would have said we would be lucky to stumble into monthly goods price inflation prints of just 10 bps.  So, this is not so bad.   Excluding used MV, core goods price inflation has seemingly accelerated 25 bps between July and August, going from slightly negative to slightly positive. I think this was flagged to some extent by the Pricing Lab data that I flagged a couple weeks ago. But if those data are indeed predictive, then the bigger absolute rise in core goods prices (the first derivative, not the second) is coming in October.  We will have to monitor how the Pricing Lab data evolve in the interim.  For now, the inference to good prices from the September CPI is hardly a problem, given what we might have expected.

On services, I must return to the issue of portfolio management and advisory fees. The MPO version of the services PCE is invariant to that. And my reading of the informed consensus is that they are effectively factoring decent DISINFLATION there.  The underlying trend of inflation in the goods and services market is slightly above the Fed’s target.  But it is so by a narrower margin than we thought three months ago and by a much narrower margin than we thought when Trump was doing the Lethal Weapon imitation around Liberation Day.   I am not talking my book. I figured things would be worse. But for a variety of reasons, which I have tried to flag when they arose, they have not been. In fairness, this is not over.  
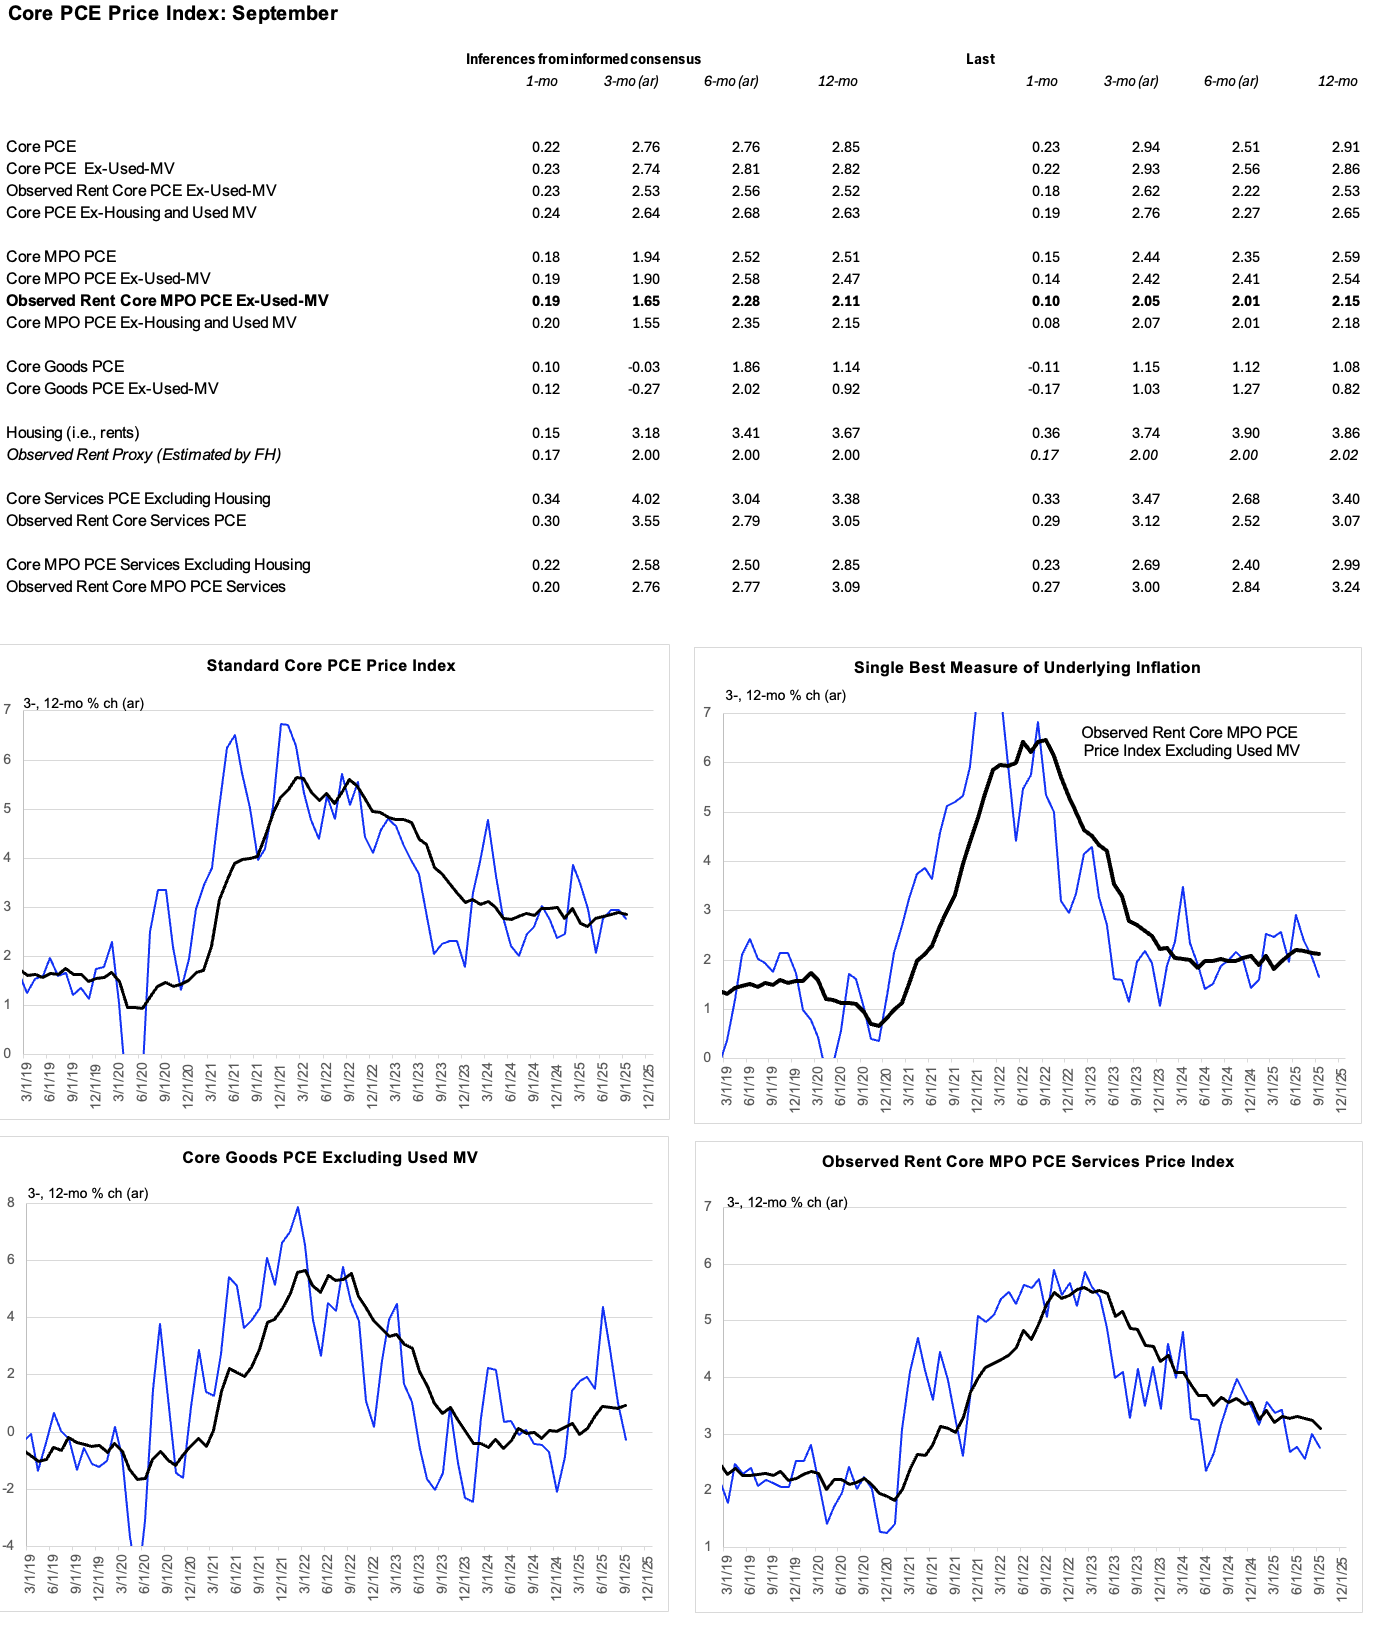
A screenshot of a graph

AI-generated content may be incorrect.
Source: BEA, FH estimates and inferences from informed consensus
Data are actual to August and estimates for September.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.