Back China Strategy

CHINA: Stimulus Expectations Muted Ahead of Politburo Meeting (CHESS Update)

Published on July 22, 2025

∙ Download the PDF Report

By

Michael Hirson

Houze Song

This report details the latest signals from 22V’s proprietary China Economic Sentiment Series (CHESS) tool. CHESS uses ChatGPT to assess the sentiment of analysts commenting in China’s domestic financial media, providing a snapshot of evolving views towards the economic and financial outlook.

SUMMARY

  • Analyst expectations for stimulus have declined to neutral ahead of the upcoming July Politburo meeting; this aligns with 22V’s view that Beijing will only announce new support measures after a further decline in growth momentum.
  • Sentiment towards the economic outlook and towards the equity market are slightly above neutral; we would not necessarily fight the recent rally in Chinese equities, given relatively low valuations, but would note the macro backdrop remains subdued.
  • Sentiment towards consumption has dipped on uncertainty over Beijing’s trade-in program and softness in the labor market.

Stimulus Expectations Decline Ahead of Politburo Meeting

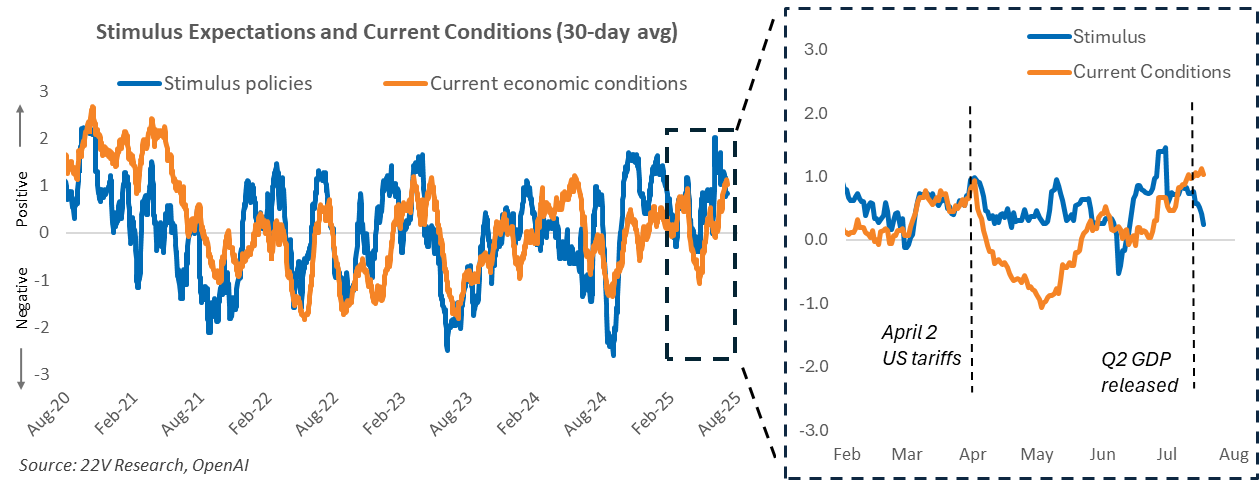
China’s 24-member Politburo decision-making body will meet by the end of the month to discuss economic policies for the second half of 2025. While our forthcoming preview note will provide details, we expect little in the way of concrete stimulus measures to come out of the meeting. A key factor is the strong headline GDP growth numbers for Q2, which came in at 5.2% year-over-year. Those figures mask a significant slowdown in sequential growth, which will continue through Q3. We expect Beijing to announce a modest stimulus boost only in early Q4, once the growth slowdown becomes evident in year-over-year numbers and forces policymakers to act.

CHESS signals align with that view. Analyst sentiment towards current economic conditions (orange line below) has picked up since mid-June. While we expect this momentum to fade, at present analysts perceive that Beijing is under little pressure to announce new support measures: Stimulus expectations (blue line) have declined and now stand near neutral. The silver lining of subdued analyst sentiment is that it reduces the risk of major market disappointment if the Politburo is lackluster, as we expect.
Neutral Sentiment Towards Growth and Equities

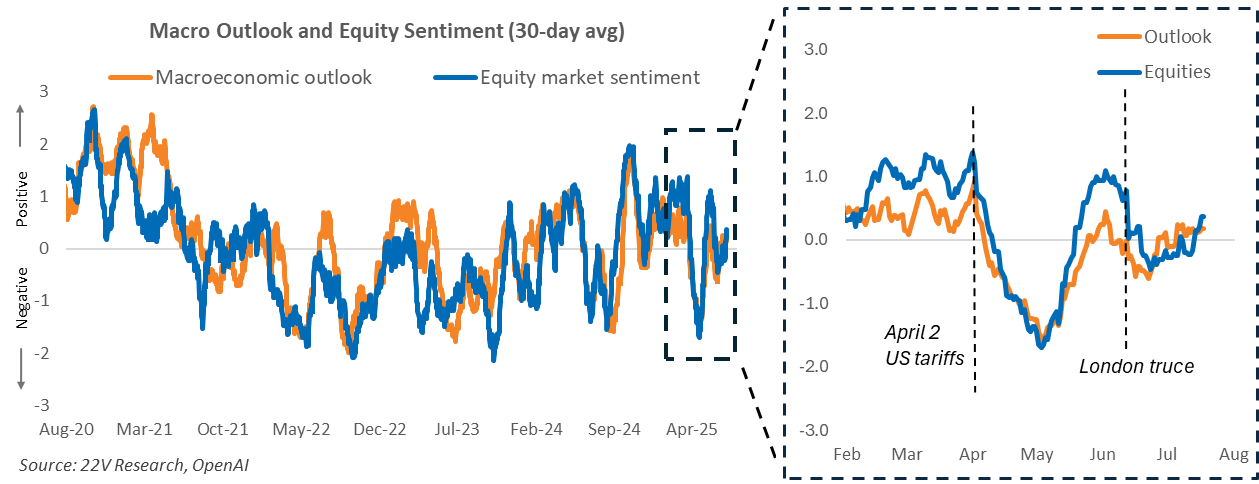
Volatility in US-China trade tensions since early April has sent sentiment towards the macroeconomic outlook (orange line below) and the equity market (blue line below) on a wild ride. Both series have picked up since the US-China tariff truce in mid-June, and are now slightly positive.

What does this imply for Chinese equities, which are up 16% since their bottom in early April? We would not necessarily fight the rally, which has been driven in part by reduced tail risks for US-China trade. Still, it is important to note that the overall growth backdrop remains muted: domestic demand is subdued, property activity is undergoing a “double dip,” deflationary pressures continue, and policy support is unlikely to gear up soon.
Export Sentiment Stabilizes, While Consumption Sentiment Dips

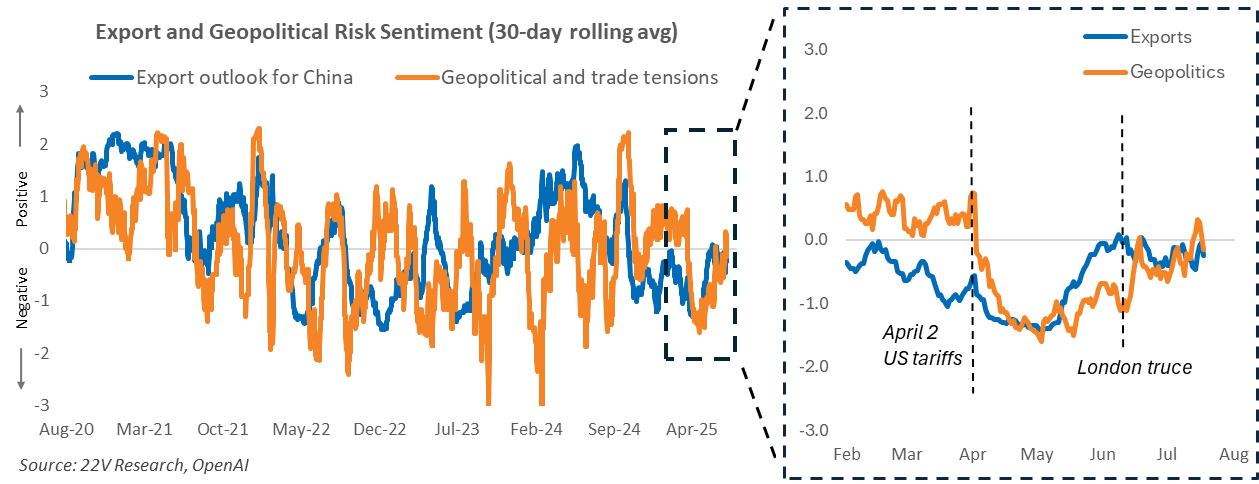
Analyst sentiment towards China’s exports (blue line) and geopolitical risks (orange line) have swung to neutral in the last month, following the truce on rare earths in London. A likely Trump-Xi meeting later this fall is an important watchpoint but we see major tariff relief as quite unlikely. Export growth is likely to slow in the second half as the front-loading of export orders fades and as transshipment of Chinese exports to the US through third markets comes under greater scrutiny from Washington.
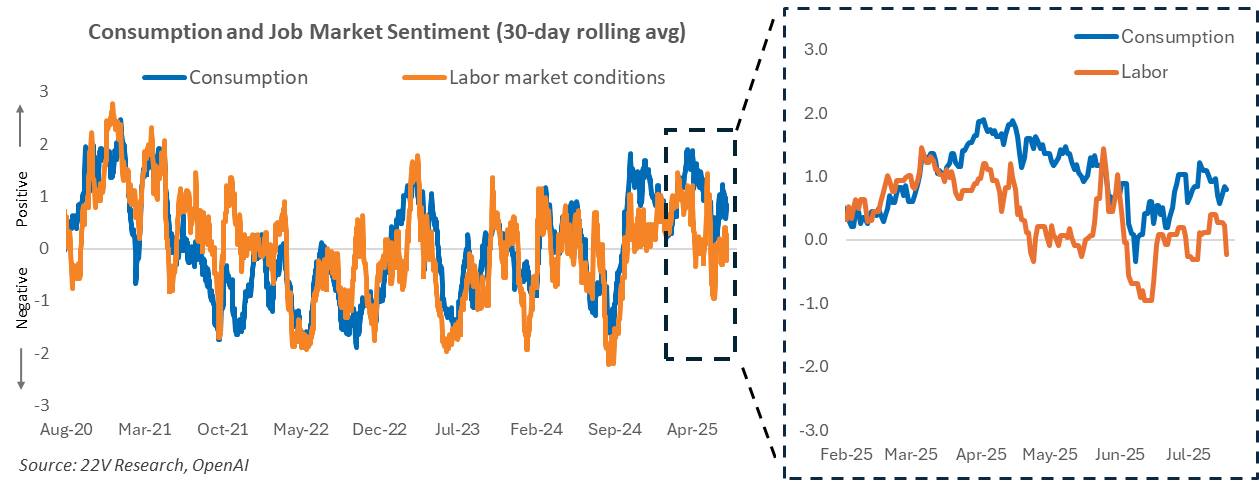
The headwinds for the external sector highlight the importance of the outlook for domestic consumption, a relative bright spot this year. While consumption sentiment (blue line below) remains positive, it has faded a bit since the spring. One reason is the uncertain funding outlook for the trade-in program in the second half. Another reason is the weakness of the labor market, which analyst sentiment (orange line below) probably understates. Such caution is appropriate, as we do not expect policy support to be strong enough to lift retail sales back to the growth levels of earlier this year.
CHESS is a collaborative project, leveraging the expertise of Sophia Wang, 22V’s Director of Quantitative Research, and China-based economic consultant Dr. Fei Han. The authors express thanks for contributions and insights.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.