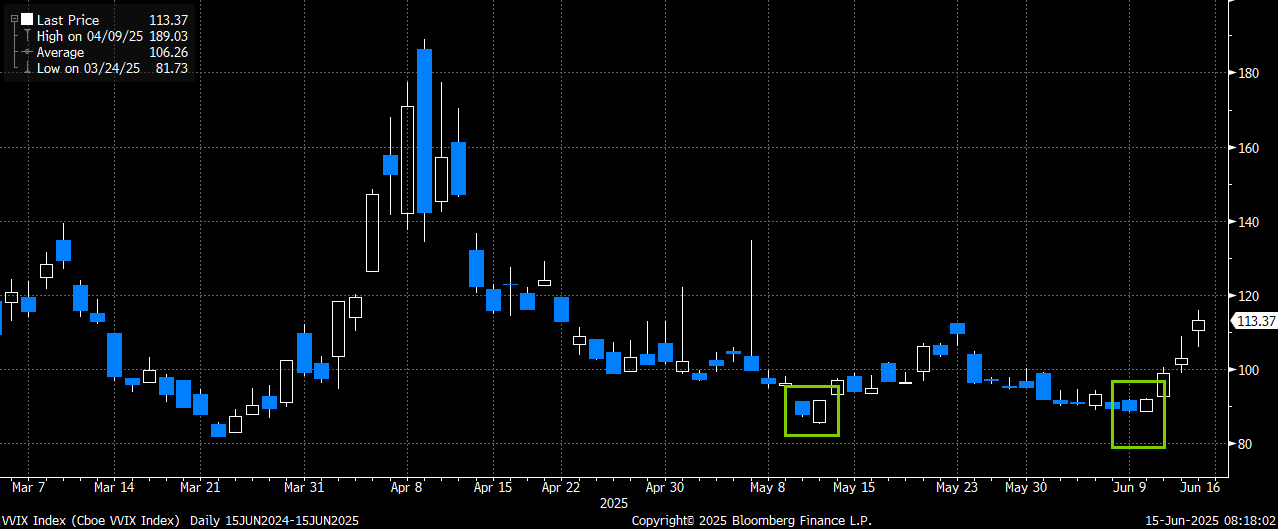
While the major stock indices were all down small last week, the biggest mover was volatility (VIX) which saw a nearly 25% spike (with much of the move happening on Friday after news broke on Thursday night of the escalation in the Middle East). Of particular note was that VVIX (the vol of volatility index) had already started to move higher earlier in the week (even as markets stayed bid and before the news of the escalation had hit). It was the potential for this type of move higher in volatility that made me suggest getting long vol in my note last week (here). While volatility did spike on Friday, we could continue to see a much higher move given the low level it had gotten to before the conflict and obviously depending on how the situation plays out. In addition, this move in vol on geopolitical concerns likely raises the floor in vol/VIX I have been mentioning and reinforces my belief that when volatility gets to those low levels it needs to be owned.
VIX index spiked by ~ 25% last week after getting back down to the March/May lows

The VVIX index bottomed on Tuesday – well before the Middle East news hit and as markets were still rallying (we saw a similar move in May)
Own financial stock hedges for earnings season
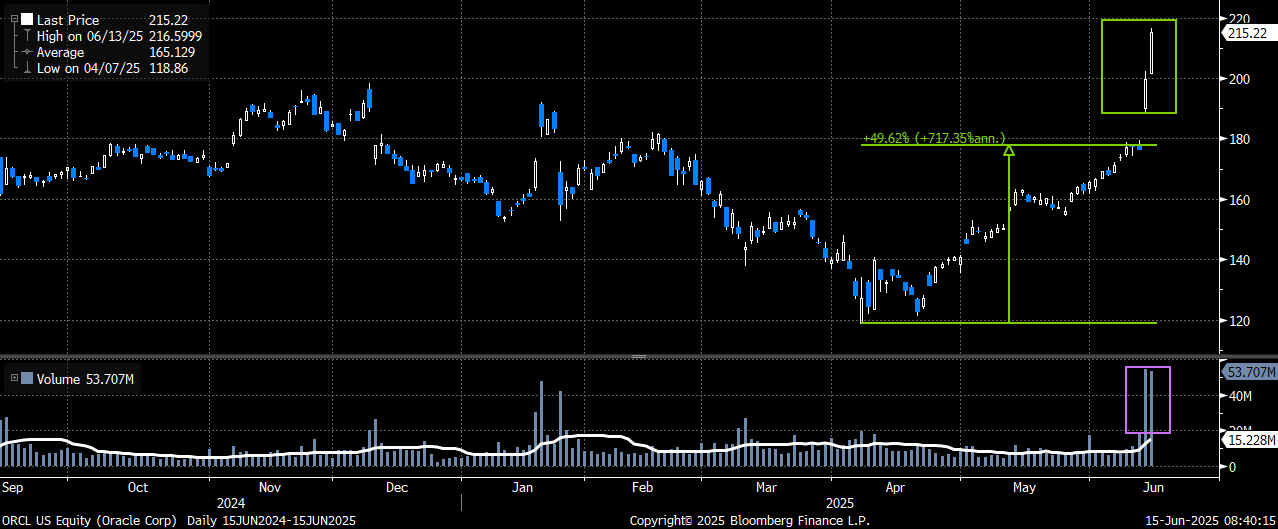
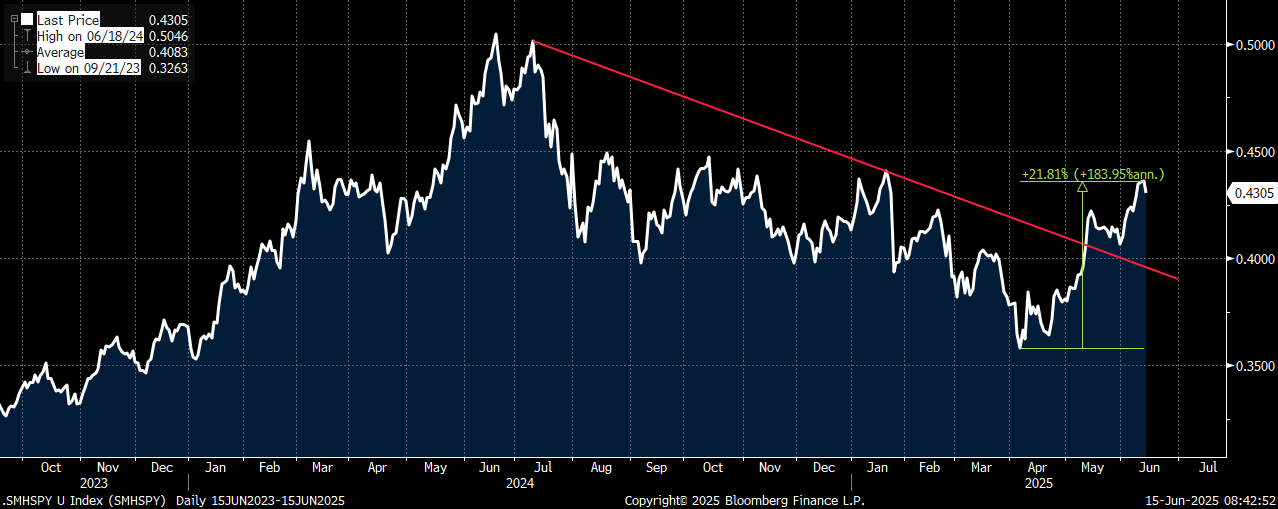
Before the pullback on Friday, the market was once again being led higher by the tech/AI trade. Look no further than the 21% rally in shares of Oracle (ORCL) after they released earnings on Wednesday after the close. What makes this move higher even more impressive is that 1) Oracle had already rallied nearly 50% into the report and 2) shares gained ~ 7% on Friday (on massive volume) even as the rest of the market was under considerable pressure. Semis (SMH) have also regained their leadership role in the market with the SMH/SPY relative spread up more than 20% since the April lows and the spread breaking above the downtrend that had been in place for nearly a year.
Extremely impressive action in Oracle on earnings. Shares rallied 21% on massive volume even after the 50% rally off the lows into the report
Semis (SMH) back to a market leadership role with SMH/SPY spread up 21% from the lows and decidedly above the July ’24 downtrend
With the AI sectors now working, I wanted to focus on other sectors that could be more likely to come under pressure over the next few months (and thru earnings season). One that I have identified is the financials (XLF), and I suggest owning sector hedges now for the upcoming earnings season:
Own XLF August put spreads
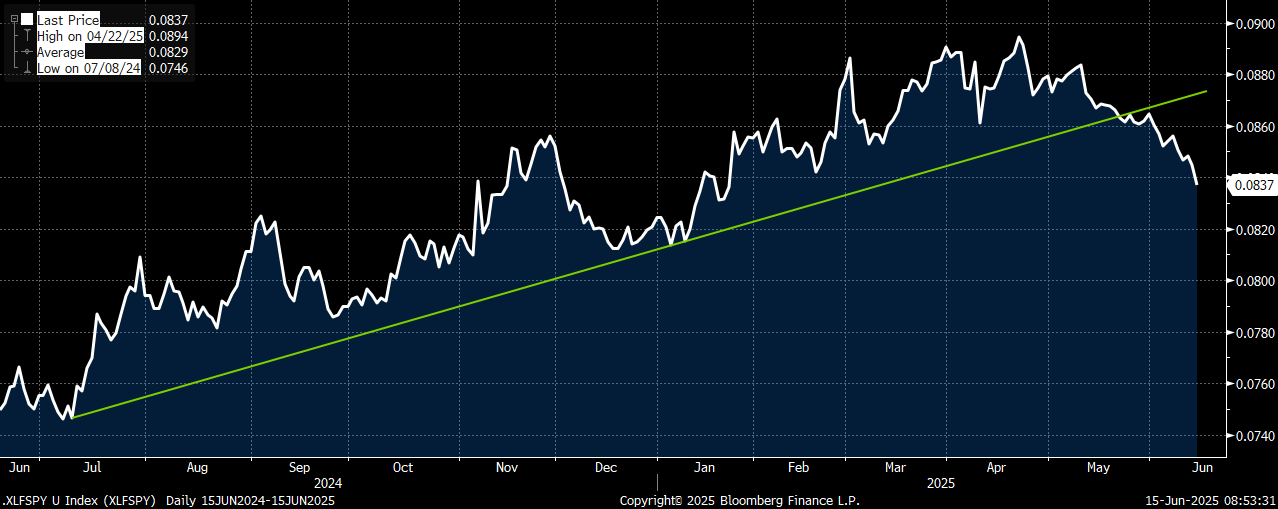
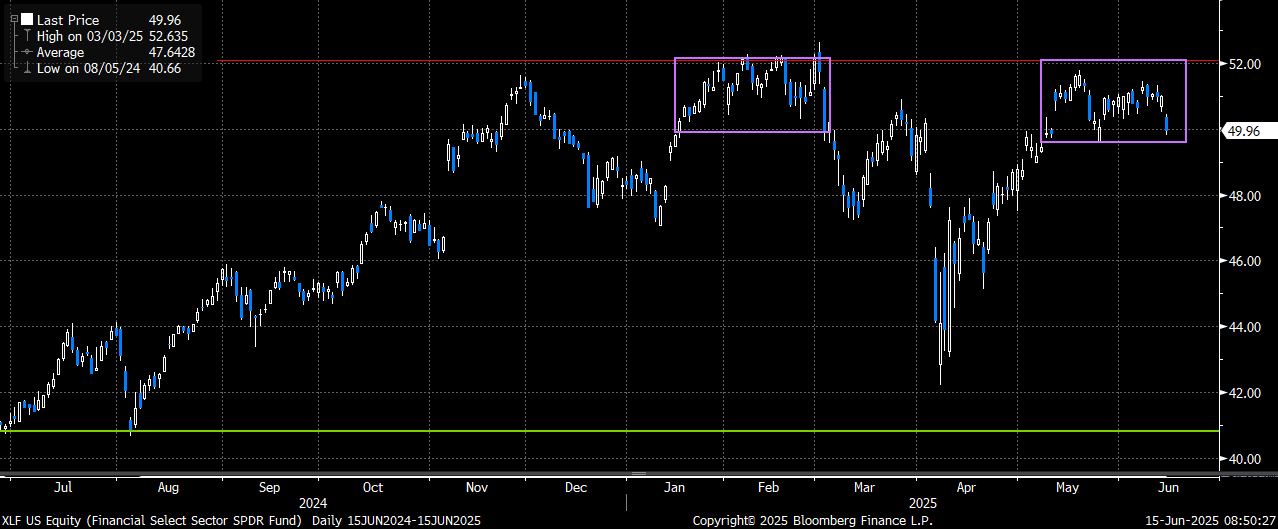
The current action in the main financials etf reminds me a lot of the move back in February. Back then we also saw a sharp rally to the $52 area, followed by sideways action (as the market kept rallying) and then a break below support. What is perhaps even more concerning now for XLF is that it peaked on a relative basis to the market (SPY) back in April and has since broken below the 1-year uptrend. This may speak to the strength again in the tech/AI trade, but the fact that financials aren’t outperforming now means they are likely more susceptible for a more meaningful decline.
There are two other concerns I have regarding XLF that also make me want to own hedges. First, the largest weight is Berkshire Hathaway (BRK/B) @ 12.7%. While BRK/B did a lot of the heavy lifting for XLF as the market sold off in Feb thru April and money rotated to “safe” names, it has since come under a lot of pressure. The combination of the growth trade working, Warren Buffett stepping down and Insurers under pressure on pricing concerns have all weighed on the stock. If BRK/B remains under pressure it will continue to make it more difficult for XLF to rally meaningfully (and it could help bring it lower). Second, the news on Friday that several large retailers were considering their own stablecoins hit both Visa (V) and Mastercard (MA) especially hard with both names down ~ 5%. These two names make up ~ 15% of the total weight in XLF and both had been a large reason why XLF was able to rally back to the highs ~ 52 after the April selloff as both names had hit new all-time highs early last week. Should these concerns over stablecoin continue to weigh on both stocks then XLF will continue to feel the impact (XLF was down ~ twice as much as SPY on Friday).
Against this backdrop, XLF put vol for August still remains towards the bottom-end of its recent range and put skew remains very favorable with the out of the money puts trading at a sizeable premium to the closer to the money puts. Therefore, buying August put spreads is an attractive way to hedge downside risk for the next few months and thru the upcoming earnings season.
Trade:
Buy XLF Aug 49 puts
Sell XLF Aug 42 puts
Costs ~ .97 (XLF Fri close ref price of 49.96)
Trade Details:
- Buying the August XLF put spread hedge following rally back to the highs after the April selloff
- Starting to see some “cracks” in the trade as some of the largest weights now under pressure (BRK/B, MA and V)
- XLF/SPY relative spread peaked in April and is now below the 1-year uptrend support
- Put spread starts less than 2% below spot (XLF was down 2% just on Friday) and is capped to the downside 16% lower at $42 (which was also the April low for XLF)
- Hedge offers a nearly 6.25x to 1 max payout and captures earnings for all the top-weighted names
- Please contact me or the 22V sales team for updated pricing and execution capabilities
XLF with a very similar technical pattern to what we saw back in Feb (before the sharp correction)
XLF/SPY relative spread peaked in April and is now below the nearly 1-year uptrend support