Perhaps the most interesting aspect from the markets last week was that even as stocks continued their climb, ending the week on their highs, we saw volatility put in a low well earlier in the week. Looking at the VVIX index, which is essentially a measure of the volatility of vol, we see that it bottomed on Tuesday morning and then actually rose along with stocks. I believe this is an important distinction as VVIX tends to trade inversely to the market, so if vol was unable to make new lows as stocks continued to rise, this could be a signal of a quasi-floor to vol in the short to medium term. I believe there are important ramifications if this proves to be true regarding volatility. First and foremost, it absolutely would mean that owning vol here becomes far more attractive since it may be signaling that vol should likely only move up from here and the lows have been made for now. With the late Friday afternoon news of the US credit downgrade by Moody’s we should see stocks open the week lower and vol move higher. But, if we see stocks brush this news aside (for now), then I would absolutely consider being long vol at current levels given how it currently behaves.
VVIX index made a low on Tuesday (right above where it bottomed in March) and moved up even as stocks rallied further

If vol has in fact bottomed, one trade that should now be considered is owning VIX calls or wide call spreads. A big headwind to owing index puts is that not only does vol move lower as markets rise, but the delta of the put also moves lower as markets go up. If you own VIX calls, and vol doesn’t move meaningfully lower, then the delta of the call should stay constant (even if the market should rally further). I would also expect to see a decent move higher in vol should we see a meaningful pullback in the markets, especially after the sharp rally off the lows. Therefore, VIX calls could be a very interesting way to hedge against any market decline here over the next few months. The other trade to consider with vol at these levels is outright owning puts (or calls) in the main stock etf’s (SPY, QQQ and IWM). Again, if vol stays at this level or moves higher even if stocks should advance more, then owning vol outright becomes an attractive proposition. Let’s see how markets, and vol, react to the Moody’s news from Friday, but should we see a rally back on the news then I would absolutely consider buying VIX calls or call spreads in June or July. Please feel free to reach out to me to discuss specific structures.
Gold (GLD) at a key inflection point – great spot to own vol depending on viewpoint
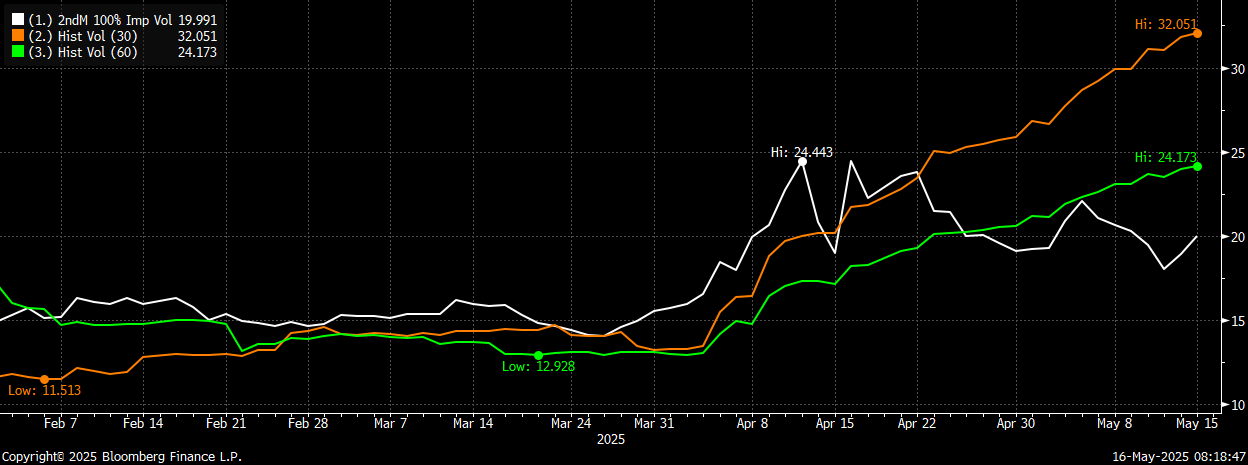
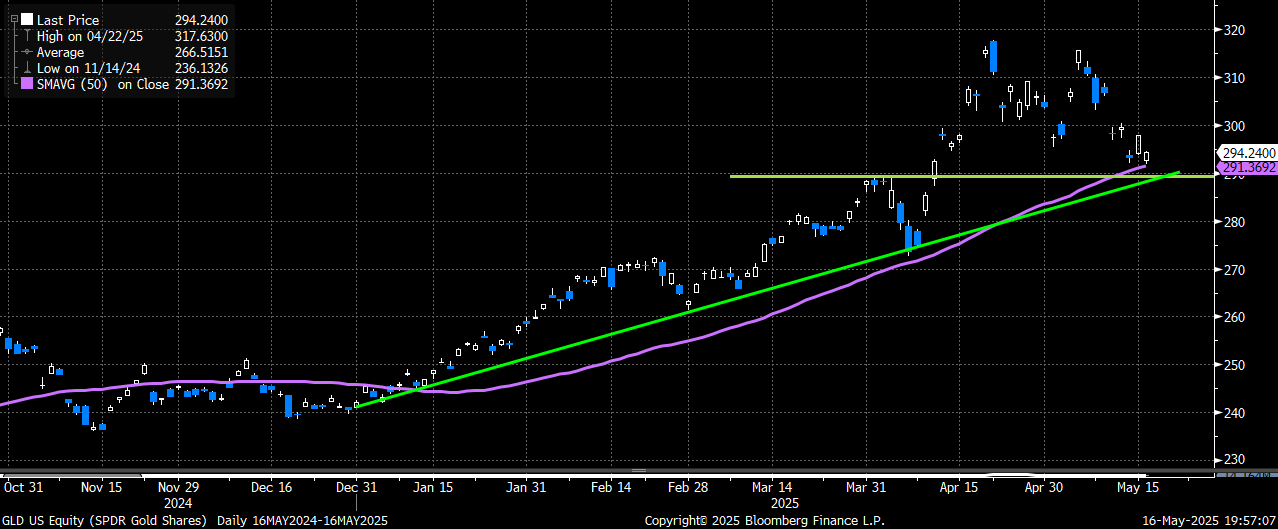
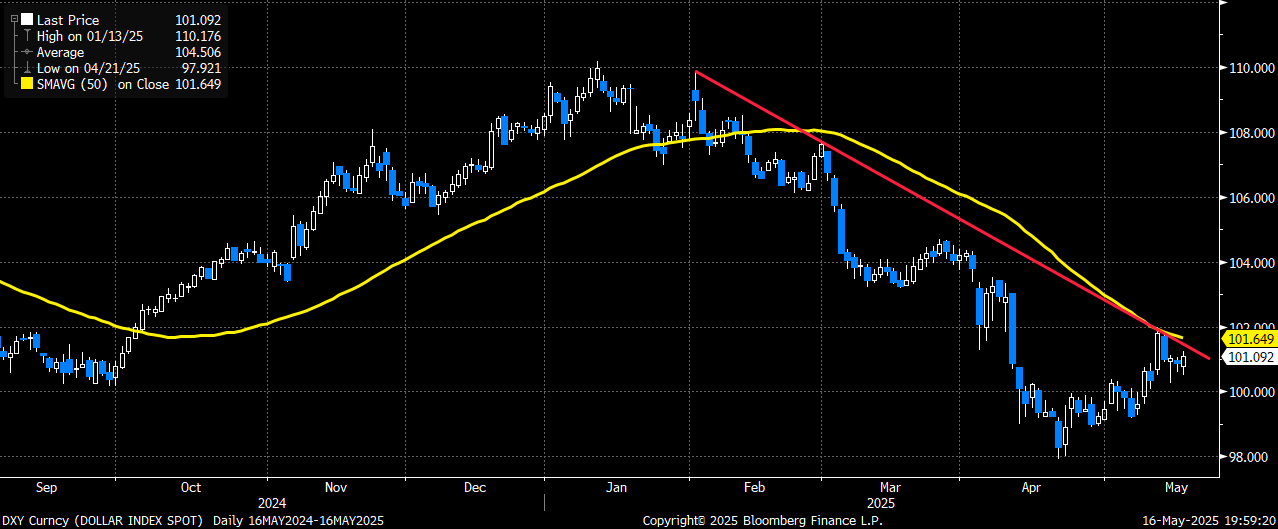
After breaking out to new highs in April, we have seen gold consolidate as the risk-on trade has taken hold and the US$ has rallied along with risk as well. Both gold and the US$ index (DXY) now sit as key levels (gold at support and DXY at resistance). It seems very unlikely that we just stay at these levels for a prolonged time given the realized volatility we have seen in gold. With 2-month (June) implied vol for GLD ~ 20, and both 30-day and 60-day realized vol way higher, this should be an opportune time to own GLD vol. If bullish on gold, then I suggest tactically adding upside calls, and if concerned about a further move lower (rally in US$) then I would target owning puts that are just below the key 290 support level. I looked at both put skew and call skew for GLD and since neither are at attractive level, and implied vol continues to trade at a sharp discount to realized vol, I prefer to own calls or puts outright here (again depending on current viewpoint).
Trade if bullish gold:
Buy GLD June 301 calls for ~ $5.20 (GLD 294.24 Fri close ref)
- Buying the 40-delta June call following 8.3% decline from the April highs
- GLD implied vol has moved down by nearly 20% and continues to trade at a discount to realized vol
- Defined risk way to play for a move back higher with gold sitting right at support and US$ at potential resistance
Trade if looking to hedge a possible break in gold:
Buy GLD June 288 puts for $3.75 (GLD 294.24 Fri close ref)
- Buying the 32-delta June put that is just below the clear support for gold
- GLD implied vol has moved down by nearly 20% and continues to trade at a discount to realized vol
- Given how technical gold (and most commodities) trade, could see further selling on a break below key support
- Please reach out to me or the 22V sales desk for updated pricing and execution capabilities on either trade
All roads lead to the 290 level in GLD – April breakout level, Jan uptrend support and rising 50-day
US$ index has also rallied to a potentially key resistance level – 50-day and Feb downtrend
GLD 2-month (June) implied volatility continues to trade at a sharp discount to 30-day and 60-day realized volatility