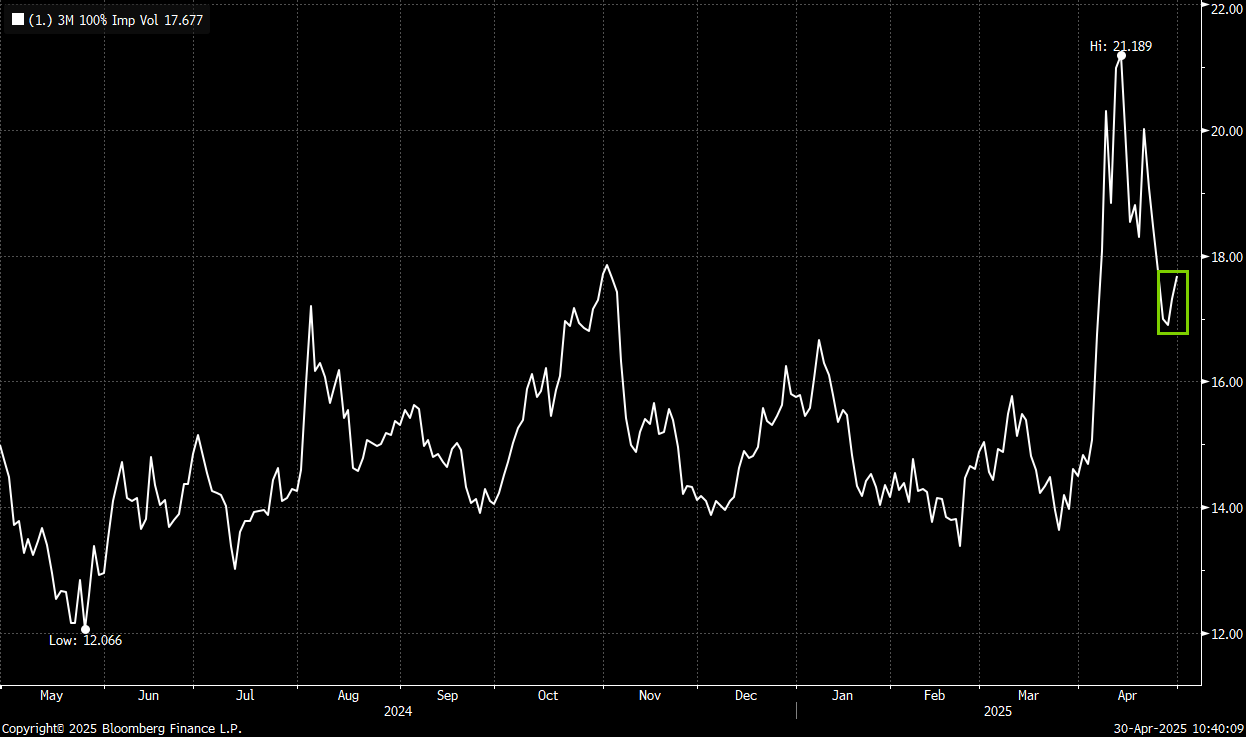
I collaborated with 22V Economist, Peter Williams, on the following idea as an interesting way to own SPY hedges, after the sharp rally off the lows, that are fully funded by selling bond (TLT) volatility:
With bonds (TLT) continuing to trade in a range, and implied volatility still well above the lows, we like the setup here to sell “expensive” bond vol to buy “tail” hedges on the equity market (SPY). Our thought is if yields breakout of their current range (either to the upside or the downside) that stocks would not fare well given the likely policy and econ shocks that would force the issue.
From Peter Williams:
In the near-term the economy has two clear risks which may pressure equities lower.
- There may be a mechanical soft patch in the data starting in May’s data, given tariff front-loading in Feb-Apr (as the Q1 data showed this morning). Bonds likely rally in this world.
- If the China tariffs largely stick and we see little broader progress in actually bringing implemented tariffs down (goods on boats and shelves care less about a potential deal, same applies to trucking and mom & pop goods retailers as going concerns), the optimism embedded more clearly in equities than rates will start to rerate some to the downside. Given the lessons of the covid-era supply chain snarls it is less clear to me how bonds should trade in this world (especially with a trough in rates priced at roughly 3% and a lot of inflation uncertainty).
There are additional more medium-term risks which could become salient to markets as we move through the early summer. These policy and supply shocks are likely to weigh on bonds and equities jointly but with so much steepness in the curve already it may be more of a pricing out of cuts than substantial breakout in LT yields.
- Inflation expectations may continue to move higher more actively curtailing a Fed which remains inflation cautious.
- If little progress is made on tariffs we may more sharply go back into a stagflation / sell-US exceptionalism trade.
- Expansionary fiscal policy that further jettisons budget orthodoxy may not be greeted favorably by markets. Yes, there will be some growth offset of the tariff shock but that would sustain higher rates and inflation over the medium-term, in addition to leading to higher issuance expectations.
With stocks having rallied by as much as 15% off their lows (yet still unable to eclipse either their pre-tariff levels or the 50-day), we like owning out of the money puts (funded by selling TLT vol) in case we see a re-test (or worse) of the lows hit just a few weeks ago.
Trade:
Sell TLT Aug 85 put/95 call strangle @ $3 (TLT 89.65 ref)
Buy SPY Aug SPY 490 puts for $8.95 (SPY 549.30 ref)
- We suggest selling 3x as many TLT strangles given underlying price discrepancies – makes trade effectively costless
- Using the recent support/resistance levels in TLT as strikes we want to sell to finance the cost of buying the SPY downside put in August
TLT back in the middle of the 85-95 range it has traded between since October

TLT 3-month implied volatility remains well above the 1-year lows, even as TLT continues to be range-bound