

SUMMARY
- 22V’s China Economic Sentiment Series (CHESS) tool shows that analysts commenting in China’s domestic media are relatively optimistic about the outlook, especially hopes for stimulus; our in-house view is more guarded, as we expect Beijing to focus on maintaining financial stability in coming months, with boosting growth a secondary priority
- Analyst sentiment also looks overly optimistic to us when it comes to expectations for the property sector and household consumption; there is also downside risk for domestic equities, but Beijing’s willingness to support this market is more clear-cut than in the case of property
- Near-term watchpoints for the outlook include the health of consumption and property sales during the upcoming Lunar New Year holiday, preparations for the annual National People’s Congress in March, and signals from Washington and Beijing on the US-China trade tensions
Our outlook for China’s growth and markets in 2025, published earlier this week, is subdued (link HERE). Vicious cycles centered on the property market will continue to drag down domestic demand. Exports were a key growth driver last year but face potential US tariffs. We expect Beijing to respond to these challenges with a policy mix that prioritizes financial stability over growth, with only moderate stimulus in the first half of the year. In the second half, rising economic and political pressures will increase the probability of a growth-oriented policy pivot, but this is hardly guaranteed.
In this report, we compare our in-house view with the views of macro analysts in China, using 22V’s proprietary China Economic Sentiment Series (CHESS). CHESS uses ChatGPT to measure the sentiment of analysts commenting in China’s domestic financial media. We find that analysts are more positive about the near-term macro outlook, especially when it comes to expectations of stimulus support. Views on property and consumption also look overly optimistic to us. This creates a risk of disappointment in coming months, even if Trump does not impose significant tariffs on China. Please see further details below.

Stimulus expectations seem high
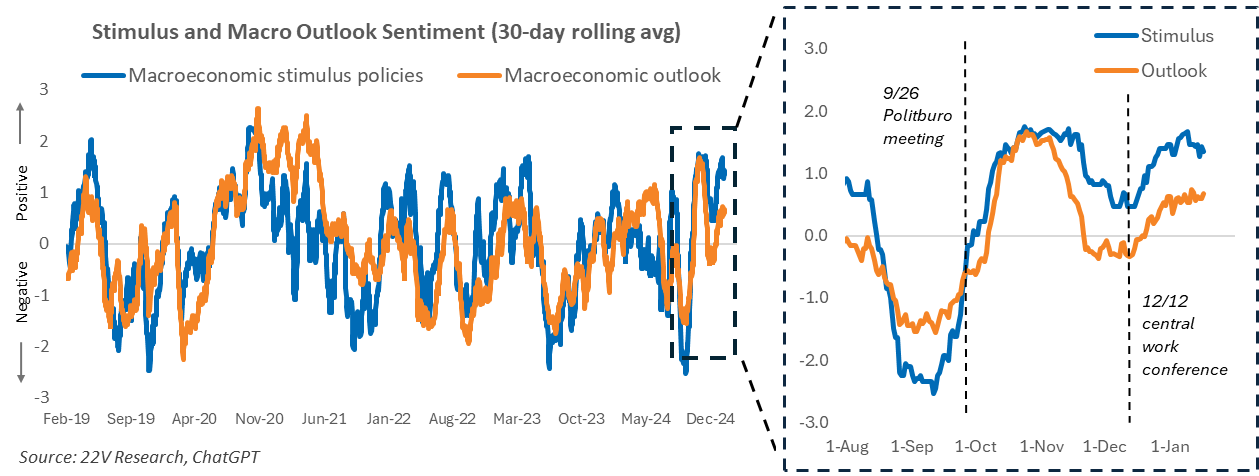
The chart below shows two key CHESS indexes: sentiment towards stimulus (blue line) and sentiment towards the broader macro outlook (orange line). Both series have seen major swings after policy events. Expectations for stimulus and growth surged after the Sept. 26 Politburo meeting signaled a “policy pivot” intended to ease downside pressures on growth. Sentiment slid after underwhelming follow-up announcements in October and November but picked up again after the Dec. 12 Central Economic Work Conference (CEWC). Our takeaway from the CEWC was to expect only modest support for growth (see our write-up HERE), but analyst sentiment towards stimulus remains at quite high levels. China’s consensus-beating GDP print on Jan. 17 also helped boost sentiment towards the macro outlook.
High expectations for stimulus suggest room for disappointment in coming months. As our 2025 forecast report detailed, Beijing will likely announce a growth target of “around 5%” at the National People’s Congress in early March, but it will backed by only a modest stimulus package. Measures to support financial stability – including stability in the USDCNY exchange rate – will take precedence over aggressive easing. The chances of stronger stimulus increase in H2, by which time growth momentum will have faded and Beijing may be dealing with the imposition of US tariffs.
Property sentiment is vulnerable to another dip
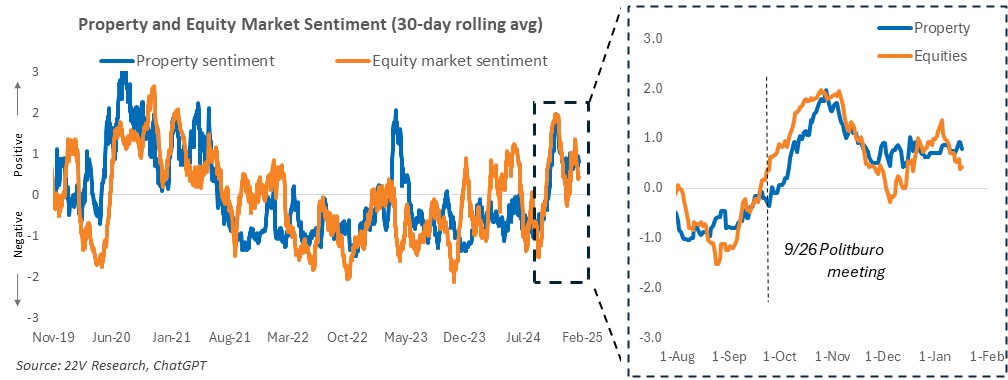
Analyst sentiment towards the property sector (blue line) and the equity market (orange line) have both declined a bit from their post-pivot highs in September. We regard property sentiment as the most vulnerable to further disappointment in coming months.
While housing sales in December rose into positive territory year-over-year for the second straight month, other indicators (including a continued fall in prices of existing homes) suggest that the post-pivot rebound in property sales is already running out of steam. We are not optimistic that Beijing is ready to implement the type of fresh policy measures necessary to stabilize the sector, which would involve the central government using its own balance sheet to clear excess housing inventory rather than continuing to place the responsibility on cash-strapped local governments.
We continue to think that Beijing will honor an implicit put on the equity markets, extending support as necessary to prevent domestic markets from falling back to pre-pivot lows. But with current prices now 15% higher than those lows, there is some downside risk before Beijing intervenes. The positive is that the political and financial hurdles necessary for Beijing to boost support for equities are lower than is the case for property.
Labor market is the Achilles Heel for consumption
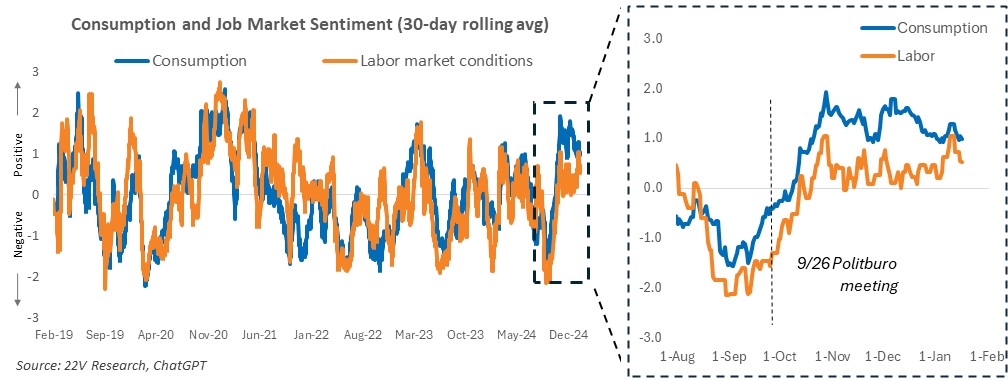
Another area in which our outlook is more guarded than CHESS sentiment is consumption. On the plus side, Beijing has signaled more support for consumption this year: we expect fiscal support equivalent to 0.6% of GDP, which would fund a continuation of the consumer trade-in program and limited household income subsidies. But this is too small to drive a broad-based consumption rebound in the face of stiff macro headwinds from a weak labor market and from falling homes prices. We expect household expenditure to remain anemic this year.
Exchange rate and export sentiment are appropriately cautious
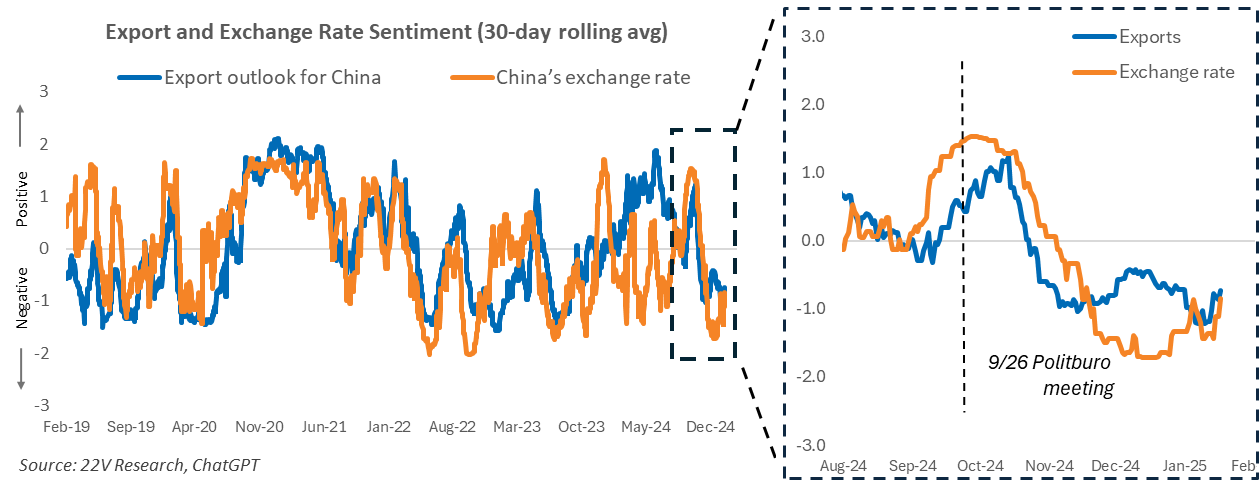
Domestic analysts are taking trade risks seriously: export sentiment and exchange rate sentiment have both declined since Trump’s election and remain negative. That outlook seems appropriate. In addition to tariff risks, the CNY is weighed down by a gap between US and Chinese interest rates that is very wide by historical standards. That said, we continue to think that the PBOC will be cautious about signaling tolerance for a weaker CNY and will aim for exchange stability, especially before the US imposes tariffs.
Near-term watchpoints:
- Lunar New Year holiday (starts Jan. 29): We will be watching for the robustness of household spending and interest in properties during the holiday, as well as possible short-term measures to boost confidence by the central government and local governments.
- Preparations for the National People’s Congress (mid-Feb to early March): After the Lunar New Year holiday concludes on February 4, Chinese officials will focus on preparations for the annual NPC meeting (starts March 5). Signals and speculation as to the NPC’s announcements will shift into high gear.
- Signals on the US-China outlook. Trump has threatened a 10% increase on tariffs on imports from China, starting February 1, over China’s continued export of fentanyl precursors. At the same time, Trump has signaled some openness to exploring a trade deal with Xi Jinping. We will be watching this front closely.
CHESS is a collaborative project, leveraging the expertise of Sophia Wang, 22V’s Director of Quantitative Research, and China-based economic consultant Dr. Fei Han. The authors express thanks for contributions and insights.

