

Rates Trapped Between Two Economies: Housing vs Overall Activity and Sticky-ish Inflation
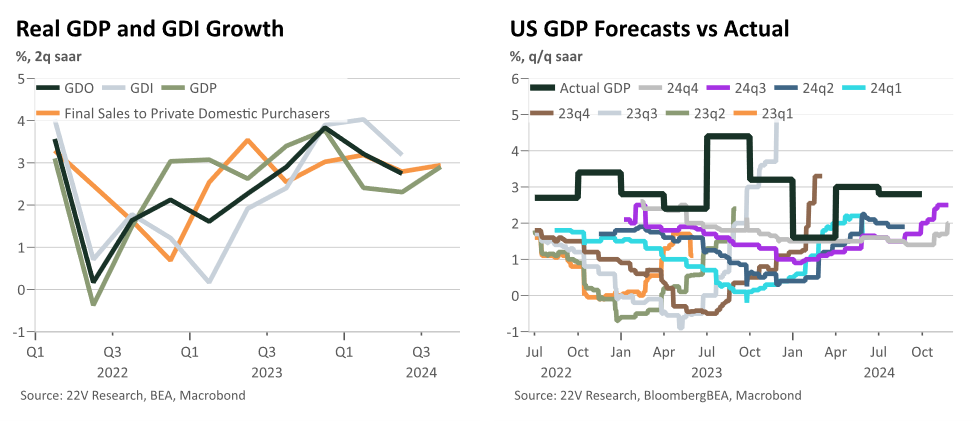
- Looking at aggregate topline performance in the US economy would not suggest that policy rates or longer-term rates have been obviously restrictive in recent quarters (the most recent y/y GDP is 2.7%, final sales to private domestic purchasers 3.1%, and core PCE 2.7%).
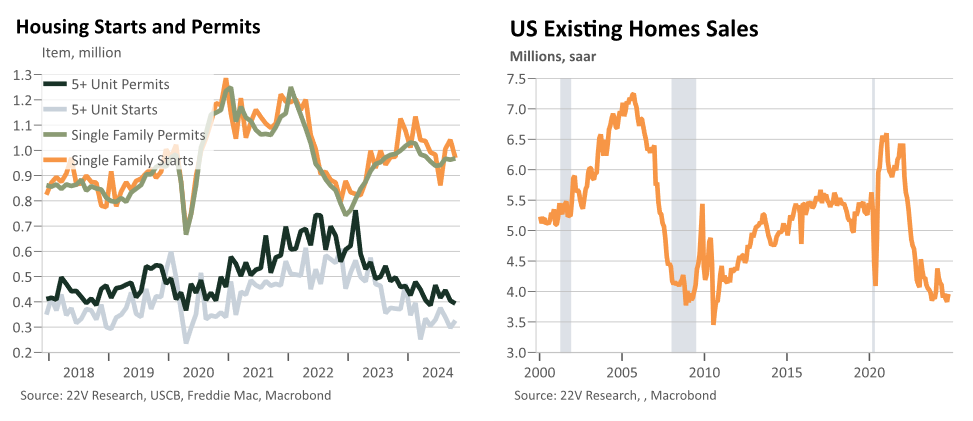
- However, rates sensitive spending, particularly for existing homes, has been sluggish at best with only mild recoveries from initial legs down following the beginning of the inflation/tightening cycle.
- It is not clear to me that in the near-term there is a 10y rate which is jointly compatible with a healthy level of transactions in the overall housing market, along with a rebound in broader rate sensitive spending, and inflation settling in back towards, or durably at, 2%. Given where the Fed’s mandate lies, this means that housing is unlikely to be able to really accelerate notably until, at least, is more clearly durably anchored to target and, as a result, housing will have roughly 0 impulse to growth going forward.
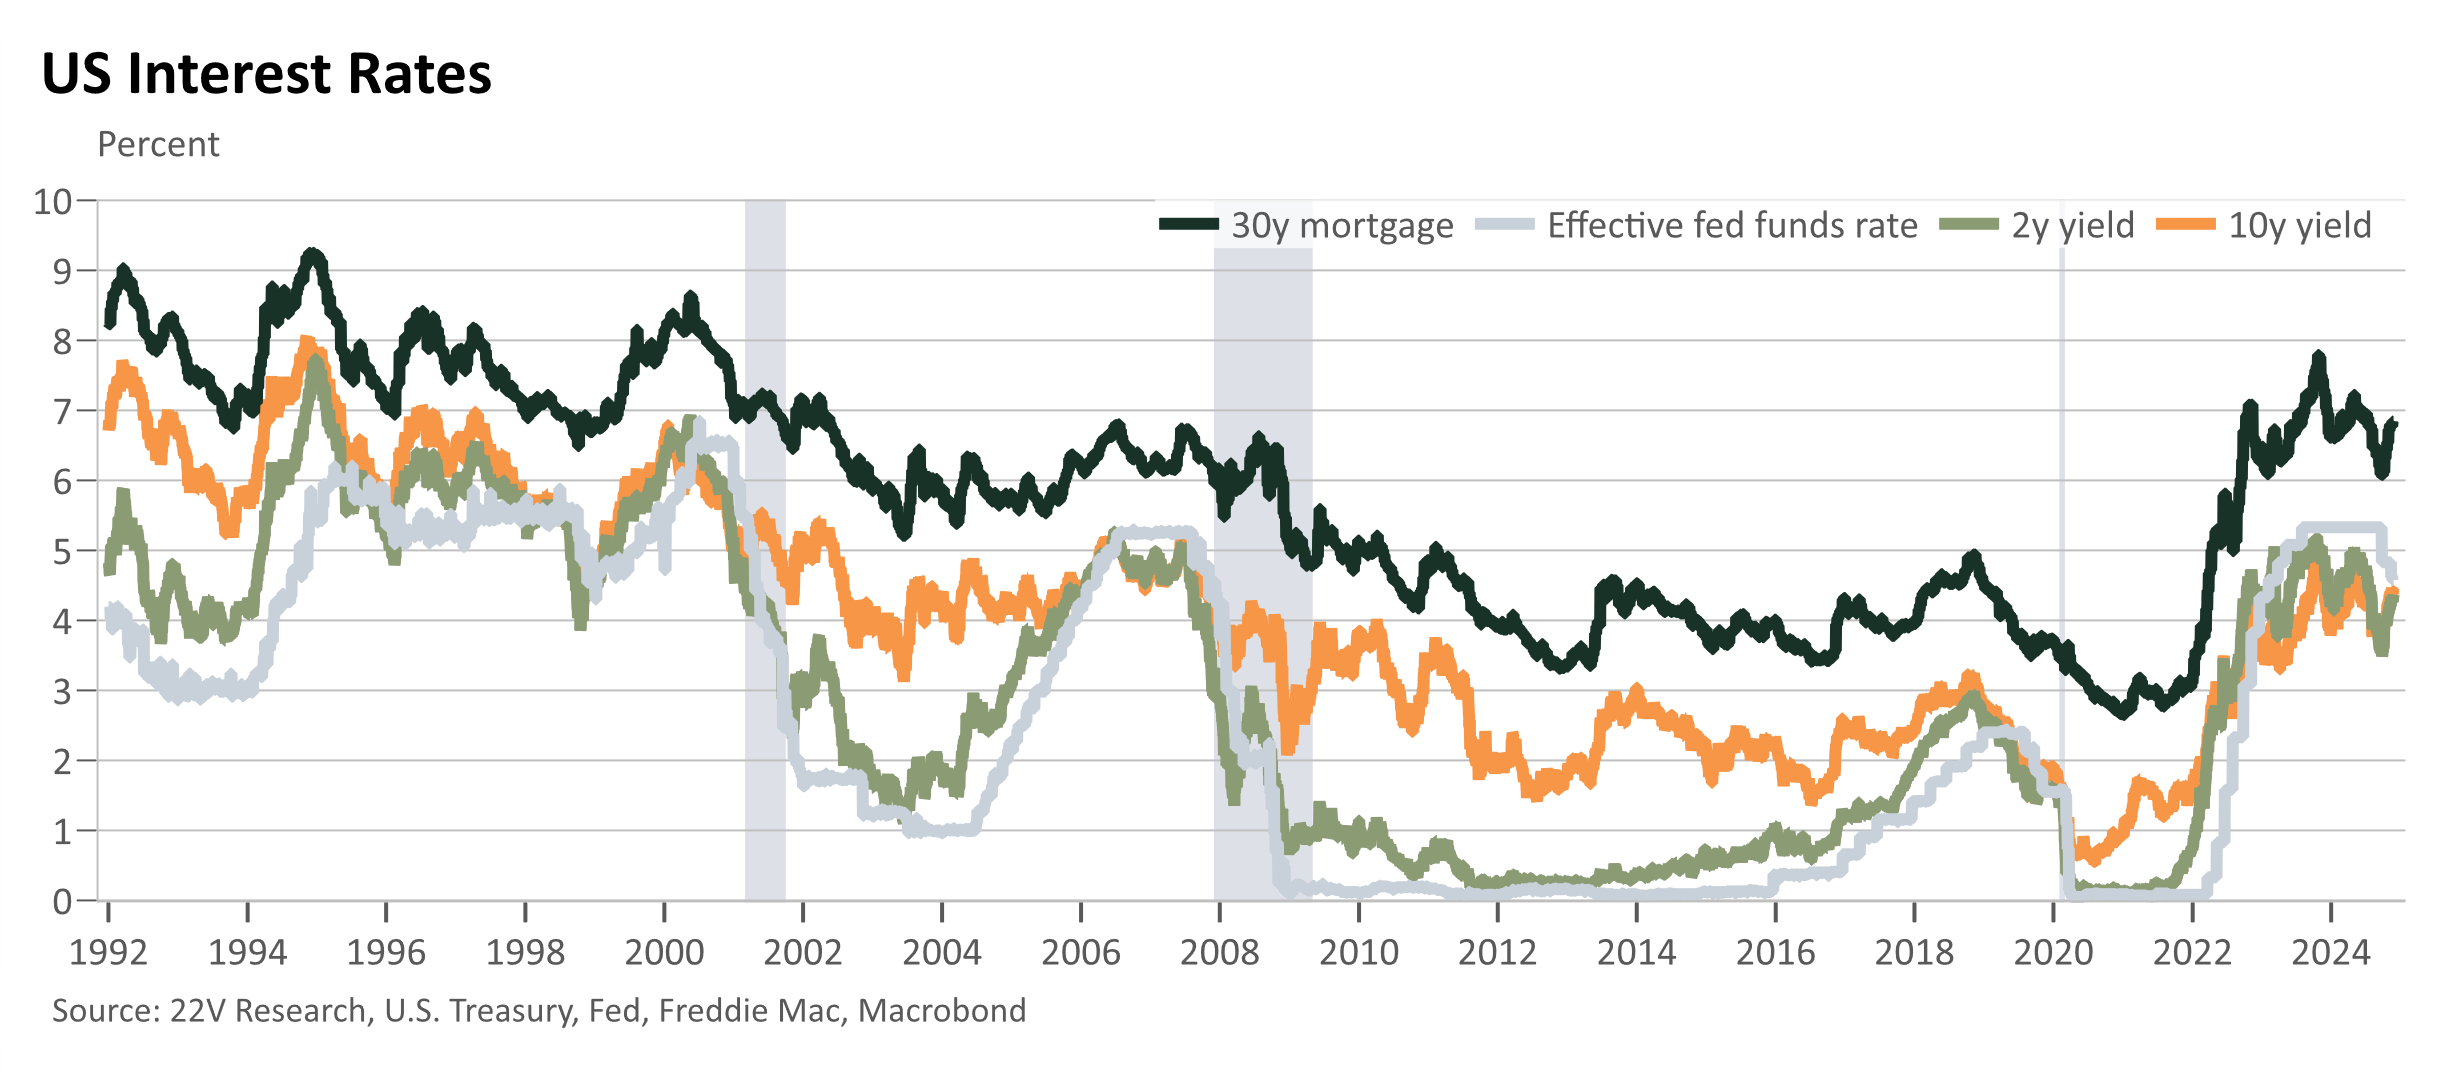
- My base case remains that 10y UST rates continue to range trade in the low-to-mid 4s as the Fed cuts rates 2-3 more times total, with longer-dated forwards driven by dualling inflation and recession concerns (currently neither is obviously dominant in pricing).
- Eventually markets will start to pivot to what comes after the pause/terminal. That will likely mean another move higher in rates, if that base case comes to pass, but for now that seems a ways away.
Many, but not all, Fed speakers have been in the habit of describing policy as restrictive on the basis on the activity in classically interest rate sensitive sectors, housing most notably. However, the topline data has continued to come in remarkably strong over this same period. While inflation has fallen notably it is not clear that its settling in exactly to target; on the other side of the mandate the labor market appears to be continuing to gradually ease but long-building recessionary fears have not been realized. Admittedly, as with so many things post-covid, disentangling the impacts of varying supply-side shifts and shocks and the reopening boom versus underlying structural and demand forces is a remarkably imprecise endeavor.
Given that the neutral rate, and thus how restrictive the stance of policy is, is a whole economy concept and not one specific to rate sensitive spending (rate-sensitive spending the channel not the goal), the Fed’s default description of policy’s stance has always struck me as a bit strange, even when it has been obviously correct that rates were somewhat restrictive under any plausible estimate of neutral.
With 75bps of rate cuts now and done at another 25-100 to go (25s in Dec, Mar, and June remain my base case but all seem increasingly tentative), the fed funds rate is likely still somewhat restrictive but that is less obviously the case than it was. This is particularly true if we think of the likely terminal rates as something “more neutral” rather than outright neutral.
The 10y rate is likely to continue range trading between 400-450bps in the short-term, in an unhappy equilibrium where the housing market can never really show outright strength but will be a roughly 0 contribution to growth going forward. In other words, to keep risk of another inflationary shock from increasing too high, the housing market, rate sensitive investment, and home equity withdrawal can’t rip. The 10y’s range will likely[1] trend higher as the Fed debate starts to shift from “where is terminal?” to “what happens after terminal (hikes)?”
Looking at the topline activity data in the US economy, in both nominal and real terms, it would be hard to say that the current level of interest rates is obviously restrictive. As the rate hiking cycle accelerated in 2022 the drag on overall GDP growth was much more obvious suggesting that rate of change in rates, and the associated moves wider in credit spreads and the broader end of the post-reopening boomlet, was a substantial drag on growth. Since then, growth has stabilized at a well-above trend pace. GDI had been running much slower than GDP in the as-reported data for much of the past few years; however, positive revisions to the levels of GDI and GDP in September eliminated the GDI-based argument that activity was being notably restricted by high rates.
Not all of the strength in the recent topline activity data can be seen solely as a result of the economy’s indifference to higher-for-longer rates (aka a higher neutral rate). Some of this is likely due to the fading of supply chain shocks, the surge in prime-age participation and immigration, and other positive supply-side developments which have enabled relatively costless disinflation so far. These would be better thought of short-term boosts to the rate of potential growth or simple exogenous demand shocks. Still, the persistent forecast outperformance over the past two years suggests that the drag from higher rates on overall economic activity was likely overstated and that with many of the forces which dragged down neutral following the GFC now well in the rearview, neutral rate estimates should be notably higher than those anchored to the 2008-15 era (a category in which I would include the Fed’s).
On top of the strength of the real economy, inflation’s descent has been noisy and more sluggish than expected. There has been a habit of a almost fully incorporating downside surprises into near-term forecasts while at least partially looking through upside surprises (the Fed’s mark down of its 2024 core PCE to 2.6% in September will likely see it revised up to 2.8-2.9% in December). Overall, the data seems to suggest that 2% is more of a soggy floor for inflation than a symmetric anchor.
Despite the strength of overall economic activity, housing has been a mixed bag in recent quarters. After the surge in activity and starts from 2020H2-22H1 the market reset notably lower and then, despite the move higher in average rates over the course of much of 2023, single family housing starts have seemed to stabilize at or just above pre-covid levels. The existing home sales market though has remarkably weak with only the briefest rebound arresting its broader weakness. The relative strength of starts is at least partly downstream from this as there are more levers available for builders to meet pricing needs of prospective purchasers than existing homeowners have.
This assumes that the market doesn’t assume Fed hikes kill off the cycle in the near-term and that longer-dated forwards directionally follow STIR higher. Given our very limited sample size here, I’ll stick with the idea of a level reset higher in rates with perhaps a bit of fiscal and inflation-induced additional term premium. ↑

