Back Economics

Bessent > Warsh

Published on November 25, 2024

Download the PDF Report

By

Gerard MacDonell

Trump’s choice of Scott Bessent over Kevin Warsh for Treasury Secretary seems like an upgrade from the perspective of substance.  Bessent’s bio suggests he is his own guy and can do, not just solicit.  But for markets, especially in the immediate future, there may be two other aspects of the pick that are more important, although also relatively constructive.


First, there is much ballyhoo about how Bessent understands markets and is a great “strategist,” to use Trump’s term.  Such commentary seems to misunderstand what the Treasury Secretary’s job is. It is not to outwit the markets. Being boringly predictable and ideally mostly neutral would be closer to the mark.  And I don’t assume I am saying anything interesting in pointing that out. It is just a reminder to stay sober.  But this focus on who markets will like reinforces the point that Jeremy Siegel made about how Trump is the most “pro-stock-market” president in American history. That seems right, if we take it to mean that Trump wants to be measured by how he affects the stock market – or for now at least he thinks he does.  And this choice of Bessent, as well as the spin around it, reinforces the point. 


Trump’s agenda is not entirely market friendly. Some aspects are positive and some are negative, as is well known.  But choosing Bessent suggests higher odds of Trump pushing harder on the aspects of his policy that are positive for the market.  Whether Bessent is a great market strategist is largely beside the point.  


Secondly, and on that issue of the trade war, I think I may be picking up in commentary from Bessent’s fans that the purpose of the Trump tariffs may be creeping in a favorable direction.  The tariffs were initially proposed to the unwitting electorate as a means of having foreigners pay for the operations of the US government, just as Mexico paid for The Wall.  But the problem with tariffs is that they land on domestic consumers and therefore stoke inflation, probably meaningfully if what Trump has proposed were to be implemented.  And that would provoke the Fed, which would have to guide aggregate demand growth lower and accept a renewed rise of the medium-term recession risk to reverse the inflation impetus. This is not the main problem for the country with tariffs, especially when accounted over a longer-term horizon.  But it is probably what would most concentrate minds in markets. So, if that could be avoided, it would probably be bullish – relative to the alternative.


What I think I hear being proposed now is the idea of using the threat of tariffs to force trading partners to conform with the Administration’s wishes somehow, perhaps by buying American exports or taking some other steps presumably designed to reduce the US trade deficit.  Such efforts are unlikely to work at reducing the trade deficit. Rather, they will introduce opportunities for more corruption through self-dealing, weaken America’s reputation as a reliable trading partner, and generate minor welfare losses in the US by directing American resources into the production of the wrong stuff. 


But from a market perspective, this is probably all small beer, because whatever damage is associated with this will be limited and will show up only over the longer haul. And in the short run, it would be more than offset by other aspects of the Trump agenda that markets are likely to approve, such as lower corporate tax rates, financial market and anti-trust deregulation, and an associated likely rise of market power and profit margins.


Bessent is also known as a fiscal hawk. The idea that the hawks have been “right” over the past decade or so strikes me as not being burdened with much evidence.  But the US probably now has almost enough public debt, so slowing or at least not accelerating its rate of ascent relative to GDP would probably be a win.  Whether Bessent will have much influence there remains to be seen. Historically, Trump has had more influence on his cabinet than it has on him. But it would probably be best if future policy change did not steepen the path of the debt/GDP ratio. And on this issue, Bessent probably is at worst not a negative, and he might be a positive, through either his influence or what he signals about Trump’s own priorities.

One final point that goes in the same direction. The utterly clueless cheerleading from the MSM around all this stuff is irksome to a fellow with my perspective. But it is probably symptomatic of a point that is constructive in the short run. Trump’s cray cray is being normalized by the culture. This will probably further encourage markets to retain their focus on immediately tangible effects, like profits or deregulation, and not to obsess as I do about abstractions like rule of law or longer-term worries like competence to deal with an actual macro shock.  Trump is getting the benefit of the doubt, until something actually goes wrong.

An example of the cluelessness
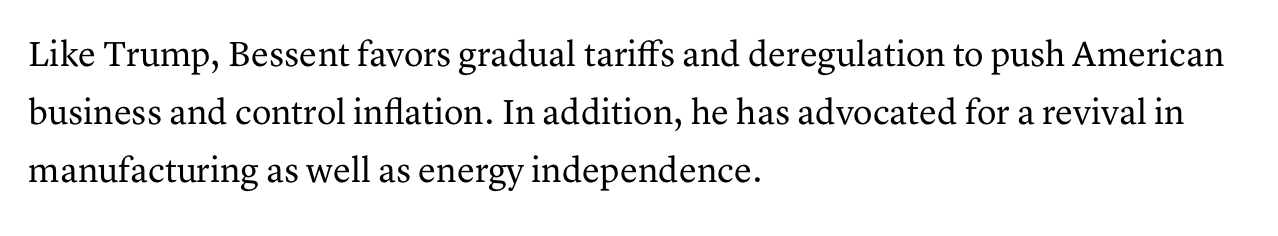

Source: CNBC, obviously

Trump wants just gradual tariffs to reduce inflation. And Bessent agrees.  This is from the guy whose beat is to understand this stuff. Brilliant.

None of this is resolved, and we will have to keep updating our sense of politics and policies as the news comes in.  But at the margin, Bessent seems ok, IMHO.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.