Back Economics

Marginal wage growth has indeed decelerated

Published on March 21, 2024

∙ Download the PDF Report

By

Gerard MacDonell

Pardon the pun. But a client pointed out to me that there is a disconnect between the trend in Indeed’s marginal wage growth tracker and the apparent rate of inflation in Average Hourly Earnings (AHE).   He is right about that, and I think the issue he points out is worth considering.

Let’s start with what the raw data show, as depicted in the chart immediately below.  It compares the 12-month change in AHE controlled for sector and rank mix shift in the usual way with Indeed’s wage tracker. As the analysts at Indeed point out themselves, their wage tracker is developed in a way that is analogous with the Atlanta Fed’s wage tracker in the sense that they survey the 12-month rates of individuals (in this case individual postings) and attempt to weight the results of that survey to correspond with the relevant economics (in this case the sector distribution of job classifications throughout the economy). 

The key point is that Indeed measures the rate of growth of marginal wages, which in principle might lead the average wages picked up by AHE. And speaking of analogies, this makes it analogous with how marginal rents might lead average rents.  (And incidentally, Powell yesterday expressed high confidence that average rent growth will slow because the marginal does in fact lead.)  So, taken in isolation, the steep deceleration of the Indeed tracker shown below should incline us to expect some further moderation of wage growth.  We know it does not itself point to acceleration. 

 Marginal may lead the way, in labor markets as in housing

A graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of

Description automatically generated
Source: Indeed, Federal Reserve Bank of St. Louis (FRED), FH calculations
All data are actual to February.

The question is how strong this signal is.  And that is a tough one because we do not have a long run of the Indeed data.  Moreover, it is the cumulative gap between marginal and average wages that should drive the acceleration or deceleration of average wage growth, picked up by AHE. And because the Indeed wage tracker has dropped below the rate of change of AHE, we know that the gap must be narrowing now. But from where? And where?

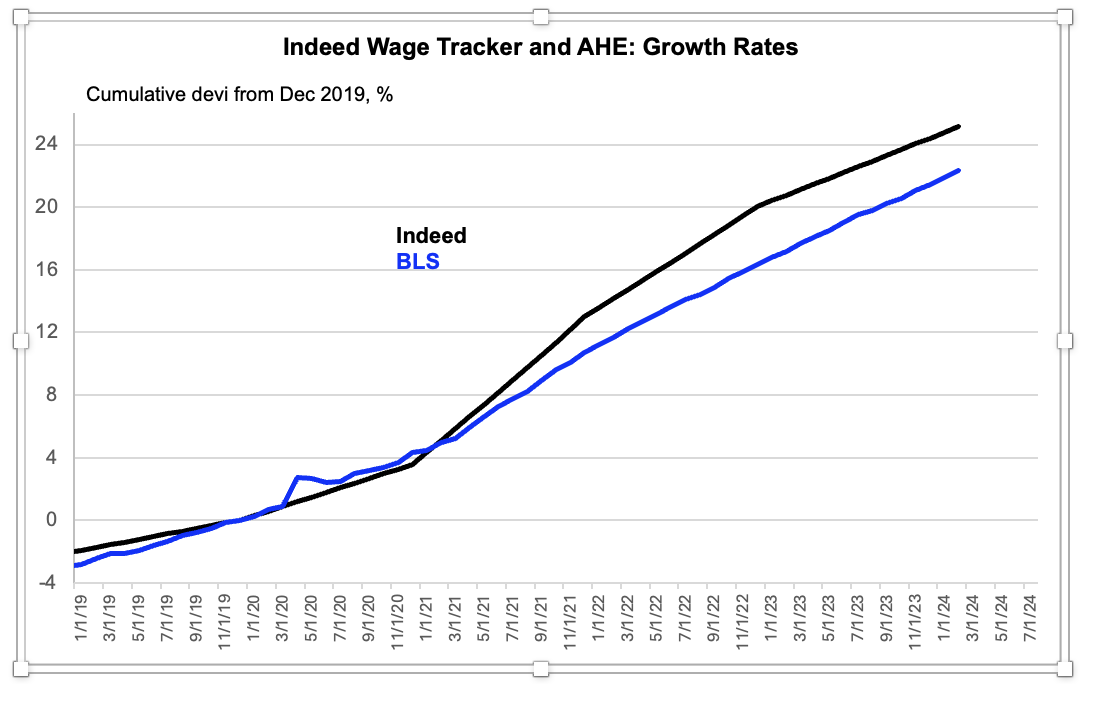
The lower panel of the chart above shows the estimated cumulative gap since pre-Covid separating the level of the Indeed wage tracker with AHE. I had to do some mental gymnastics to convert the surveyed growth rate within the wage tracker to level terms.  But unlike with the marginal wage data in the Atlanta Fed wage tracker, the change metric in the Indeed series is commensurate with a level.  And I made the conversion in the most conventional way, although there is some risk of imprecision there.  (The chart at the bottom of this note shows my proxy of the level of Indeed and then the level of AHE, the latter of which is readily available from my regular data tracking.)

We see two things from this analysis. First, the cumulative gap has narrowed from a peak of 3 1/4% to about 2 1/4%.  In principle, this should mean that the gravity tugging on the rate of change of AHE growth is less upward.  So, if this were a reliable leading indicator, we might expect AHE growth to slow. And my guess is that there is something to that.

But second, there is little evidence that the gap actually leads.  Both the gap and the pace of Indeed’s wage tracker peaked well before the peak of AHE, although all have been slowing recently.  One might say the gap leads, but in principle it ought not.  So, I cannot put a lot of weight on this indicator, although I concede it is probably picking up something relevant. Comments are most welcome. 

The level metrics used to calculate the cumulative gap above
A graph showing a line graph

Description automatically generated with medium confidence
Source: Indeed, Federal Reserve Bank of St. Louis (FRED), FH calculations
All data are actual to February.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.