Stronger than expected CPI and PPI readings last week led to increased policy uncertainty. The S&P dropped on the data and risk-off internals rallied, reversing some of the risk-on gains from the first week of March. Value has been the leading factor for March though, adding to the month over month factor reversal.
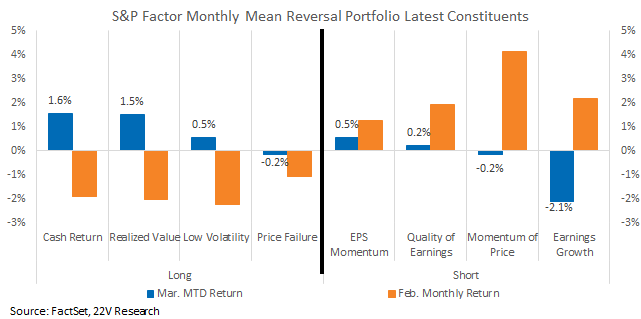
The long side of the factor reversal portfolio increased due to Value and Low Volatility returns improving. On the short side, Earnings Growth has underperformed, reversing sharply from February. The biggest story is the weakening of Momentum. High price momentum names are not underperforming significantly, but returns to the factor have reversed from it rapid gain in Feb. As we discussed (HERE), Momentum headwinds have increased, making some reversal more likely. Over the past week Value continued to gain even amid the risk-off general rotation.
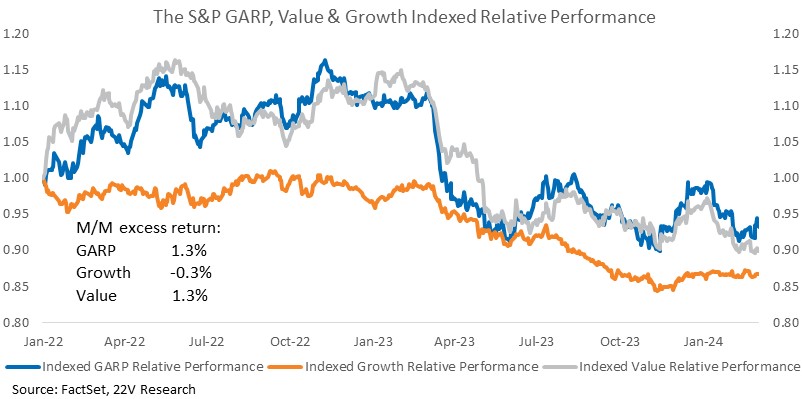
GARP overall has rebounded since February and remains our preferred screening approach while the inflation/growth outlooks are uncertain. Value has been the incremental support for GARP during the recent rebound basket and the portfolio rebound sharply since late February. We continue to favor GARP names expecting Value names to gain to catch up with its return divergence with yield moves.
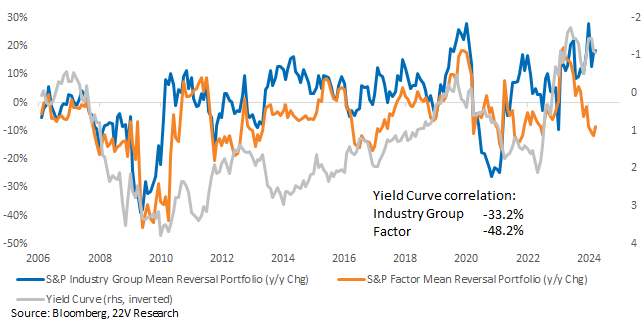
Interestingly, though indexed factor and industry group mean reversal portfolios trend to diverge, their monthly returns move together with correlation of ~58%. Applying portfolio returns as a proxy for mean reversal, the yield curve has a more consistent negative correlation with both industry and factor mean reversal portfolios – a steepening curve encourages trends. Easing of financial conditions tends to support reversal. If the FOMC does not surprise this week, a steeper curve and stable FCI should be the base case assumption, favoring the current Value trend.
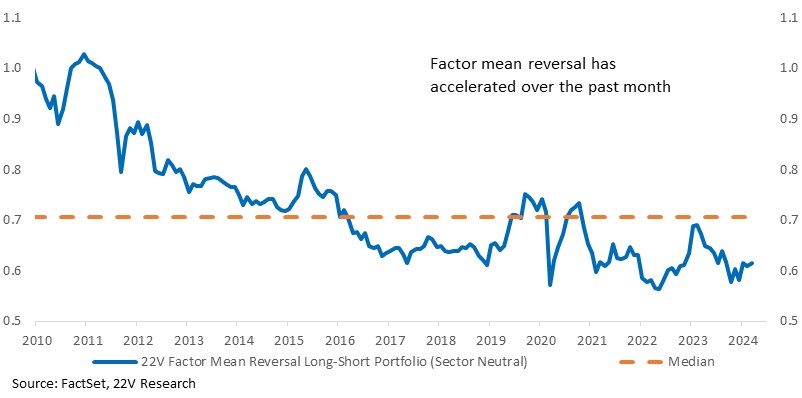
Another Round of Increased Mean Reversal: Stronger than expected CPI and PPI readings last week led to increased policy uncertainty. The S&P dropped on the data and risk-off internals rallied, reversing some of the risk-on gains from the first week of March. Value has been the leading factor for March though, adding to the month over month factor reversal. Our indexed factor mean reversal portfolio (long the worst 4 and short the best 4 factors from the prior month) is climbing again this month.
The long side of the factor reversal portfolio increased due to Value and Low Volatility returns improving. On the short side, Earnings Growth has underperformed, reversing sharply from February. The biggest story is the weakening of Momentum. High price momentum names are not underperforming significantly, but returns to the factor have reversed from it rapid gain in Feb. As we discussed (HERE), Momentum headwinds have increased, making some reversal more likely. Over the past week Value continued to gain even amid the risk-off general rotation.

GARP overall has rebounded since February and remains our preferred screening approach while the inflation/growth outlooks are uncertain. Value has been the incremental support for GARP during the recent rebound basket and the portfolio rebound sharply since late February. We continue to favor GARP names expecting Value names to gain to catch up with its return divergence with yield moves.
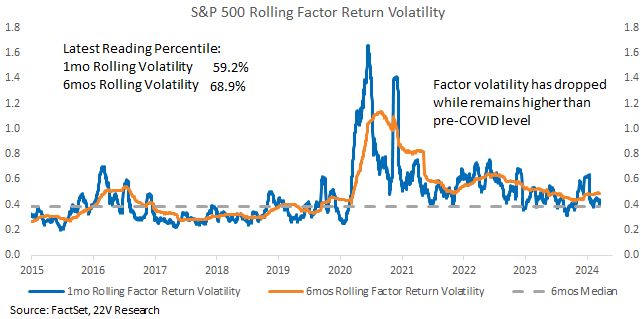
Longer-term, factor mean reversal has NOT been an effective strategy. Its returns are roughly flat over the post-COVID period. That is consistent with higher factor return volatility. Both short-term and long-term factor volatility have above pre-COVID levels and the current reading remains above its median as well. Both the factor portfolio returns and volatility suggest increasing rotations within factors post-COVID.
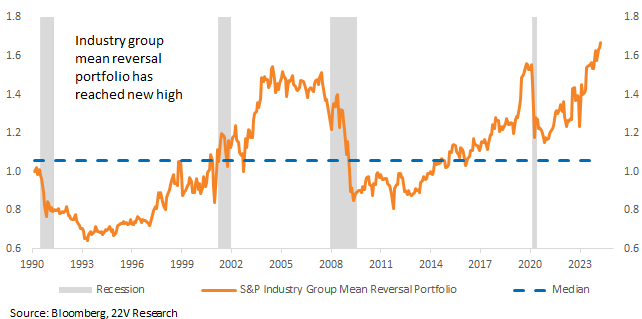
Mean reversal at the industry group level has been VERY strong. The industry group mean reversal portfolio (long the worst quartile industry group and short the best quartile industry group prior month) gained 1.5% in March. Historically, industry mean reversal is a more effective strategy, gaining in most non-recessionary periods.
Interestingly, though indexed factor and industry group mean reversal portfolios trend to diverge, their monthly returns move together with correlation of ~58%. Applying portfolio returns as a proxy for mean reversal, the yield curve has a more consistent negative correlation with both industry and factor mean reversal portfolios – a steepening curve encourages trends. Easing of financial conditions tends to support reversal. If the FOMC does not surprise this week, a steeper curve and stable FCI should be the base case assumption, favoring the current Value trend.
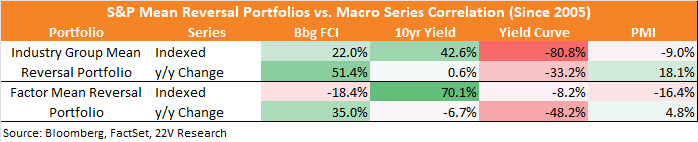
Though both the yield curve and mean reversal portfolio returns are volatile, their negative correlation suggests steeper curves should help lower market mean reversal, which is expected to happen as 10yr yield to climb on expanding economy and 3mo rate dropping.