

Former New York Fed chief Bill Dudley has an opinion piece on Bloomberg arguing that it will be important where the Fed decides to stop its quantitative tightening (QT) (article HERE). The piece argues that the main objective here is to avoid undershooting the level of reserves that would allow the Fed to hit its objectives for the money market: the target funds rate, target SOFR, etc. Dudley was ultimately and earlier effectively in charge of the trading desk at the New York Fed and so he is particularly well positioned to comment on these issues.
His views are consistent with my intuition which must come as a relief to him, although I suspect he overstates the drama around the need to be particularly careful sticking the landing for the balance sheet. That would be a PR issue, not an economic or even enduring financial issue. And it is not really like “landing an airplane without an altimeter,” unless we imagine an airport at which you are allowed to touch the runway five times and then pick which touch was the most comfortable. On the technical issues, he knows much more than I do.
What attracts me to his piece is his insistence that the effect of QT on the bond market will be trivial. So now they tell us! Guys, sorry to break it to you but your obsession for the past decade+ has been a distraction. Revenge is a dish best served cold, so I have come to the table 20 times with the same course, just to make sure, as you may have noticed. Anyhow, he has the right conclusion.
But the received reason why QT does not matter is the new source of hilarity. The reason is that QE and QT work “asymmetrically.”Ahhhhhhh. I see. What a beautiful immunizing stratagem. QE was important, but like God it works in mysterious ways! Here is Dudley with the new riff going around:
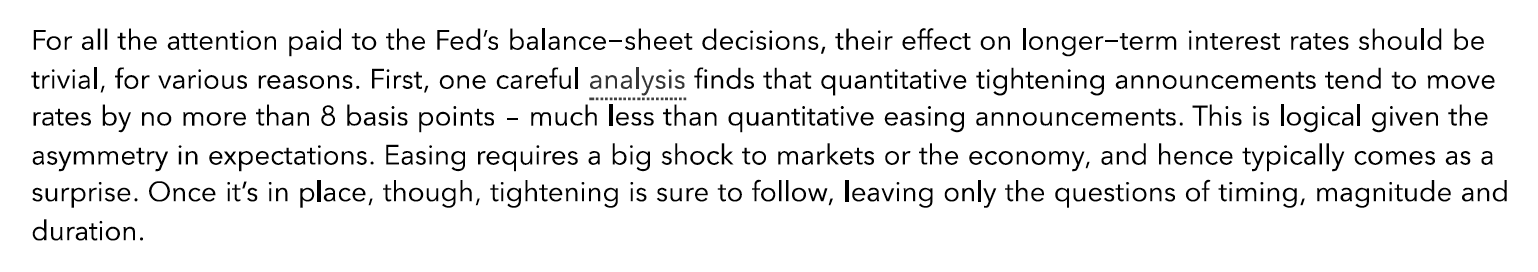
I will grant that the announcement effects this time around will be minimal, even if QE / QT were important to yields, which it is not. But the reason is that this stuff is so well telegraphed by Fed commentary, not that QT follows QE as reliably as night follows day. In fact, if that false claim were true, QE itself would be largely impotent, which it is, but just for a different reason.
The real debate here is not the announcement effects, but the enduring effects. And to see why this new claim is nonsense, consider a situation where the Fed surprise announces $3 trillion of QT. What would be the effect of this on yields? Short answer: not much, beyond the immediate announcement effect, as we have seen. But the argument presented above is that once the QE announcement is made, then QT is sure to follow with the timing being only a “trivial” consideration, as a simple matter of “logic.” Really? I thought the Fed leadership had repeatedly insisted that it was the expected path of the balance sheet over time, and not its spot value, that was important to the bond market. Nope, the new story is that it would not matter to markets if the $3 trillion were withdrawn tomorrow or in 10 years. So good.
Dudley concludes by pointing out that one value of shrinking the balance sheet now is that it creates “room” for renewed QE later. But when the Fed next does QE, it will be “trivial” how long the Fed suggests the injection might last. I will bet you 3 trillion dollars they would not characterize it that way in real time. If these folks (i.e., central bankers) did not have the ability to ruin your quarter, your year and your career, through other means, they would be laughed off Wall Street for this nonsense. And the media hang on every word, although it is not quite as cringe inducing as how they cover Jamie Dimon.
Anyhow, bottom line: QT won’t matter much for yields, because QE did not matter much for yields. We can keep it simple, without going into these gymnastics.
Totally off topic, but this was also very good:
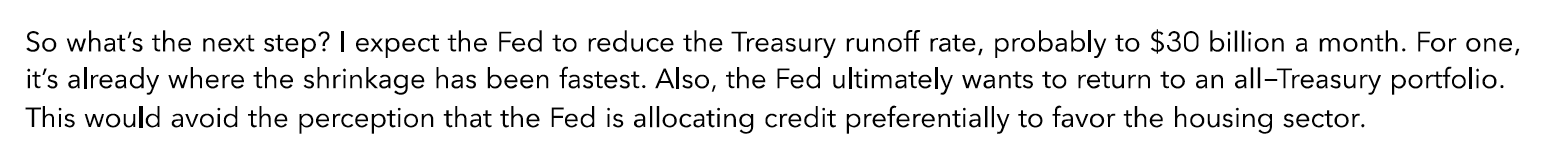
The Fed would not want to leave an impression that mortgage purchases were designed to help the mortgage market. And I think Dudley is smart. As I have said before, the balance sheet is intellectual kryptonite. Its main effect is to turn observers of it into fools.

