SUMMARY – Focusing on Some Core Views: Global central bankers reminded the world last week that fighting inflation remains their focus. Investors internalized that view over the past week+, pushing stocks modestly lower and causing a broad risk-off rotation. Cyclicals, risk-on factors, and the average stock all lost ground last week (after an unusually strong 1.5-month run higher). Deep Cyclicals and risk-on factors are reflecting that a weak China and more rate hikes being priced (from here) are a bad combo and lead to a deeper yield curve inversion. Still, the selloff was orderly with the VIX still below 15. Non-equity action was less clearly negative, and the GS financial conditions index was only modestly tighter.
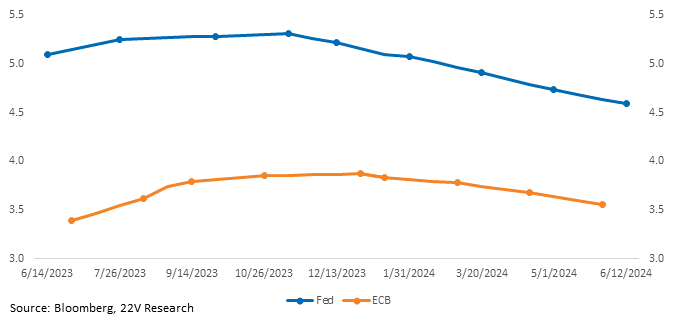
Powell and Lagarde both speak in Portugal this week, but with both Fed and ECB futures pointing to higher rates for longer (the Fed Funds rate is expected to be 5.25% through year-end), don’t expect to get much new hawkish info. Especially from Powell. Payrolls are next week after all. Assuming geopolitical risk doesn’t spiral, expect financial conditions to remain range bound. The worst of the hawkish policy/China trade is likely behind us for now.
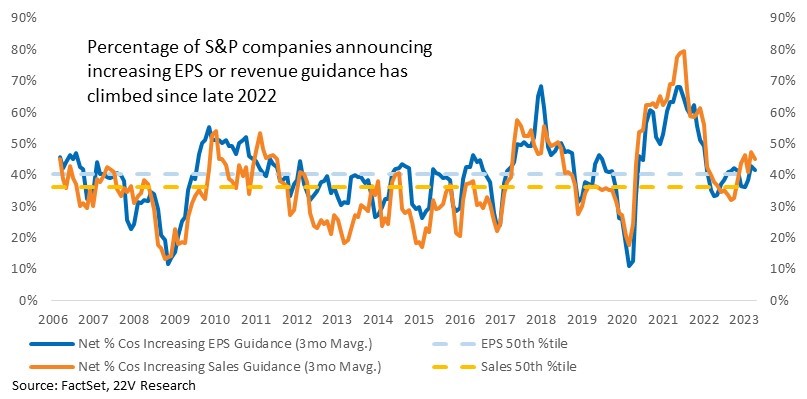
Investors in our survey (HERE) who do not expect a recession put 2023 S&P EPS at $220. For those expecting a recession, estimates drop to $210. 2024 estimates are wider with non-recession at $245 and the recession number $220. With 81% of investors thinking a recession will happen, the base case for earnings appears to be $210 and $220. Consensus put 2Q EPS down -8.4% (to $53) and 2023 earnings at $217. That creates a low bar for earnings heading into a season where earnings sentiment and guidance are firming. A strong earnings reporting season would help lift NTM earnings expectations, which are already up ~3% from their low. That would take some pressure off PEs to maintain equity pricing and supporting risk assets/factors. Risk-on factors underperformed last week, but we remain long Destocking losers, Deep cyclicals (ex-Energy) over Defensives and Early Cyclicals, the average stock over mega caps, emerging markets, and risk-on factors into earnings season.
Medium-term, a higher range for equities, and a persistent risk-on rotation require reduced hard landing odds. Despite a rapid pace of rate hikes, a 5% fed funds rate, and expectations of another hike the economy is ok. All that means there is a greater chance that R* (the equilibrium real fed funds rate) is higher and the economy can “live” with 5% fed funds. At least for now. That idea helps explain why risk-on and Cyclicals have outperformed MTD despite their stumble last week. If inflation moves slowly lower (can wages decline WITHOUT a major labor market disruption? This is the million dollar question), Powell can probe for a soft landing. Which he seems willing to do (see below). Investors understand that Powell is willing to probe for a soft landing, which is why a significant shift higher in the expected fed funds rate, which would happen if wages stay too high, and subsequent FCI tightening, is the biggest risk.
FYI: The stability of macro forces over the past few months has allowed equity vol to decline, but market trends remain tied to those macro forces. Macro influence should trend lower OVER TIME, but market calls are hard to make until the outlook for a soft or hard landing becomes MUCH clearer. Short-term narrative shifts will continue to exert a large influence. We wonder if the latest hawkish narrative shift is largely priced in given the move in futures markets.

Full report below…
MARKET VIEWS: Cyclicals, risk-on factors, and the average stock all lost ground last week (after an unusually strong month and half run higher). Still, the selloff was orderly with the VIX still below 15. Non-equity action was less clearly negative as well and the GS financial conditions index was modestly tighter. Short-term narrative shifts will continue to have a large influence. We wonder if the latest hawkish narrative shift is largely priced in given the move in futures markets. Rates are expected to stay higher for longer in both Europe and the US.
In a few weeks, 2Q reporting season will get underway. Investors who do not expect a recession put 2023 S&P EPS at $220, and for those expecting a recession, the estimate drops to $210. 2024 estimates are wider with non-recession at $245 and the recession number at $220. With 81% of investors thinking a recession will happen, the base case for earnings appears to be $210 and $220 (more HERE). Consensus put 2Q EPS down -8.4% (to $53) and 2023 earnings at $217. That implies downside risk for the market, but not a sharp selloff. It also creates a low bar for earnings heading into a season where sentiment and guidance are firming.
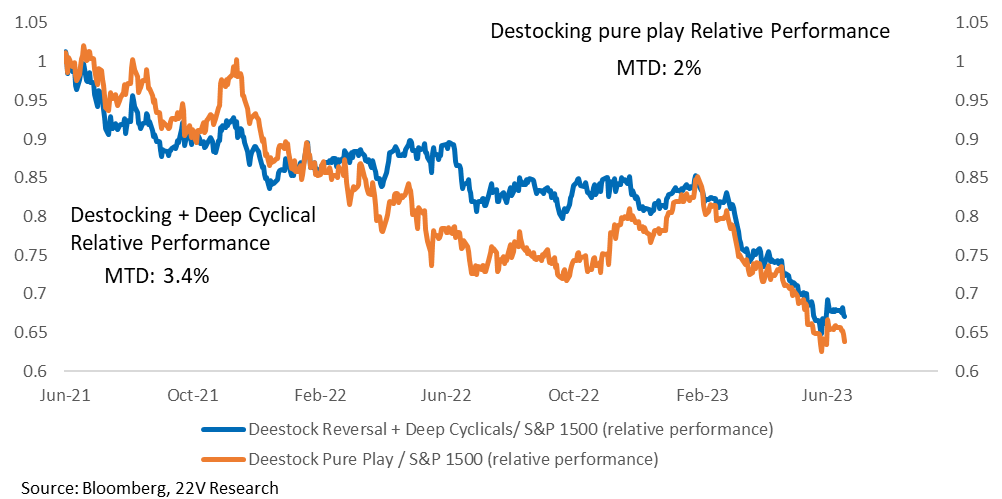
As we discussed over the past few weeks, we remain focused on themes including a rebound in Destocking losers, Deep cyclicals (ex-Energy) over Defensives and Early Cyclicals, the average stock over mega caps, emerging markets, and risk-on factors. Both the destocking losers and destocking losers + deep Cyclical baskets are up MTD but had a bad week.
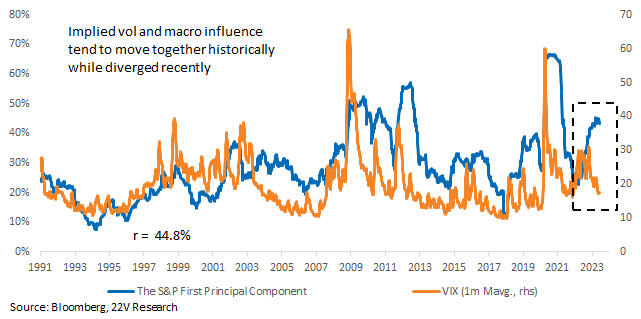
Macro influence on S&P remains high (85th %tile). The divergence between macro influence and market vol has reached extreme levels. Our read of this is that the stability of macro forces over the past few months has allowed equity vol to decline, but market trends remain tied to those macro forces. Macro influence should trend lower OVER TIME, but market calls are hard to make until the outlook for a soft or hard landing becomes MUCH clearer. Until then, data surprises and narrative shifts will exert outsized influence over markets. Given the ongoing transition period, that means more mean reversion moves.
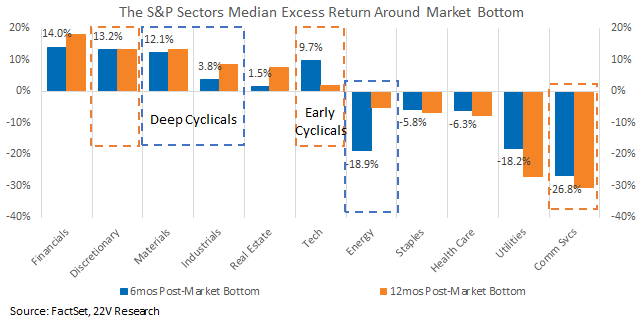
If a soft landing is coming, the market low for this cycle was likely Late-October 2022. One year from the market low, Cyclicals generally outperform Defensives overall, with Deep Cyclicals tending to gain in the latter half of the year. Deep cyclicals should be in favor now if a soft landing is going to happen. Again, conviction on a soft landing is needed to green light a longer-term long Deep Cyclicals call.
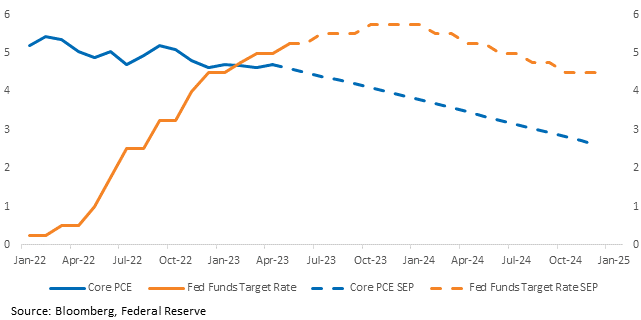
Powell Will Probe for A Soft Landing If He Can: So, it is less obvious that the Fed needs to force a recession to cool inflation. From Powell about the DOTS “what they’re showing is that as inflation comes down in the forecast, if you don’t lower interest rates then real rates are going up, right. So just to maintain a real rate, the nominal rate at that point two years out should come down just to maintain real rates.” That hints at allowing higher than 2% inflation for some time, increasing the odds of a soft landing (no or mild recession) outcome.
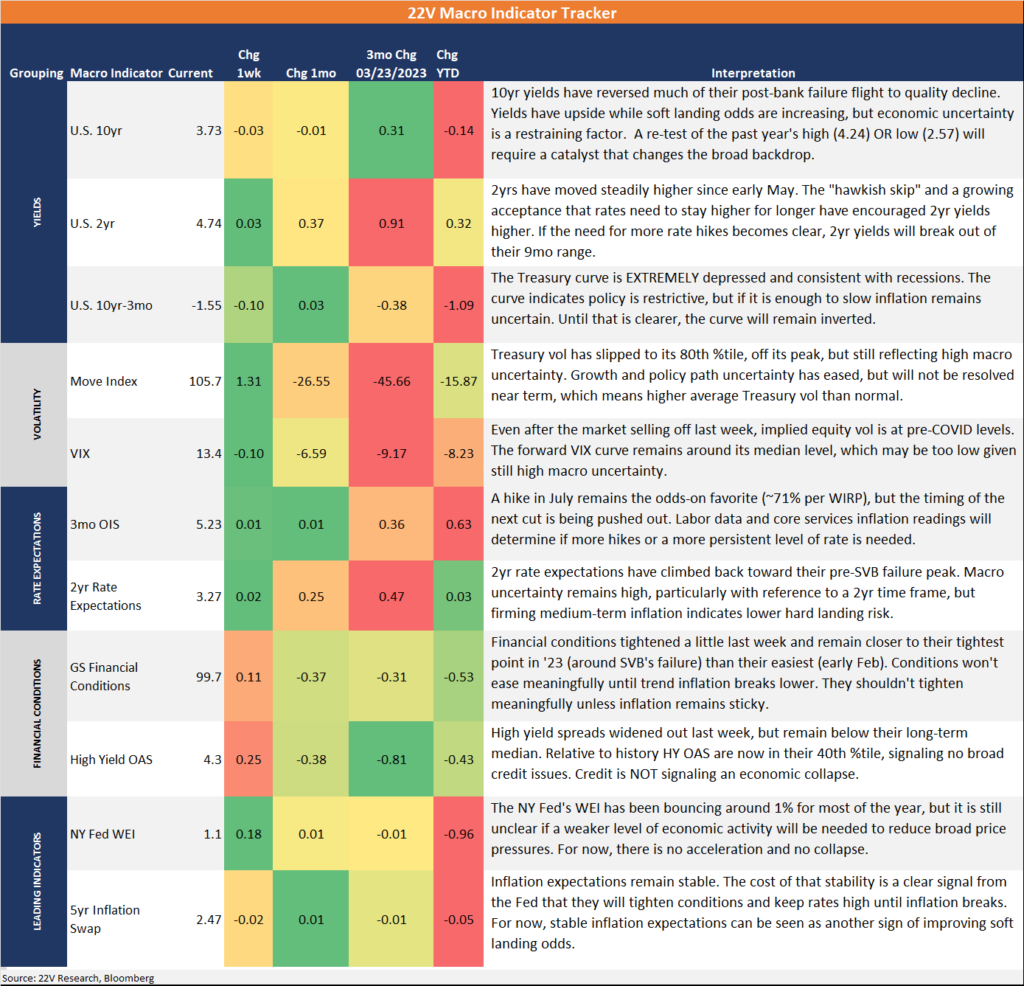
Macro Tracker: Global central bankers, following the signal from the FOMC, reminded the world last week that fighting inflation remains their focus. Urgency in the fight against inflation appears to still be a larger concern, particularly outside the U.S., than the risk of a recession. Investors internalized that view over the past week+, pushing stocks modestly lower and causing a broad risk-off rotation. Cyclicals, risk-on factors, and the average stock all lost ground. Still, the selloff was orderly with the VIX still below 15. Non-equity action was less clearly negative as well. High yield spreads widened, but only modestly, and remain below their median level. The Treasury curve inverted more but remains off its low, and it has been a very poor timing tool, particularly in the latest period. Market gains from May have been a result of multiple expansion as hard-landing fears eased. Data in the U.S. remains firm and earnings outlooks have been improving since 4Q. Offsetting those impulses are weakness in Europe/China, an acknowledgment that global central bankers are still willing to accept rising recession risk to offset sticky high inflation. A strong earnings reporting season would help lift NTM earnings expectations, taking some pressure off PEs to maintain equity pricing and supporting risk assets/factors. Medium term though, a higher range on equities and a persistent risk-on rotation require reduced hard landing odds.