Back Portfolio Strategy

Expect the Risk-on Rotation to Continue Near-term, not Long-Term, and Headwinds to Tech

Published on May 22, 2023

∙ Download the PDF Report

By

Dennis DeBusschere

Brian Herlihy

Kevin Brocks

Sophia Wang

SUMMARY: 1Q earnings were better than feared. The S&P has experienced a 9% increase this year, with cyclicals leading defensives and early cyclicals leading deeps. Risk-on factors have been outperforming risk-off factors recently. Additionally, 10-year yields have risen while credit spreads have tightened. That’s the good news.

The not-so-good news, it is important to be cautious when extrapolating macro trends due to high economic volatility and the Federal Reserve’s focus on fighting inflation. Mean reversion remains the dominant theme, and we are maintaining our range bound market call between 3800 and 4200. As the quant team discussed this morning (HERE), most factors have reversed relative to their Mar/Apr and early-May trends. Expect the rotation into risk-on factors to continue near-term, assuming a debt default is avoided, but don’t expect the rotation to be durable.

TECH RISK: Tech has been the best-performing S&P sector, driven by mega-cap names. Tech companies are more exposed to momentum of price and quality of earnings factors, while being less exposed to risk-off factors and realized value. Those exposures have been a support since the bank failure. This current round of mean reversion will be a headwind to Tech broadly. Especially if 10yr yields keep marching higher….

CREDIT TRENDS FINE: Credit availability has decreased since SVB, and financial conditions related to banking are tighter compared to two months ago. However, there are no signs of a widespread liquidity crisis. You can see this in C&I loans, which have fallen but not cratered. And companies still have positive financing sentiment, including debt financing and cash availability. This suggests that the ongoing mean reversion, which favors risk-on investments and poses a challenge for tech, is likely to continue in the near term as investors re-adjust their recession expectations. Our survey work HERE indicates that is happening now.

A picture containing text, screenshot, font, plot

Description automatically generated

More details in the full report below…

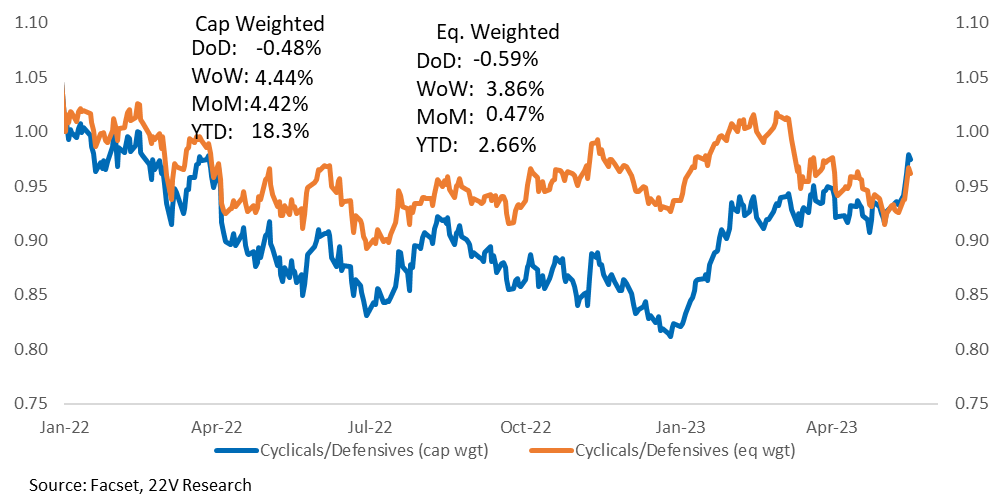
MARKET VIEWS: 1Q earnings reporting is about complete, and companies logged 1) higher than normal beat rates (top and bottom line) and 2) a surprise expansion of margins. The S&P is up 9% this year, cyclicals are leading defensives, Early Cyclicals are leading Deep Cyclicals, and as of last week, risk-on factors are leading risk-off. Recently, 10yr yields have moved higher and credit spreads tighter. Those are the good bits.
A picture containing text, screenshot, font, plot

Description automatically generated

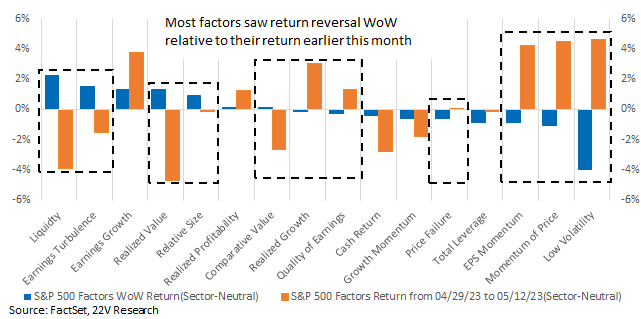
Now the worse part. It is still dangerous to extrapolate macro trends when economic vol is exceptionally high and the Fed is still in inflation-fighting mode. Mean reversal remains the overarching theme, and stocks are range bound (3800-4200). As the quant team discussed this morning (HERE), most factors have reversed relative to their Mar/Apr and early-May trends. Expect the rotation into risk-on factors to continue near-term, assuming a debt default is avoided, but don’t expect the rotation to be durable.
A picture containing text, diagram, screenshot, line

Description automatically generated

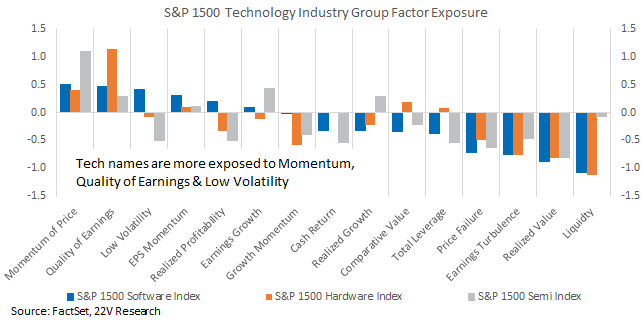
TECH RISK: Technology has been the best performing S&P sector this year, led by mega cap names. Breaking down into factors, Tech names are more exposed to Momentum of Price and Quality of Earnings while less exposed to risk-off factors and Realized Value. Those exposures have been a support since the bank failure. This current round of mean reversion will be a headwind to Tech broadly. Especially if 10yr yields keep marching higher….
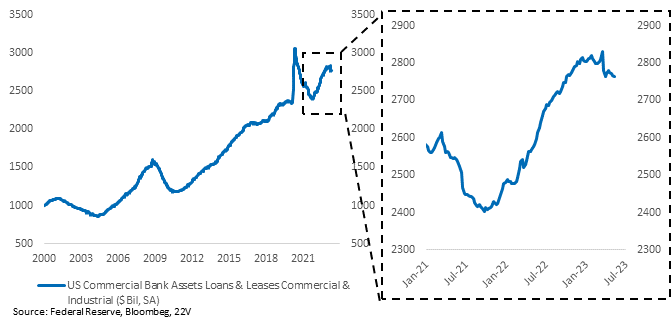
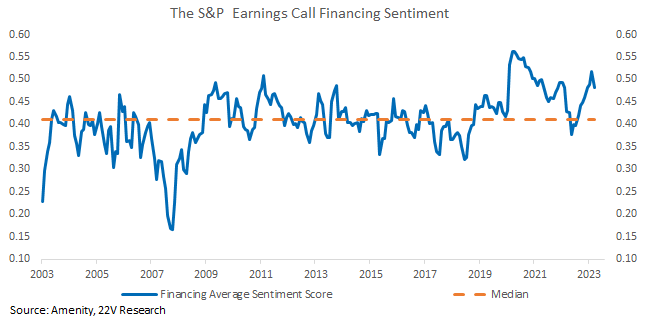
CREDIT TRENDS FINE: Company sentiment readings, measured using Amenity’s natural language processing tool, showed credit conditions tightened AT THE MARGIN but did not collapse. Since SVB’s failure, credit availability has decreased, and banking related financial conditions are tighter than two months ago. However, a rapid credit freeze has not occurred and there are no signs of broad liquidity issues. You can see this in C&I loans, which have fallen but not cratered.
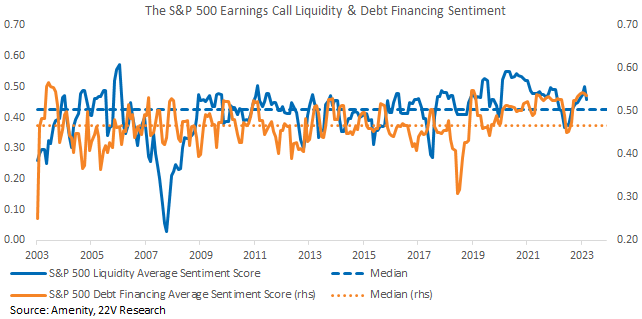
Companies still have positive financing sentiment, which includes sentiment about debt financing and the availability of cash. All this implies the current round of mean reversion, which is risk-on and a headwind to Tech, is set to continue near-term as investors re-adjust recession expectations. Our survey work HERE indicates that is happening now.
A picture containing text, screenshot, font, plot

Description automatically generated

Here is debt financing sentiment and liquidity sentiment broken out. Both are above their medians.

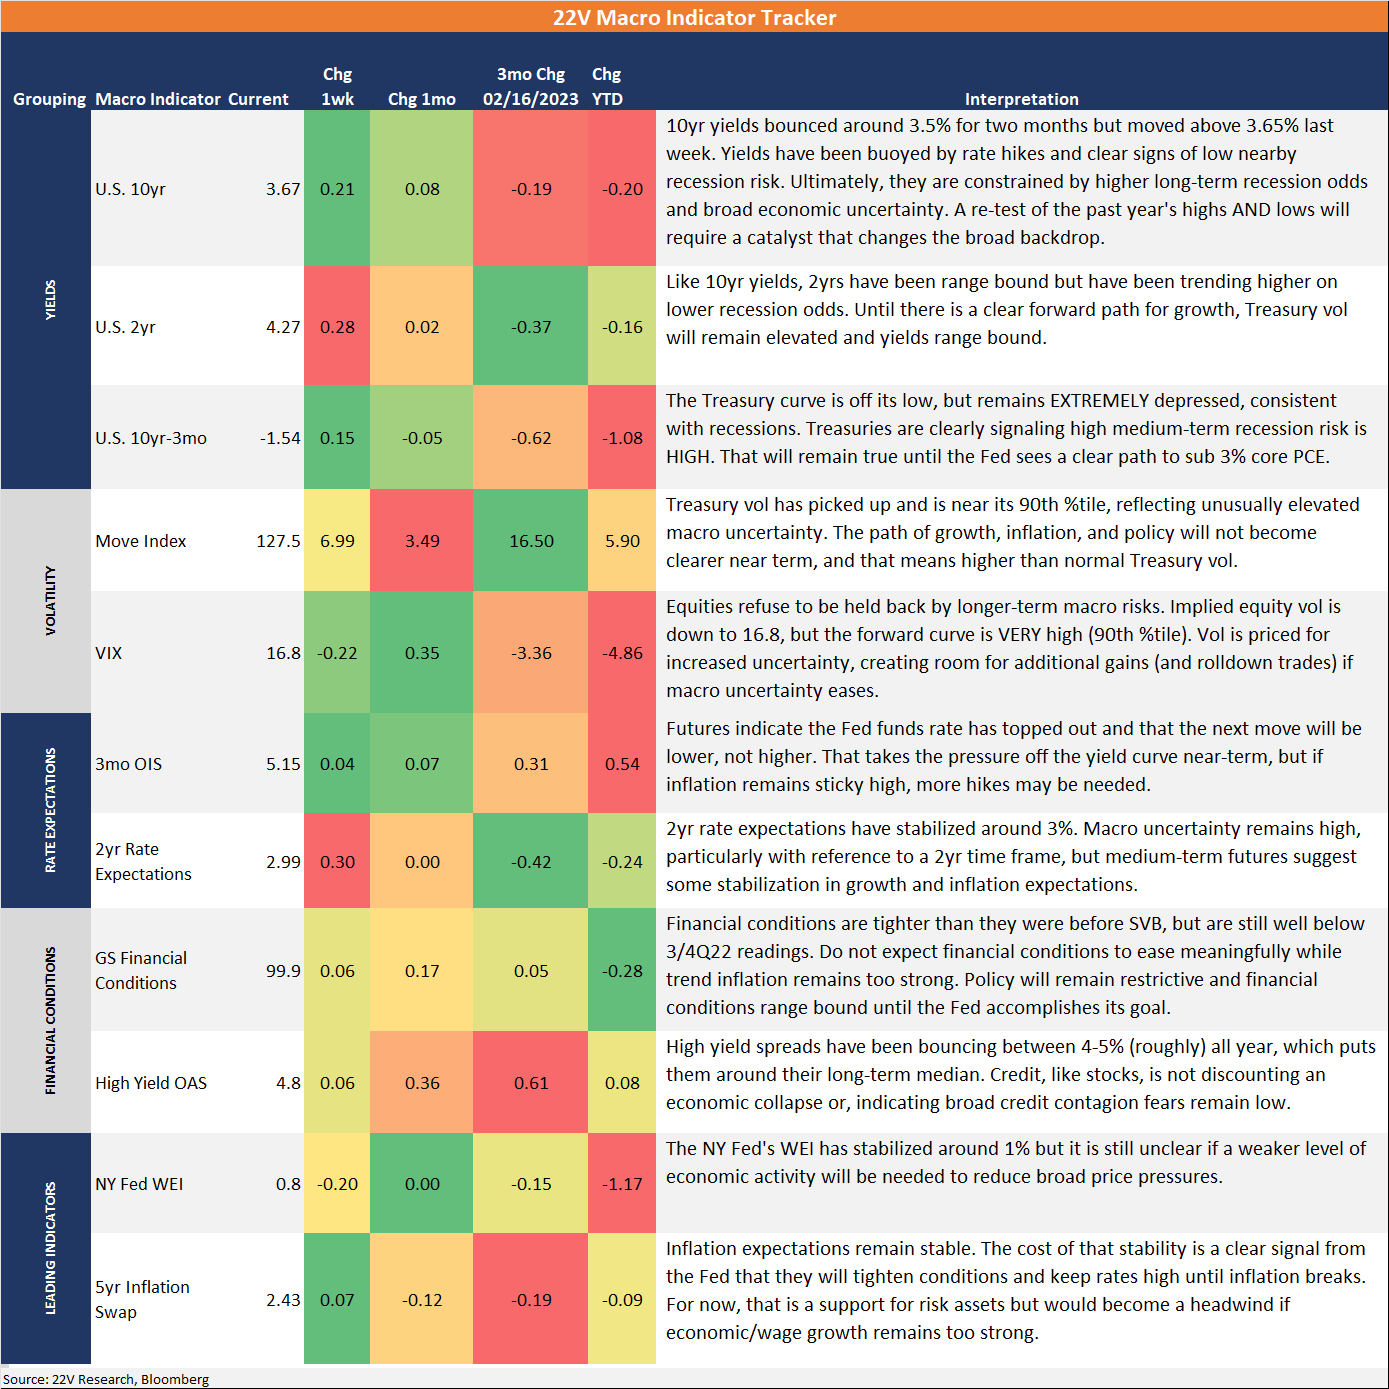
Macro Tracker: Rolling issues stemming from the Fed’s aggressive rate hikes continue to crop up, but they have not snowballed in a way to create deep recession risk. As a result, investors have lowered their nearby recession odds and increased their EPS estimates for the year (HERE). Credit spreads remain range bound, the VIX is stable below 17, 1Q earnings were better than expected, and market internals took a big move in the risk-on direction last week. The skew on stocks has improved some, but a meaningful break higher requires more clarity on looming economic issues. Labor markets remain too tight, inflation too high, so Fed-induced recession risk odds remain elevated.  
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.