Back China Strategy

China: Despite strong credit data, low inflation points to subdued demand

Published on April 11, 2023

∙ Download the PDF Report

By

Michael Hirson

Data releases on Tuesday present a mixed picture of the outlook for China’s recovery. Credit data was very strong and beat expectations, including long-awaited signs of an initial recovery in mortgages. But inflation readings surprised to the downside, suggesting underlying demand is still somewhat weak.

What’s the takeaway? Policymakers are keen to support the recovery by keeping credit conditions loose. But the impact on real activity will be limited in strength and duration unless it is accompanied by a rebound in underlying demand – particularly by households.

It remains early to conclude that broader demand is on a solid footing, given:

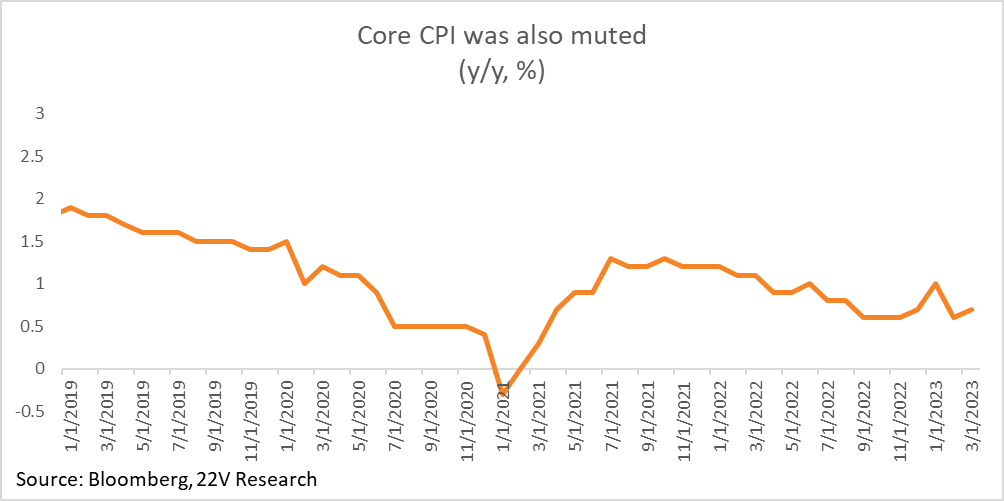
  • Weak underlying inflation, with core CPI edging up to 0.7% y/y, from 0.6% y/y in February.
  • Broader signs that while consumers are readily partaking in services (such as travel and entertainment), spending on goods remains subdued. Autos, for example, are in a brutal price war, with the price of gas-powered cars falling -4.5% y/y. As we have been emphasizing, healthy consumer spending will take time to develop, requiring a recovery in the labor market and household income given lack of direct support for consumption from the government.
  • Slowing exports, with new export orders in manufacturing slipping into contractionary territory in the March manufacturing PMI surveys (see our write-up HERE). China’s domestic demand needs to compensate for weak external demand this year, reversing the 2020-2022 trend in which strong export growth provided much-needed support during zero-Covid.
  • Restrained fiscal stimulus, given Beijing’s renewed focus on local government debt risks. Local government revenues are strained by weak land sales, which will be slow to turn around given that property developers will need to use sales proceeds to pay back maturing debt and complete stalled projects.

Chinese media had previously reported that PBOC gave window guidance to banks to slow the pace of lending in March after a blowout January and February. That clearly wasn’t the case, but there are limits to Beijing’s willingness to lean on banks to lend given a focus on containing long-term financial risks; the private sector will have to take over the baton from stimulus in H2 for the recovery to sustain momentum.

In sum, the overall data are still consistent with a rebound this year that is gradual and driven more by services than accelerating industrial activity. It will be important to look at March activity data and Q1 GDP, which come out together on 17 April, for a broader gauge of the health of private sector demand.

From a global perspective, muted CPI and PPI data suggest that China will not be exporting inflation to the rest of the world anytime soon.

A few more details of note:

Credit data:

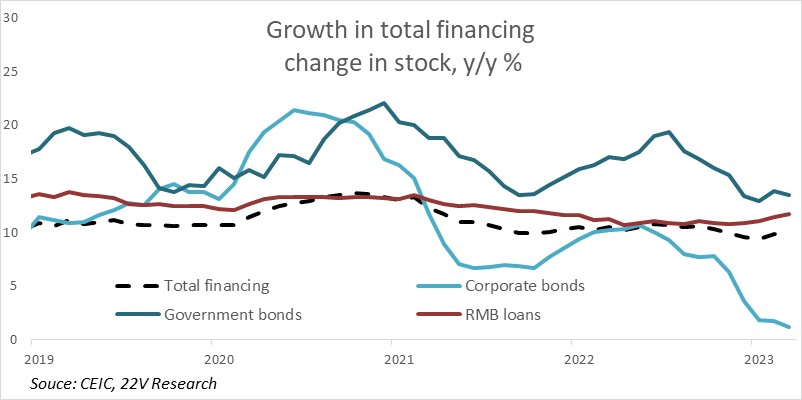
March is traditionally a strong month, with banks pushing out loans to meet their end-quarter quotas. But the scale of new loans (RMB 5.4 tn) was close to all-time monthly high and brings the three-month total to a record RMB 14.5 tn. Lending in March was strong both to corporates and households, with the latter particularly notable: new household loans were the strongest in two years.

Overall, bank lending was enough to offset a slowdown in government and corporate bond financing, with total social financing increasing by 10% y/y in March vs. 9.9% y/y in February.
Inflation:

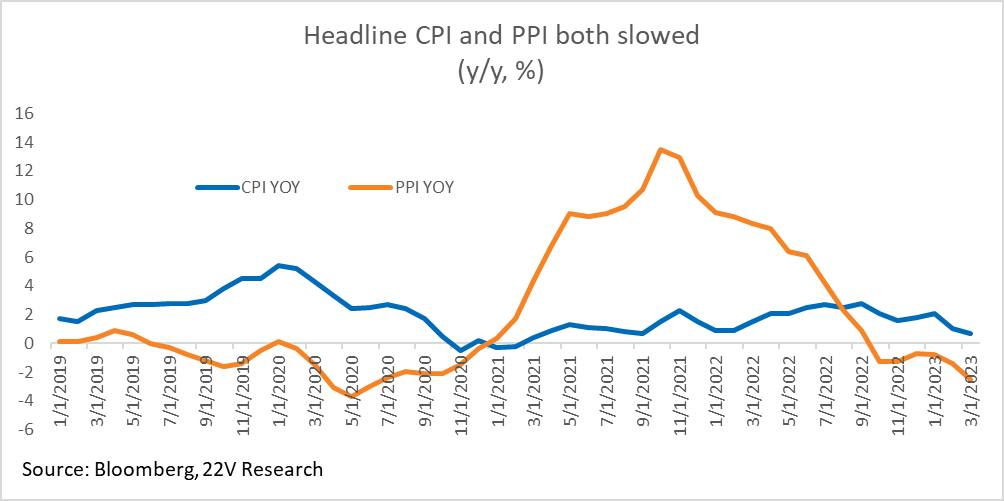
The slowdown in the headline CPI in March, 0.7% y/y vs. 1% y/y in February, was due in part to slowing food prices and falling energy prices. But the core CPI reading – essentially flat at 0.7 y/y – also shows relatively muted demand. Falling commodity prices were also a factor in PPI, which slowed from -1.4% y/y in February to -2.5% y/y in March, the lowest reading since late 2020.
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.