

SUMMARY
- The most likely risk to prevailing narratives on China this year is on the growth side: demand from China may not match up to high expectations, particularly when it comes to inputs into China’s investment and industry. The risk of China overheating this year is correspondingly low.
- Geopolitical risks are more moderate, but it will be important to watch US-China tensions and the run-up to Taiwan’s January 2024 presidential elections.
- While one shouldn’t overstate Xi Jinping’s newfound pragmatism, we see a relatively low probability that Beijing announces political or regulatory actions highly disruptive to private firms and the tech sector.

Expectations towards China this year have risen dramatically since the fall, evident in market prices (especially shares of Chinese e-commerce companies), 22V’s recent client survey (see link here) and our conversations with investors.
This is not without some grounding, given the rapid Covid pivot underway (however chaotic) and signs that Xi Jinping is looking to lower foreign policy tensions and boost the confidence of the private sector.
Still, it is worth probing – and several clients have asked – what could go wrong this year. Two broad areas of vulnerability for the market narrative on China are:
- Expectations that China’s reopening will buoy demand across a wide range of assets. This may be optimistic given signals of relatively restrained stimulus, headwinds to fixed investment, and a consumption rebound that could fade in H2. We are relatively cautious when it comes to the growth story, as our 2023 outlook laid out (see link here).
- A view that Xi Jinping has undergone a shift towards pragmatism. It is more accurate to say that Xi is prioritizing an economic recovery for now. His broader objectives are unchanged and some of these – an insistence on Party control, a growing focus on economic security, and an assertive foreign policy – create risks for investors, particularly if his priorities shift once the recovery is on solid footing. And it isn’t all about Xi: some risks this year, such as US policy towards China, are outside of Beijing’s practical control.
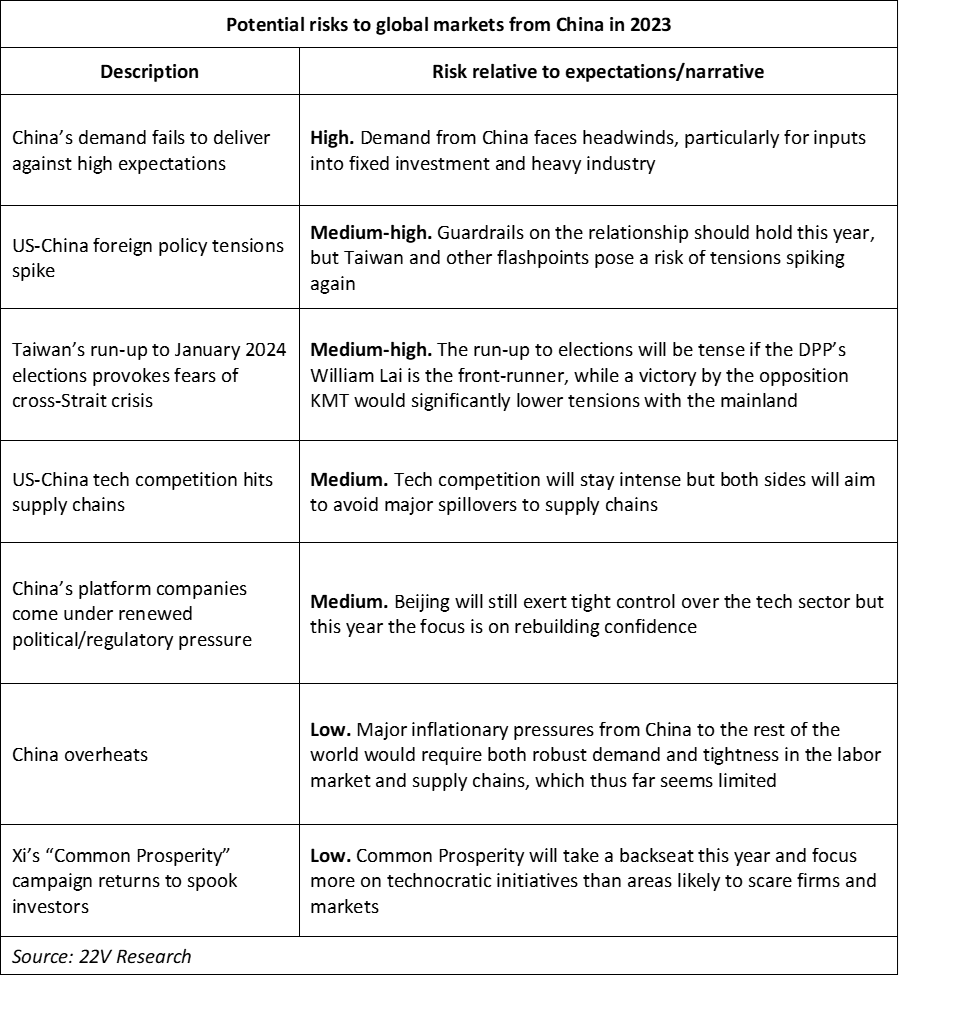
This note is not a bearish take on China but more in the spirit of a “pre-mortem”: imagine that China-related developments will at some point this year generate uncertainty and concern for global markets. What would the most likely culprits be? The discussion rates specific risks relative to expectations, which refers broadly to current narratives on China and is a subjective concept.
Economic Growth:
1. China’s recovery fails to carry global growth
Description: The easiest way that China could disappoint markets this year is simply by demand failing to deliver against high expectations. To be clear, GDP growth of around 5% – which is where the sell-side consensus is – should be achievable and the downside is limited. But anecdotally, many investors seem to be anticipating higher growth and/or broader growth than is likely to manifest. The potential causes for disappointment could include:
- Outsize expectations for the consumption boom. Our note last week covered overly high expectations around “excess saving” for Chinese households and what it means for “revenge spending” (see link here). We see room for disappointment in the strength of the consumption rebound in H2, particularly when it comes to spending on goods; there is a stronger case for spending on services, including travel.
- Limited new demand for industrial/investment inputs. While some observers believe Beijing will pull all levers to boost growth this year, our outlook noted that the authorities are banking on post-Covid reopening to do most of the work. The overall strength of new stimulus measures may be limited and local governments are adopting conversative growth targets. Support for property is scaling up but it aims at stabilizing the sector rather than a quick rebound in investment, which would be extremely difficult. In short, growth this year will be led by consumption and services, the areas repressed under zero-Covid, rather than investment and manufacturing, which had held up relatively well during the pandemic and face headwinds this year. (This dynamic is behind the recent trade idea from 22V’s portfolio strategy team for exposure that is long oil, which benefits from renewed travel, relative to iron ore).
- Reemergence of financial risks. Three years of pandemic spending and the property downturn have exacerbated long-brewing financial risks in China, particularly at the local level. Two risks that could hit the headlines are debt distress among local government financing vehicles (LGFVs) and weakness/failures among smaller regional banks. These are unlikely to raise systemic concerns this year, with the authorities moving proactively to avoid a hit to confidence. But managing LGFV risks will be another headwind for fiscal stimulus, including infrastructure investment, and a broader reminder to investors of China’s longer-term vulnerabilities.
- A second wave of Covid. China will likely experience a second Covid wave, which looking at the pattern in other countries would probably come in H2. That could be another headwind to H2 growth momentum, particularly for consumption.
- Climate risks. While hard to quantify, it is worth noting that extreme weather has been having a more noticeable impact on China’s economy in recent years, contributing to energy shortages and flooding last summer. This winter the problem is a cold spell in the north and high natural gas prices.
Risk relative to expectations: High. China’s growth will be much better than 2022 but may not provide the lift to the global economy that some expect, particularly in H2.
Signposts: The major near-term watchpoint is the National People’s Congress in March, where we expect a modest GDP growth target (such as “above 5%”) and no bombshell stimulus announcements; more ambitious targets/policies would indicate that Beijing is gunning for faster growth.
2. China overheats, creating problems for central banks
Description: The opposite scenario of China’s growth disappointing is a strong rebound leading to a major inflationary impulse for the rest of the world. The clearest case for China adding to global inflation is through a rise in oil/energy prices, given pent-up demand for domestic and international travel. But the prospect of broader inflationary pressures from China, exported abroad, seems less likely. It would require both very strong demand in China and supply side constraints such as a tight labor market. On the supply side, China’s unemployment rate remains above pre-pandemic levels, suggesting considerable slack, and supply chains had generally been running smoothly between Shanghai’s lockdown in the spring and the national Covid wave in December/January.
Risk relative to expectations: Low. China’s reopening is positive for oil, and there could be broader temporary inflationary pressures in Feb-April if demand recovers and hiring lags. But a sustained surge in industrial prices exported to the rest of the world looks unlikely. We agree with the client survey response (link here) that China’s reopening is unlikely to disrupt the path of the Fed.
Signposts: A higher-than-expected growth target and major stimulus at the NPC, as well as signs of labor market tightness as the recovery gets underway, would point to elevated inflation risks.
Geopolitics:
3. US-China “guardrails” come under strain
Description: The effort by President Joe Biden and General Secretary Xi Jinping since their November G-20 meeting in Bali to put a floor under the relationship faces challenges from domestic politics in both countries and the sheer number of areas in contention (see the discussion in our outlook, written with 22V’s Washington Policy team). The key potential triggers for volatility this year, in descending order of risk, are:
- Taiwan: By far the most serious flashpoint in the relationship. House Speaker Kevin McCarthy pledged last year to visit Taiwan if elected speaker and there were recent media reports of a planned visit this spring. China will respond with the same level of saber-rattling as during the Pelosi visit last August, which stopped short of a full-blown crisis but was a serious military escalation and established a higher baseline for China’s military activities in the Taiwan Strait. Beyond the tail risk of an accident (such as collision between militaries), a visit would make it more difficult for the two sides to resume dialogues on areas including the economic relationship and climate. Even if a visit does not occur, Congress will continue to press for other ways to show support to Taiwan and rankle Beijing.
- Russia/Ukraine: While not our basecase, there is a risk that Beijing provides support to Putin’s regime that triggers a sharp response from Washington, such as sanctions or export controls on Chinese entities, thus worsening tensions.
- Iran/North Korea sanctions: The US State Department’s special envoy for Iran, Rob Malley, said earlier this week that Washington will increase pressure on China over rising crude imports from Iran, though the US will likely be restrained when it comes to major sanctions on China given concerns that these could cause oil prices to spike. Washington and Beijing have each been largely ignoring North Korea despite a sharp increase in missile firings in 2022, but a major new provocation – such as resuming nuclear tests – will compel a tougher response by the US and its allies, including pressure on China to back UN sanctions against Pyongyang.
Risk relative to expectations: Medium-high. US-China guard rails are likely to hold this year, but Taiwan issues, in particular, run the risk of increasing tensions.
Signposts: Secretary of State Blinken’s visit to China, reportedly to take place around 5 February, will follow up on the Biden-Xi meeting in November and help gauge where both sides stand on key issues.
4. Run-up to Taiwan elections provokes fears of cross-Strait crisis
Description: Taiwan will hold presidential elections in January 2024. The opposition KMT party, more inclined to favor engagement with Beijing than the ruling DPP party, did very well in local elections in November. Those elections were not a referendum on Taiwan’s policy towards the mainland but nonetheless provided impetus for Beijing to recently tone down rhetoric towards Taiwan. However, the DPP’s likely candidate will be vice president William Lai (Lai Ching-te), who has been more outspoken on the issue of Taiwan’s independence from China than current president Tsai Ing-wen. The risk is that if Lai looks set to win in January, it could provoke saber-rattling from Beijing, or more broadly hang over market sentiment given what would be a tense four years for China and Taiwan under his presidency. Beijing will also be watching how Taiwan is playing into the US presidential campaign in 2024 – the prospect of electoral victories by both Lai and an outspoken supporter of Taiwan in the US (e.g., Mike Pompeo) would be deeply troubling to China’s leadership.
Risk relative to expectations: Medium-high. Beijing will seek to avoid a crisis with Taiwan this year, though dynamics around Taiwan (and US) elections are important to monitor, especially in H2. We continue to see a low probability of direct military conflict over Taiwan in the next several years.
Upside surprise: A KMT victory in January 2024 elections would significantly lower cross-Strait tensions, at least temporarily, and likely boost Taiwan assets.
Signposts: (1) Polling for the January 2024 election, which is early but shows a competitive race; (2) treatment of China in the campaign, including rhetoric by William Lai, who has tweaked his messaging to downplay concerns over his past statements in support of Taiwan’s independence.
5. US-China tech competition hits supply chains
Description: US export controls on advanced semiconductor technology in October marked a watershed in tech containment of China. Washington will likely roll out further incremental export controls this year, targeting critical technologies including semiconductors, AI, biotech and quantum. There are risks to supply chains and markets but they do not appear acute in 2023. First, the Biden administration has been relatively careful to avoid major spillovers to supply chains thus far. Second, Beijing has been disciplined about not retaliating harshly (such as by restricting its own exports of rare earths), calculating that this could harm China’s economy and its role in supply chains. China will likely continue to focus instead on its own industrial policy to address key “chokepoints” (particularly in semiconductors) and lobbying companies/countries to find as much wiggle room around export controls as possible. Still, the risk of retaliation is there if Washington launches a major new broadside on the scale of October’s moves. Other areas we’re watching include the potential for executive and legislative action against TikTok (increasingly likely, but probably won’t trigger Chinese retaliation) and the likely debut of a new US screening mechanism for outbound investment in China in critical sectors (likely to be fairly narrowly targeted for now, and won’t impact portfolio flows).
Risk relative to expectations: Medium. Tech competition will stay at the center of the US-China rivalry and continue to impact specific sectors – such as semiconductors — but sharply disruptive moves with a broad impact are not basecase.
Signposts: Indications of major moves on US export controls, and/or changes in Beijing’s rhetoric that hint at a shifting calculus behind retaliation.
Domestic Politics and Regulation
6. Tech sector gets a reminder of who is in charge
Description: One factor behind improved confidence in Chinese equities is Beijing’s messages of reassurance to the private sector, including several signals that the rectification campaign for platform and fintech companies has eased. There is a danger, however, that Beijing takes actions that undermine this sentiment. Recent weeks have seen reports that China’s government is buying “golden shares” in units of Alibaba and Tencent, following precedents such as ByteDance, which could include government board representation and governance oversight, particularly into those platforms’ media content. Another report, which thus far seems overstated, suggests the government may launch a state-owned ride hailing app that is meant for Party members and government employees and challenges the market for Didi.
Risk relative to expectations: Medium. China’s leadership is trying to strike a balance between ensuring that big tech stays well within political and regulatory guidelines while also not undermining the vitality of the sector. Given Beijing’s clear intent to boost confidence this year, we doubt that there will be a new regulatory campaign that hits the platform economy. However, there will be smaller reminders for investors that the “new normal” for the tech sector is a tighter regulatory environment than before the tech crackdown, and firms will continue to have to adjust their business models and practices to suit Beijing’s strategic priorities, which could mean expensive investments in areas such as semiconductors.
Signposts: Political statements and regulatory actions (approvals as well as enforcement measures) towards platform companies.
7. Common Prosperity comes back with a force
Description: The visibility of Xi’s “Common Prosperity” agenda has repeatedly waxed and waned since 2021; the Party Congress in October made clear that it remains a key part of Xi’s agenda, but it didn’t get a mention among the priorities for 2023 laid out at the Central Economic Work Conference in December. The potential risk here is that, especially as growth and confidence improve, Xi re-emphasizes “Common Prosperity” in ways that increase market concern over the regulatory and political environment for the private sector – tougher tax treatment, pressure to back philanthropic initiatives, etc.
Risk relative to expectations: Low. We view this as a relatively low risk for 2023, given Beijing’s focus on boosting market confidence, and the fact that Common Prosperity is likely to be more of a technocratic initiative – focused on longer-term institutional reforms to income distribution – than intense political campaign.
Signposts: Treatment of Common Prosperity at the National People’s Congress in March.

