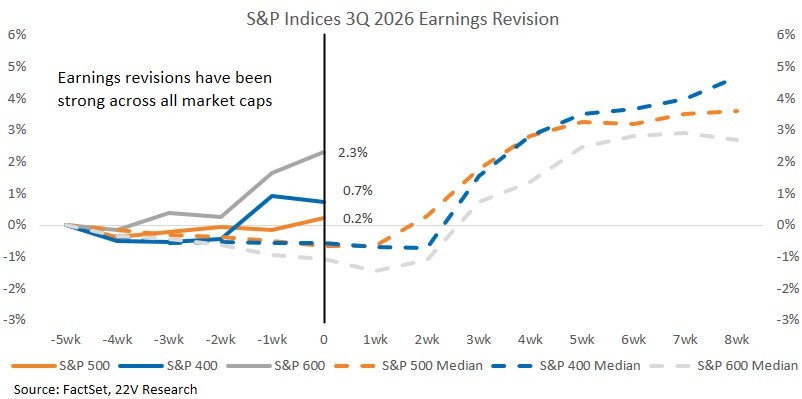
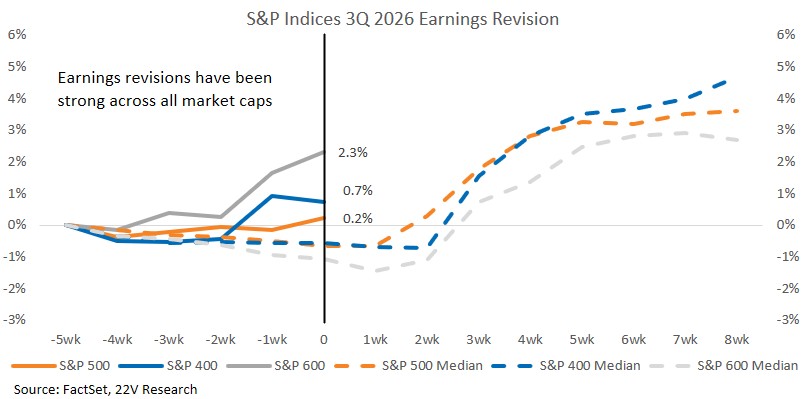
The outlook for 3Q earnings season remains strong ahead of banks reporting next week. Earnings estimates have moved higher across all market caps since late August, despite the start of the Fed’s rate hiking cycle. Small caps have recorded the largest upward revisions. Energy leads estimate upgrades across large and mid cap universes, ranking among the strongest sectors for small caps, while Industrials and REITs face broadly declining revision.
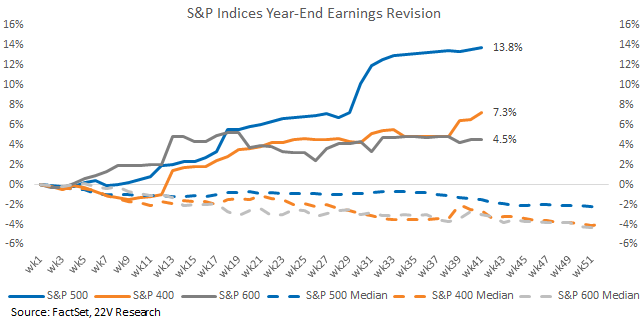
Positive quarterly revisions align with rising full-year earnings expectations. Unlike the historical pattern of estimates declining as the year progresses, 2026 forecasts have strengthened, particularly for large caps.
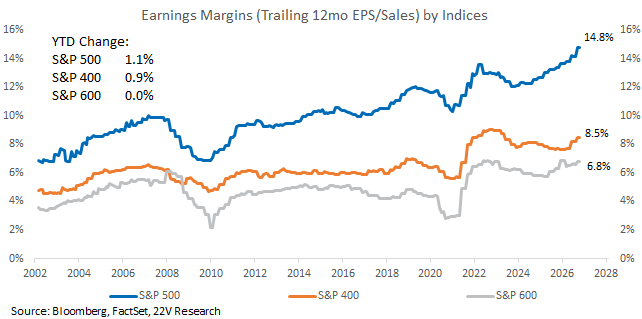
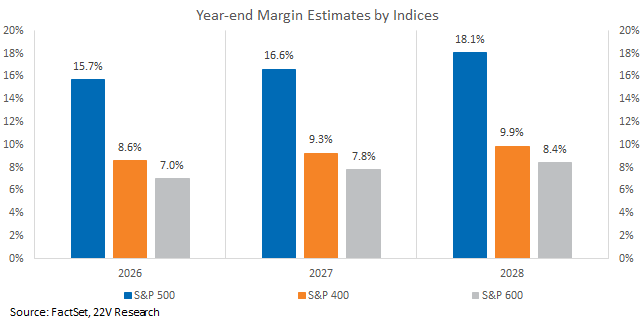
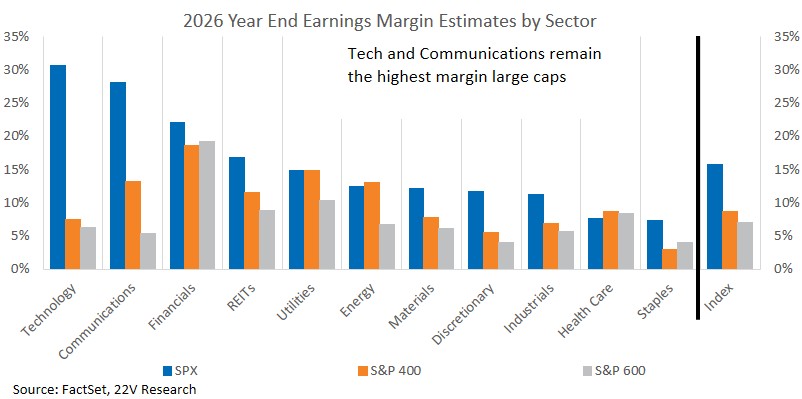
Profit margins further support the outlook, with large caps maintaining the highest trailing margins and posting the greatest improvement over the past year. Although mid and small cap margins have also increased, their gap with large caps has widened. Forward estimates suggest this divergence will continue, driven primarily by Technology and Communication Services. Financials’ margin outlook is more balanced across market caps.
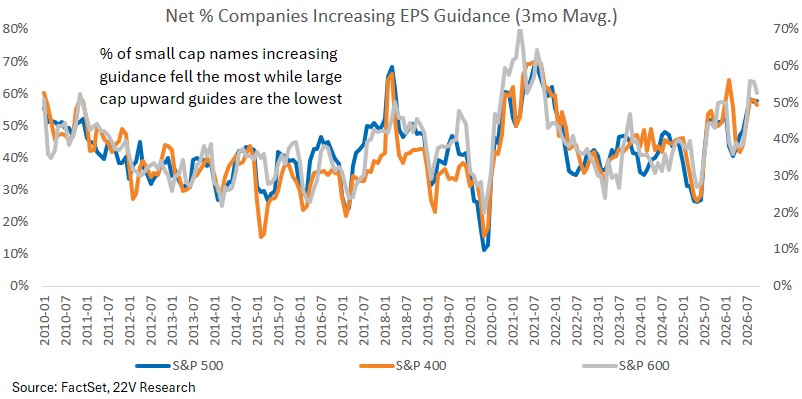
Corporate guidance nevertheless introduces some caution. Since 2Q reporting season, the share of companies lowering earnings guidance has increased, particularly among small caps, while fewer small-cap companies have raised guidance. Sales guidance shows a similar pattern. However, negative guidance remains below its historical median and large-cap guidance has been comparatively stable. Overall, improving estimates and margins support a healthy earnings backdrop but weaker small-cap guidance warrants attention.
Earnings outlooks remains strong
Banks are kicking off 3Q earnings next week. For now, the outlook for the earnings season remains strong. Revisions have been moving upward across all market caps since the end of August, even as the Fed has started the rising cycle. Small caps have the largest upward revision.
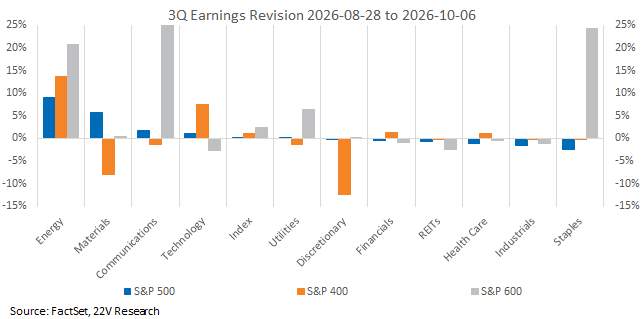
Breaking down by sectors, upward earnings revisions have been strongest for Energy in large and midcap universe, and one of the highest for small caps as well. While Industrials and REITs quarterly earnings estimate revisions have broadly declined.
Strong 3Q earnings revision is in line with upward year-end earnings estimates. Earnings outlook this year has been unusually strong, especially in the large cap universe. The median year-end revisions typically trend lower during the year, but in 2026 earnings revisions all have been moving higher. S&P EPS estimates for 2026 are up to $354 from $313 at the start of the year.
Margins favor large cap, especially Tech & Communications
TTM profit margins of large caps are the highest of the cap segments, largely driven by mega cap Tech, and index margins increased over the past year as well. By comparison, though margins for midcap and small cap also improved, their spread with large caps has widened.
Estimates of forward margins remain highest for large caps, and based on current estimates, the margin spread between large cap vs midcap or small caps is likely to continue to widen. Midcap and small cap margins are also expected to expand, but by a smaller degree. Forward margin estimates confirm a healthy fundamental outlook for S&P companies.
Technology and Communications are the leading margin sectors within large caps, suggesting AI investment and hyperscalers debt issuance are not weighing on margins, and they are also the main driver for the big margin spread between large vs. other market caps. Financials margin outlooks are more evenly distributed across all market caps than Tech and Communications.
Guidance painting some earnings concerns
However, earnings guidance for S&P names suggests some concerns. The percent of companies decreasing guidance elevated since 2Q, especially for small caps though the current 40%th percentile reading doesn’t suggest a serious earnings issue. The reading for large caps fell marginally, which is in line with a better year-end outlook for large cap earnings and margins.
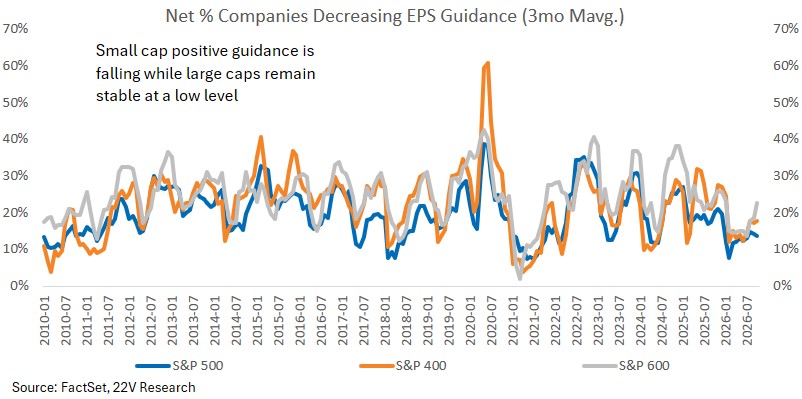
The companies increasing earnings guidance has also dropped the most for small cap universe since 2Q earnings with the reading for large cap roughly flat. The sales guidance follows the same pattern for different market caps as well.