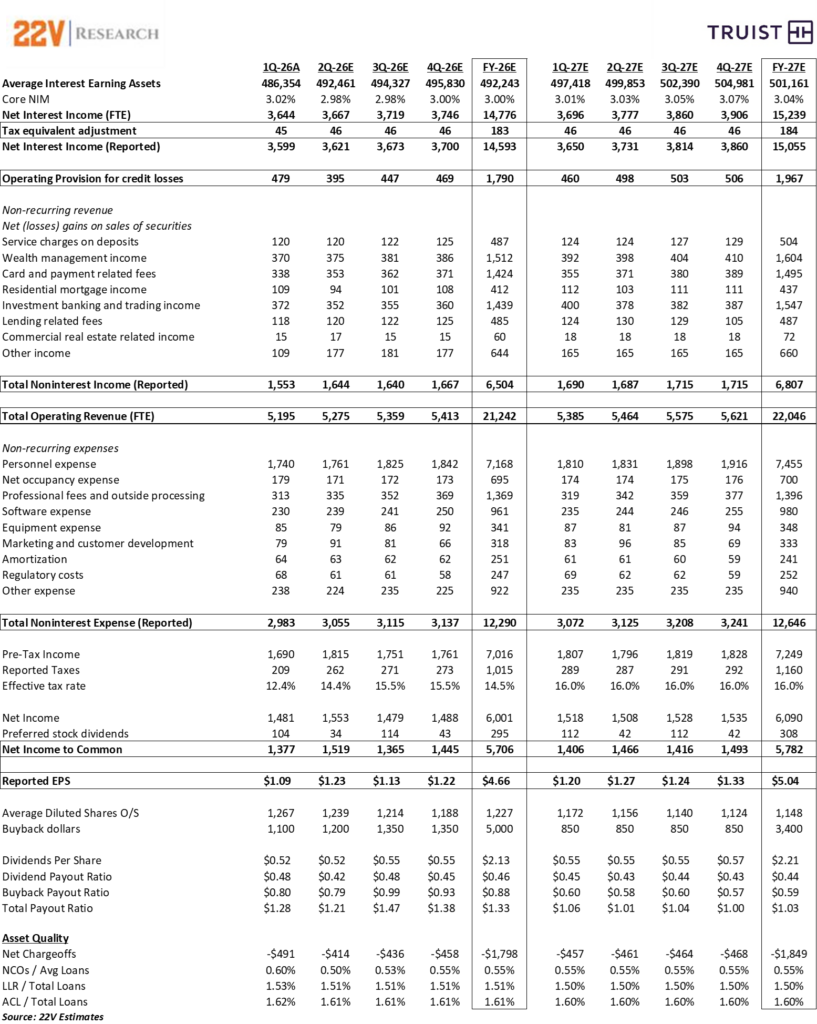
- Higher short-term rates are a negative for Truist with their current balance sheet positioning. With the majority of the cash flow swaps becoming effective from 3Q’26-1Q’27, a hike in short term rates would create more NII drag as the hedges move further against TFC. While recent inflation data has come in more benign of late, a series of more inflationary data could always derail that, especially given more hawkish rhetoric from Committee members.
- The current FY’26 NII guide of +1-1.5% (down from 2-3% last Q and 3-4% in 1Q) now looks to be more reasonable. Truist is currently assuming a hike at the September meeting. We at 22V currently are not sold on a hike that quickly. However, if the Fed were to hike in September because of the data we see between here and there, our NII would be up more like 1.1% and we’d still be ~0.7% below consensus on a PTPP/share basis this year and another 1.2% below for next year. If we assume no rate hikes being forecast in 2H’26/FY’27, TFC gets to 1.25% NII growth for FY’26 and our PTPP/share for FY’27 is essentially bang in line with consensus. A good rule of thumb as far as our model goes is that each hike costs TFC ~1% to PTPP/share or ~$0.07 of EPS.
New CEO Mike Lyons starts on 9/1. What will his take be?
- With Mike Lyons starting in a few short weeks, investors have been a bit concerned that as with any incoming CEO from outside the company, he may take the opportunity to “reset the bar.” We think there is some validity to the thought about him wanting to put his imprimatur on the bank. As we look at the different options for him relative to the way we look at and model Truist, we tend to believe the most realistic scenario would be to restructure/terminate at least part of the swap portfolio.
- Why? How would that work? With the current pay and receive rates largely offsetting each other, the current drag from the swaps is fairly diminimus. However, if TFC were to wait until a rate hike or two, the incremental expense would increase quickly. As it is, the negative AOCI drag went from ($572mm) at April 1 to ($1,035bil) for the cash flow hedges thanks to just the changing forward expectation for the path of short-term rates. From a mechanical standpoint, the next things to consider are how much of the swaps would you want to terminate along with the amortization timeline? From a broad brush standpoint, we would use as an example the fact that management has pointed out that they would have ~$80bil of active cash flow swaps in 3Q. If they were to cancel half (as an example), in theory you would take half of the $1bil AOCI impact ($500mm), realize it and amortize the expense over the life of the swap (usually 3-4 years). In this example, $500mm/12 quarters = (~$42mm/Q) of terminations plus whatever is already running through the terminated swap line plus the mark to market on whatever swaps are still active. In short, it would increase the swap drag assuming the Fed does nothing but would end up being less of a drag in totality should the Fed start hiking.
- How would investors react? In our opinion, investors tend to react positively to transparency. The opaqueness of the swap disclosures to date we believe are part of the reason why investors have had difficulty narrowing down the range of outcomes for TFC in any given Q. We think a good example of clean disclosure facilitating a re-rate in the stock has been Citizens Financial (CFG). Even though their swap drag was significant, the detailed disclosure on active and terminated hedges and the PnL impact helped give investors confidence in the numbers especially as the drag lessened. In the TFC example, given the Fed hasn’t moved and the swaps are essentially “at the money” if you think about it from an options standpoint, you’d essentially just be amortizing the time value of the option (the ~$1bil) rather than the option (swap) itself also being in the money and having to amortize that piece as well.
In sum, we believe we’re moving into a more consequential time for Truist between here and year end that will hinge on the Fed rate path combined with any potential early actions by Mike Lyons relative to what he envisions for Truist. How quickly anything were to take shape remains to be seen, but we believe it’s worthwhile to start gaming out some scenarios now particularly around the swaps which we think will become bigger discussion points over the coming months. As for our estimates, we move our FY’26 & FY’27 estimates up from $4.52 and $4.94 to $4.66 and $5.04 respectively with the key deltas relative to our original expectations being better fees and lower provision offsetting lower NII. We’re largely in line for the remainder of the year/next year assuming no Fed action/no balance sheet restructuring. As we noted earlier, Fed hikes and/or swap terminations would increase the drag on earnings from here, the magnitude of each will be key. We continue to rate as Sector Underperform.