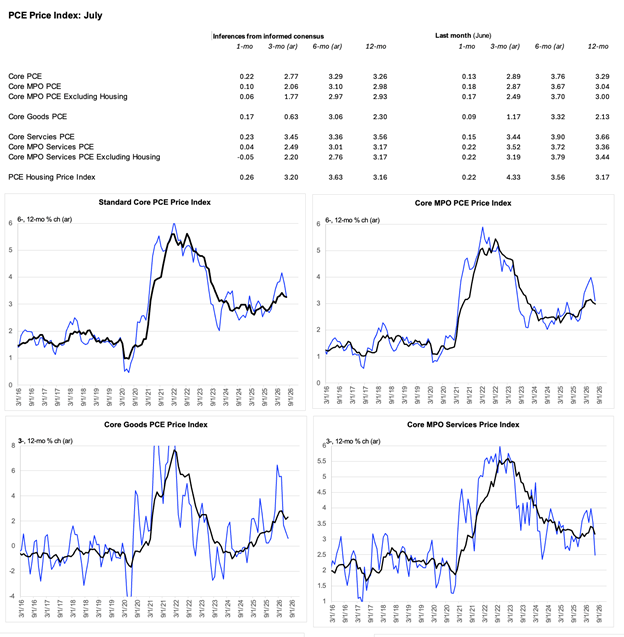
My perspective on the PCE inflation tracking for July has become more friendly since the release of the PPI for two reasons. First, I now know with great confidence how much of an add the consensus bean counter has factored in from portfolio management and advisory fees. It is 11 bps. And because I know this, I also know what the consensus has factored in for the Core excluding this obvious source of noise. The fact that the estimate went up today is irrelevant. It means that the best guess of the Core excluding that went down. (Yesterday, this was insufficiently obvious to me.) Second, and closely related, the PPI brought favorable news on airline fares.
Accordingly, the informed consensus implicitly has the Market Price Only (MPO) version of the Core PCE rising only 10 bps in July. And, if I may, the street is burying this important point by engaging in the greater fool game, recognizing that the portfolio management and advisory fees are nonense, but assuming that other people will be stupid enough to care. The Fed will not be that stupid.
One interesting aspect of this is that the distortion from portfolio management and advisory fees is concentrated in services, where the distortion is closer to 19 bps. So, the MPO version of the Core is expected to be up just marginally during July and the supercore there is actually expected (implicitly) to have fallen.
That is the good news, and it points away from a rate hike in September, as you can see to a limited extent in the price action and as is a bit more explicit in some of the shops cutting their September rate hike call. But there are two elements of complexity here related to revisions, which you may have heard about and which I want to address.
First, folks are talking now about revisions that will come with the September data. The thing about this is that it is old news. And the revisions will be concentrated in those same portfolio management and advisory fees which you should already be stripping out anyway. Those data are wrong and the BEA is now recognizing that. Outside this area, there will be downward revisions of just under 10 bps. But that was known and factored in a couple months ago, I assume.
Second, I have seen some discussion of the Core PCE being revised higher for June for reasons that have nothing to do with that methodology change. But the folks I follow most closely are not identifying a case for revision, so for now I will assume that is not an issue. If I am wrong about that, then what is under discussion here would soften but not overturn the main point of this note.