

Heading into their first earnings report as a public company, 22V’s Dauvin Peterson believes shares could see a meaningful rally given the large decline from the highs, as well as there still being a lot of negative sentiment regarding possible share unlocks. Shares are now down more than 50% from their post-IPO highs and are currently trading at their lows as we await their earnings on Tuesday after the close.
SpaceX shares now down more than 50% from their post-IPO highs

When I look at the volatility setup for SPCX options, I see a scenario where the front-month (August) vol continues to trade extremely “rich” to the outer months. While this is likely a function of the upcoming earnings, I just don’t believe this calendar skew is warranted. In fact, an argument can be made that if you want to play for a move back higher in SPCX shares, that owning longer-dated calls that not only capture earnings but will capture other potentially key events is the “better” play. Owning calls out to October, for example, will capture the earnings on 8/4, the 14th Starship flight in late August to mid-September, as well as the Nasdaq rebalance in late September which should lift the current weighting.
The SPCX August (earnings) 25-delta calls now trading at a massive vol premium to the October 40-delta calls
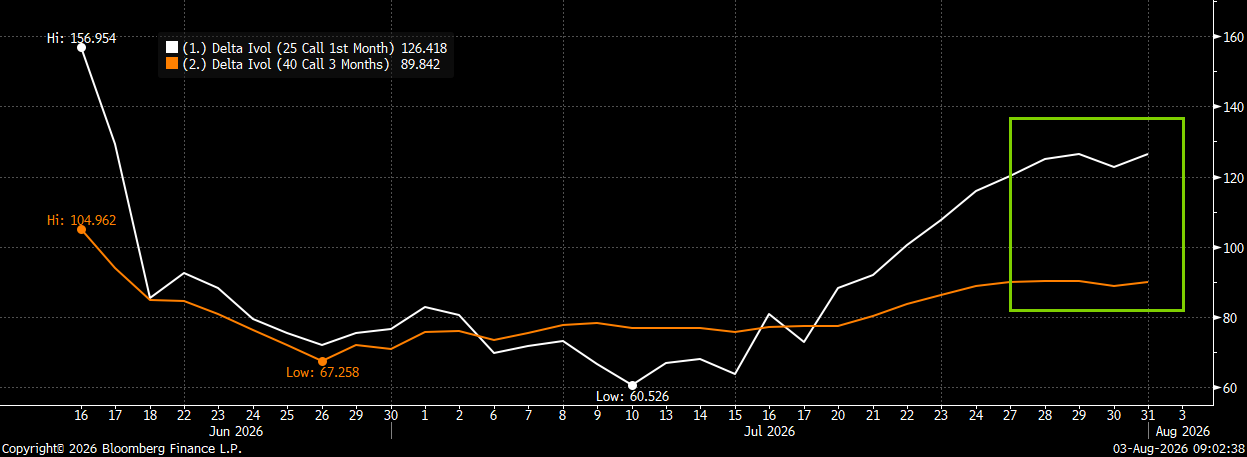
With SPCX Aug vol trading a full THIRTY+ points above where the October options are trading, I think this is a great opportunity to add upside call calendars in the name that will capture this attractive skew.
Trade:
Sell SPCX August 21st 140 calls (24d, 125 vol)
Buy SPCX Oct 16th 130 calls (40d, 92 vol)
Costs ~ $7 (SPCX 107 price ref)
Trade Details:
- Buying the longer-dated and higher-delta October call vs selling the shorter-dated and lower-delta August call
- Selling the August call covers roughly 40% of the cost of buying the October call (speaks to the very attractive call skew)
- Prefer to own October over August not only because of the cheaper vol, but capture other catalysts such as Starship 14 flight as well as NDX rebalance
- IF the August 140 calls do come into play, the structure is likely to be worth approximately double (when factoring in the 10point spread between the strikes and expected vol premium still embedded in the Oct calls)
- Once the August calls expire, can also then consider selling upside calls against the Oct 130 calls (depending on where stock and vol are trading)
- Limited-risk way to add upside exposure in the name after the large decline, while also taking advantage of very favorable call skew
- Please reach out to me or the 22V sales team for updated pricing and execution capabilities

