

Hyperscaler results from META and MSFT this week (as detailed below) have the potential to be market moving. MSFT has taken an open-source position and therefore the capex trajectory and its AI strategy will be critical points to follow in this recently accelerated debate.
META’s further clarification around its neocloud strategy could move names that have significantly underperformed since the announcement on July 1st. Thematically, names like ORCL, CRWV and NBIS may be positioned for a relief rally after their recent pullback. The abbreviated reasons are that SPCX and now META are leading the way to monetize compute in a very tight market (not oversupplying it) and other neoclouds that have early leads on compute acquisition and execution sit at a unique point with optionality and increasing values for their compute or advanced AI factory orchestration capabilities.
Liquid cooling and traditional HVAC names have several reports, and we detail below that the market is closely looking for continued signs of backlog growth, margin expansion and updates around liquid cooling or other AI factory advanced thermal management trends. We continue to favor single-phase liquid cooling exposure and believe two-phase cooling has been pushed out and to the right.
Why are AI capex stocks not working? Against the backdrop of what is a supply-constrained compute market, there are several challenges hitting the AI investment trade right now and creating a rotation out of these names given the lack of clarity.
- Margins and returns have disappointed so far this earnings season. Hyperscaler spending rates and the search for ROIC and margin expansion remain elusive. The investment is likely to show long-term benefits, but the market is concerned about the size of the bet right now.
- China’s rapidly growing influence over AI including models, chips, memory as well as creating a paradigm shift in thinking about an open-source AI approach vs closed models. There is also the potential for US regulatory responses.
- The imported volatility of Asian market equities generating increased US AI trade volatility as the correlation remains high among all AI-related names (picks and shovels, memory, chips and more).
- Market sentiment has declined for future IPOs from Anthropic or OpenAI given SPCX and SK Hynix’s ADR (SKHY) listing breaking deal prices and open source concern around closed AI model constructs.
Underneath these macro headlines, as can be seen by spot indexes for compute and confirmed by our channel checks, and as evidenced by Google’s incredible cloud revenue growth rate, compute is very tight and in high demand. The H100 spot index is our best measure today and that index remains at its highest level. One might consider that this index could drive higher if the open-source adoption of K3 takes up even more scarce compute resources.
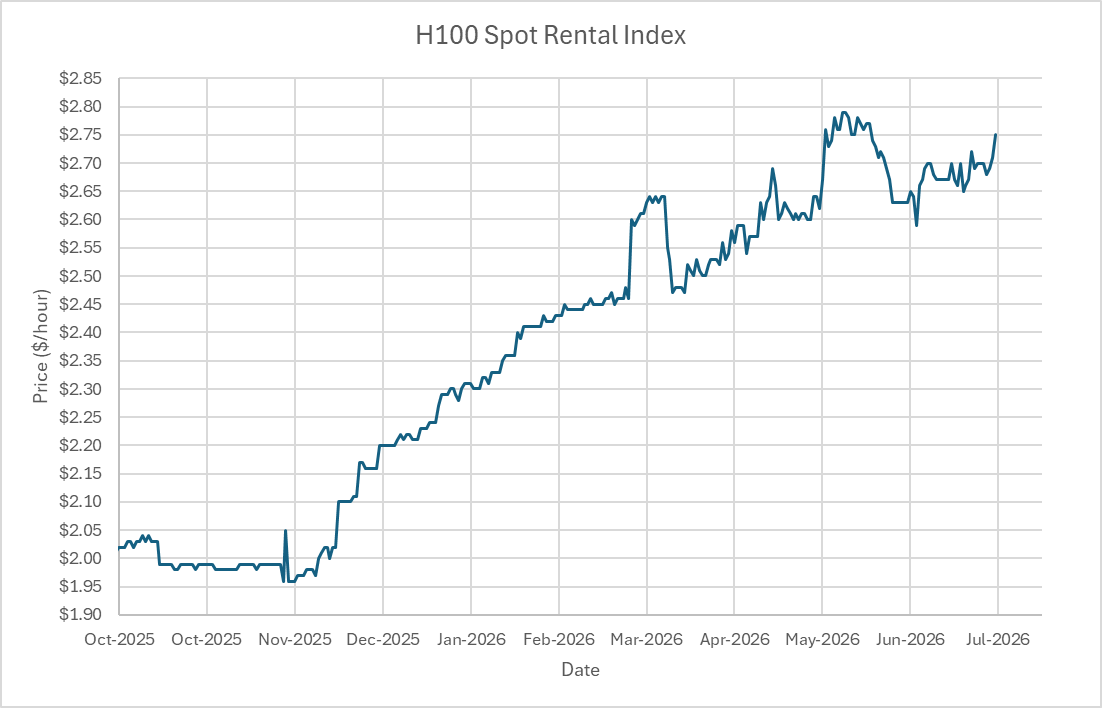
Source: Bloomberg
We have additionally seen several new AI infrastructure projects contemplated or announced in recent days to limited reception: OpenAI – Georgia; OpenAI – Ohio; SpaceX – Texas. Ordinarily these would receive reasonably strong reception from AI infrastructure stocks as they add to a longer-term build-out narrative.
Hyperscaler earnings this week / potential implications:
- AI Infrastructure: As with Google’s directionally positive capex trajectory, we would expect similar capex growth guidance to be directionally positive for AI infrastructure (macro considerations and company-specific margin or backlog concerns aside).
- Neoclouds: Thematically, early movers on compute acquisition that have successfully scaled AI factories are reaping the benefits of compute scarcity. SPCX and META have paved the way showing the pricing power that can be commanded. Since Meta’s announcement to rent excess compute, the market has continued to sell neoclouds and early movers (ORCL, CRWV and NBIS) due in part to concerns around competition and what appear to be unfounded fears about compute over-supply; with shares declining 21.5%, 27.8% and 32% respectively. The disconnect between higher prices for compute and neocloud stocks is only getting wider, and META’s tone on scale, timing and intentions could clarify and lead to neoclouds or early movers gaining traction and notice again from investors.
Hyperscaler Capex: The updated consensus forecasts for capex and FCF show Google’s 2027 spend moving up towards $287B (+$23B since earnings) reflecting a nearly 45% growth y/y in spend:
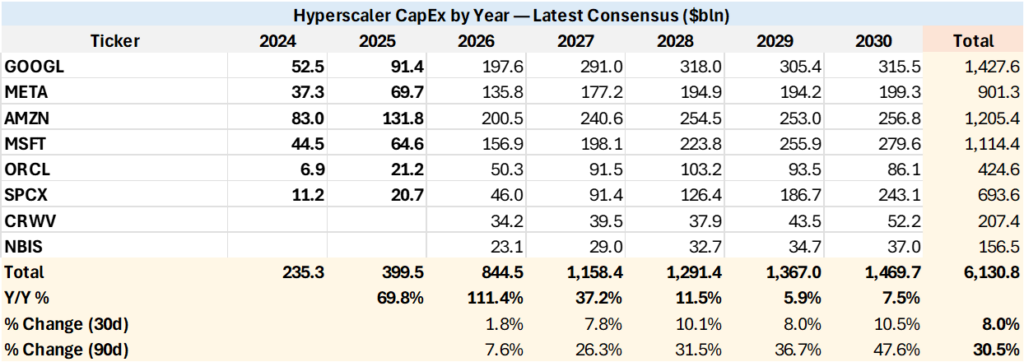
Source: 22V Research; Bloomberg
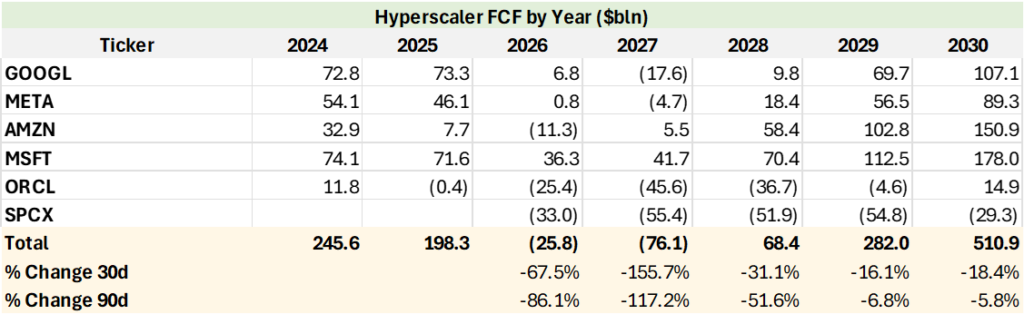
Source: 22V Research; Bloomberg
- MSFT (Wed): Two primary focus points: 1: Capex guidance heading into calendar 2027: Capex guidance for 2026 (Calendar year) is $190B, and this quarter it is expected to start hitting at least $40B in capex per quarter. Consensus remains roughly flat y/y in calendar 2027. 2: AI strategy. MSFT has become a notable supporter of open-source proliferation and as this appears to be becoming central to its strategy within the organization, a clear outlook as to how AI is impacting and improving its business and how cloud growth and margins are trending will be closely watched.
- META (Th): Capex and the neocloud business are front and center. Consensus for 2026 capex sits at the midpoint of the $125–145B guide. This implies a healthy ramp in 2H quarterly capex, and the market will be keen to dial in 2027 growth trajectory. Also as noted above – the commentary around the pace and scope of their plans to rent compute could have important implications for the neocloud stocks that have underperformed as a result of this entry into the market.
Liquid Cooling / Thermal Management:
ECL and CARR reported today (pre-call comments below).
CARR (-): Data center +300% y/y now guided to be $2B of rev vs $1.5B prior for 2026 — positive industry directionally for DC. Impact to stock in pre-mkt appears to be that while there is a slight bump to EPS/Rev outlook, FCF stays the same and multiple segments margin growth expectations were dialed back in the slides — the gains are all revenue led. *Similar to the GEV, DOV calls thus far — investors are looking for margin expansion.
ECL (+): Slight EPS beat and upward tightening of recent 2026 EPS guide (+2c/share to $8.05–$8.25). This was expected to be reasonably quiet here — conf call details on the go-forward liquid cooling and Ovivo businesses around semi-fab will be a focus for me. They are executing well on price in their other businesses and recapturing raw material costs. I expect this is in line / positive driven by the conf call.
JCI, MOD (Wed); TT, VRT (Th); ETN, NVT (Fri): Focus on incremental liquid cooling trend discussions as well as order rate and margin trajectories.
Please reach out with any questions or follow ups in these areas.

