Back Banks

US Bancorp: The re-rate continues – Raising Target to $70 and reiterate Sector Outperform

Published on July 19, 2026

∙ Download the PDF Report

By

Bill Hebel

Brian Herlihy

  • Record Results & Accelerating Revenue Growth. U.S. Bancorp delivered a strong 2Q 2026, reporting record net revenue of $7.7 billion (+10.1% YoY) and diluted EPS of $1.35 (+22% YoY). On a PTPP/share basis, USB reported a 2.7% beat relative to consensus and a 3.1% beat relative to 22V. Net interest income on a taxable-equivalent basis reached $4.4 billion (+7.5% YoY), exceeding the company’s own +6-7% guidance, driven by solid loan growth across commercial, CRE, and credit card categories. Average total loans of $405.5 billion increased 7.1% YoY and 3.0% linked quarter — broad-based across virtually every commercial category with strong pipelines. Fee revenue surged 13.2% YoY (9.9% ex-BTIG), reflecting accelerating momentum in capital markets, trust & investment management, payments, and institutional fees. The company delivered 400 basis points of positive operating leverage YoY, its eighth consecutive quarter of positive operating leverage as adjusted, while improving its efficiency ratio to 57.1% (56.7% ex-BTIG). Return on tangible common equity reached 18.7% and ROA improved to 1.26%, both now comfortably within the company’s medium-term target ranges established at its 2024 Investor Day.
  • BTIG Closes, Accelerating Capital Markets Strategy: USB closed their acquisition of BTIG on June 1st. In its first month as part of U.S. Bancorp, BTIG generated approximately $98 million in fee revenue — a record monthly performance for BTIG that outpaced management’s own expectations and ran at a $1.2 billion annualized rate. Management guided to approximately $200 million of quarterly net revenue contribution from BTIG in the back half of 2026 at a 15%-20% contribution margin, alongside roughly $60 million of integration costs expected to be recognized in 2H 2026. Capital markets revenue totaled $512 million in 2Q 2026 (+62.5% YoY), representing approximately 7% of total company revenue; management’s long-term target is 10%+. The strategic rationale centers on cross-selling BTIG’s equity trading and advisory capabilities into USB’s existing commercial and institutional client base rather than meaningful headcount expansion — an organic, balance-sheet-leveraged path to the 10% target that management appears confident in based on early cross-sell activity observed in June alone.

  • Guidance Upgraded; Amazon Partnership Adds Near-Term Momentum. Management upgraded full-year 2026 total net revenue growth guidance to +7%-9% YoY (inclusive of BTIG). Ex-BTIG, USB raised their organic revenue guide from the prior +4%-6% range to +5%-7%. Positive operating leverage guidance was maintained at approximately 200 basis points including BTIG and 300+ basis points excluding BTIG. For 3Q 2026, management guided NII growth of +4%-6% vs. 3Q 2025 and fee revenue growth of +12%-14%, with total noninterest expense growth of approximately 8% (core ex-BTIG: ~3.5%). The anticipated mid-August close of the Amazon small business co-brand card portfolio (~$1.6 billion of loans transitioning from Amex/Mastercard) represents an incremental $75-85 million per quarter in total revenue (approximately 2/3 NII, 1/3 fees) once fully ramped in 4Q 2026, with a $160 million reserve build expected at closing. NIM expanded 2 basis points sequentially to 2.79%, and management reiterated the path toward 3% NIM in 2027, with fixed asset repricing ($10-11 billion per quarter at ~100-125 basis points of pickup), improving earning asset mix, and the Amazon portfolio all cited as tailwinds.
  • Credit Quality Improving; Capital Position Solid. Credit quality continued to improve across the board in 2Q 2026, reflecting a stable macroeconomic backdrop and broad-based client health that management characterized as not overly concentrated in any single sector or theme, including AI/data centers. The NPA ratio fell to 0.33% (-5 basis points linked quarter, -11 basis points YoY), net charge-offs declined to 0.53% (-3 basis points LQ), and the credit card NCO ratio improved to 3.83% (-13 basis points LQ, -47 basis points YoY), with delinquencies across 30-89 and 90+ day buckets also declining sequentially. The allowance for credit losses stood at $8.0 billion (1.94% of period-end loans) with only a nominal $2 million net reserve build. Capital remained stable at a CET1 ratio of 10.8% (9.4% including AOCI) despite absorbing the BTIG acquisition (~12 basis points of CET1 impact) and strong loan growth, with $200 million in buybacks completed in the quarter. Management confirmed it is on the “last lap” of capital build, intending to glide total capital return higher toward the 70%-75% long-term payout target as CET1 approaches approximately 10% on an adjusted basis, and announced a planned ~4% increase to the quarterly common stock dividend beginning in 3Q 2026 (subject to Board approval).

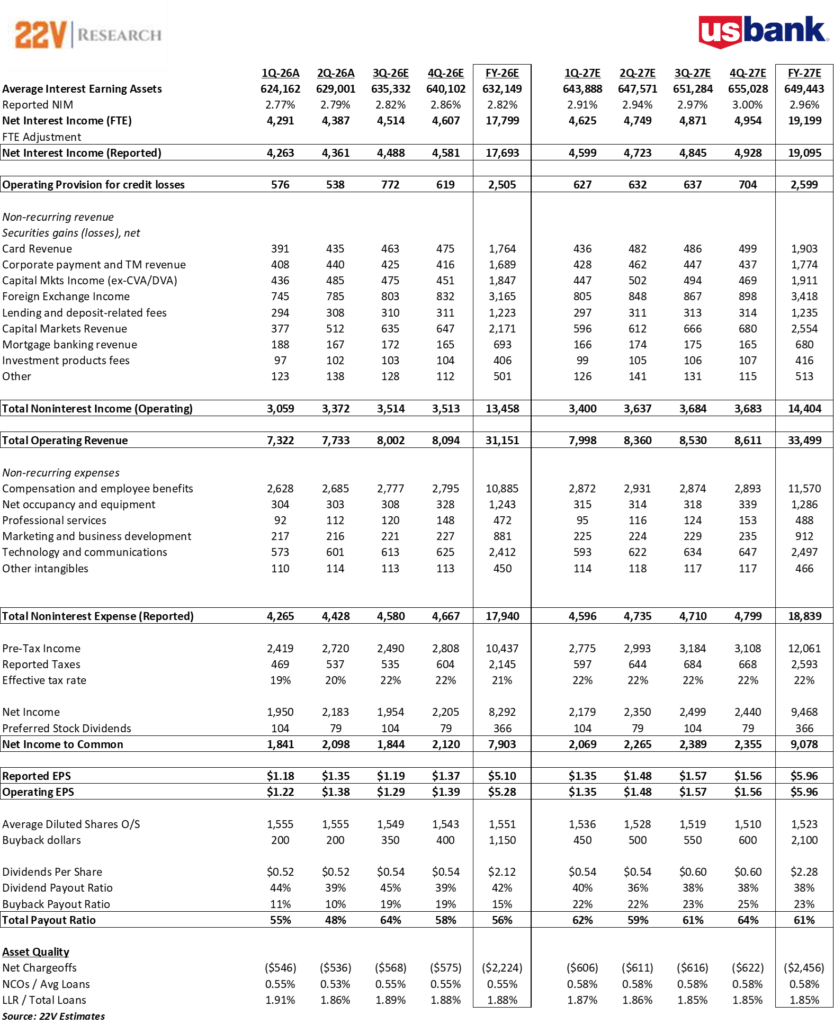
Our take: We believe this quarter, while a bit noisy with the inclusion of a partial quarter of BTIG, is yet another step in the USB re-rate story. The only drawback we saw in the Q was the step back in the merchant processing business due to the weakness in Europe and the loss of some non-strategic distribution partners. That said, USB did a good job offsetting with the BTIG addition and the strength in the underlying capital markets business which along with the addition of the Amazon portfolio next Q will offset the tougher merchant processing compares in the next few quarters. In terms of the key drivers going forward, we see continued fixed asset reprice as a bigger tailwind for USB given the absolute level of their current margin (easier to move the needle higher when your margin is 2.79% vs. RF or MTB ~3.7%) and the ~$10-$11bil rolling each Q. We’re at the high end of next Q’s 4-6% NII guide (we’re at 6.2%) as well as the fee guide of +12-14% (we’re at 14.3%), and have full year NII at 6.3% growth vs. USB’s “north of 5%” estimate. For FY’26 total revenue, we’re at +8.5% relative to the +7-9% guide which contemplates ~235bps of positive operating leverage. As we’ve mentioned in past notes, USB is also in a unique position in that their capital return is accelerating while peers are begin to decelerate. We’re estimating that their buyback will double by Q4 vs. the $200mm this Q and ramp further in ’27. We raise our estimates for FY’26/FY’27 to $5.28/$5.96 from $5.18/$5.83. We raise our target to $70 which is ~12x our new ’27 estimate. As we look at our forward PTPP/share estimates relative to consensus, we’re now 0.6% ahead for ’26 & 2.0% ahead for FY’27 which is even better than the 1.5% ahead pre-Q for FY’27. In sum, we believe the USB re-rate continues to accelerate with the better NII glidepath meeting better fees and more capital return. With our Q4’27 NIM at 3% and better fees/more capital return, we see USB consistently hitting their medium term ROA/ROTCE and efficiency targets. As such, we reiterate our Sector Outperform rating.
  • Company Statistics

    Stock Rating: Sector Outperform
    Price: $63.14
    Price Target: $70.00
    52-Week High: $64.84
    52-Week Low: $43.46
    Market Cap: $98.355B
    Dividend Yield: 3.3%

    Financials

    2025 2026 2027
    Revenue (MM) $28,540 $31,042 $33,499
    EPS Estimates Q1 1.03 1.18 1.35
    Q2 1.11 1.35 1.48
    Q3 1.22 1.19 1.57
    Q4 1.26 1.37 1.56
    $4.62 $5.10 $5.96
    Consensus EPS Estimates Q1 1.03 1.18 1.31
    Q2 1.11 1.35 1.44
    Q3 1.22 1.32 1.51
    Q4 1.26 1.38 1.54
    $4.62 $5.20 $5.77
    P/E FY $13.7 $12.4 $10.6

    One Year Performance Chart

    USB07/2510/2501/2604/2607/2610/26010203040506070
    *Source: EOD Historical Data

USB 3 Year Price History

Sector Perform47.50Jun 17Sector Perform49.00Aug 27Sector Outperform55.00Dec 5Sector Outperform61.00Jan 8Sector Outperform61.00Mar 17Sector Outperform64.00Apr 20Sector Outperform70.00Jul 19Jul2023Oct2023Jan2024Apr2024Jul2024Oct2024Jan2025Apr2025Jul2025Oct2025Jan2026Apr2026Jul2026Oct2026010203040506070
*Source: EOD Historical Data

Current Rating Distribution

Coverage Universe Percent
Sector Outperform 31.25
Sector Perform 50
Sector Underperform 18.75

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.