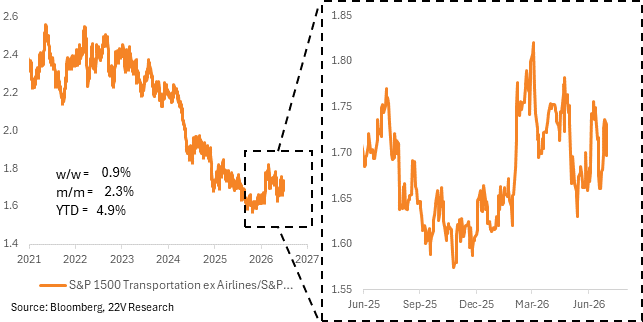
DAILY STRATEGY: MAIN POINT: Transports ex Airlines, which saw a record drawdown relative to the S&P 1500, are rallying alongside other non-AI cyclicals (Banks, Retailers). Transports are benefiting from an inflection in activity and a reduction in supply (HERE). Transports management teams have highlighted benefits from the AI buildout. That buildout is unlikely to slow anytime soon. Freight rates (ex-fuel surcharges) are rising, reaching their highest point since 2021. NTM earnings, sales, and margin estimates are all increasing. Margin compression had been a significant industry headwind that is now fading.
DETAILS: Trucking demand has picked up. Maersk reported on Tuesday, raising EBITDA guidance from $8B to $10B, up from $4.5B to $7B. They increased their forecast of global container demand from 2-4% to 4%. Peter Williams, 22V Economist, writes “Before the war we had seen clear signs of the global manufacturing cycle recovering in high-beta economies after 3yrs of sluggishness, much like in the US the war seems to be a shock but not a large enough one to derail the underlying cyclical momentum. It just now comes with a bit of a volume hit and inflationary aftereffects.”
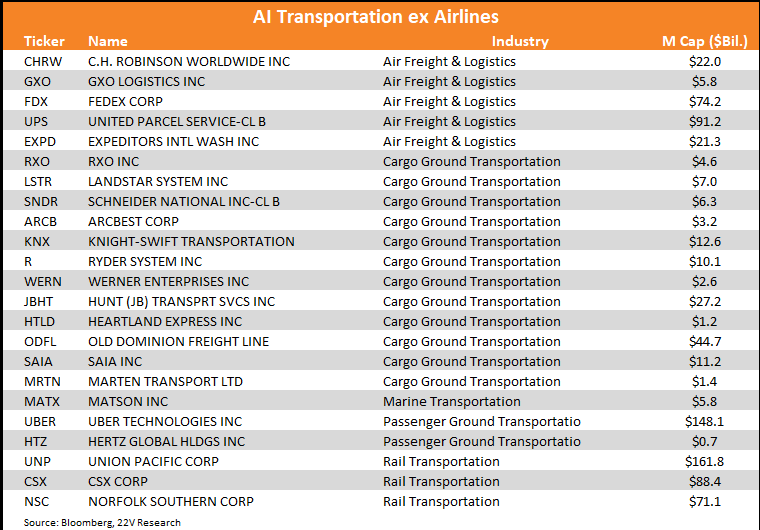
The global manufacturing cycle is recovering, and there appears to be an AI buildout effect helping Transports. 23 of the 37 S&P 1500 Transport stocks mentioned AI as a tailwind in their Q1 earnings (table below). That AI buildout tailwind is unlikely to abate anytime soon. Dauvin Peterson, head of 22V Data Infrastructure/Commodities Research, had the opportunity to connect with a handful of operators and developers across the AI factory build-out recently (HERE). The overarching theme is that the market remains compute constrained for the foreseeable future and that hyperscalers and AI builders are likely to continue front loading the AI build-out. The AI buildout tailwind for transports will continue.
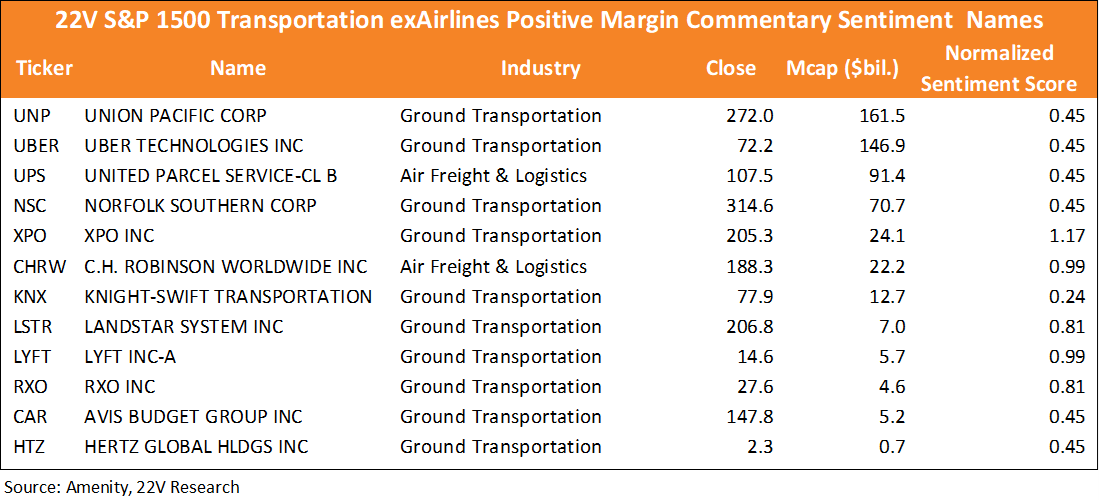
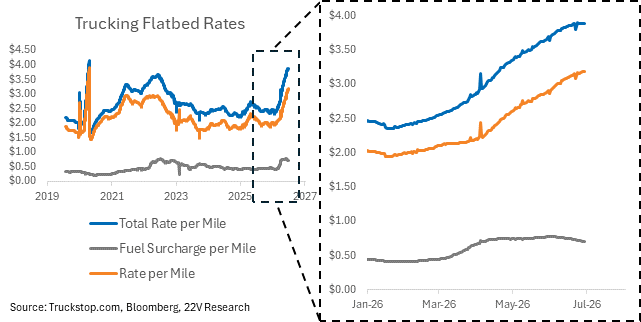
US transports had lagged partly because of oversupply – there was a spike in small, private truckers during COVID. That oversupply has faded (HERE) and now trucker rates have increased (ex-fuel surcharges) to their highest level since 2021. NTM earnings, sales, and margin estimates are all increasing. Margin compression, in particular, had been a significant industry headwind. We tabulate the Transports with the best forward-looking margin sentiment below; this is a good list to start looking for individual longs.
Risk – If inflation is too hot over the course of the summer (defined by Core PCE coming in well above the 0.21% MoM), Transports will underperform as financial conditions tighten. The biggest risk to Transports, and other Cyclicals, is inflation. Tighter financial conditions would reduce inflation but also increase recession probabilities.
FYI, RXO, and ARCB are the only two Transports that have referenced specific use cases of AI during earnings. Their forward-looking margin sentiment is better than the index average. Deployment of AI, not just tailwinds from AI, are a potential tailwind. We will be monitoring usage comments and margin sentiment.
Charts…
Transports are bouncing, albeit volatilely.
Flatbed rates, ex fuel surcharges, are increasing and at their highest level since 2021.
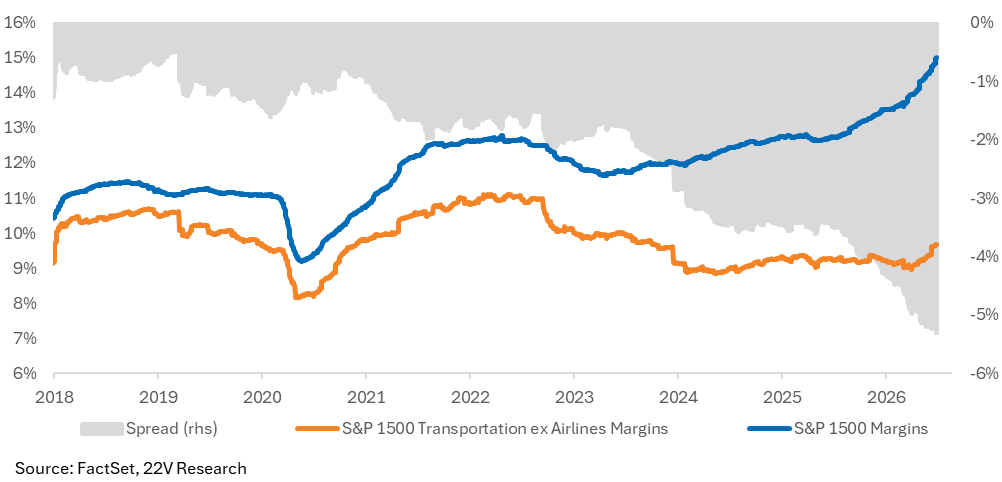
NTM margin estimates are moving higher for the first time since 2021 too.
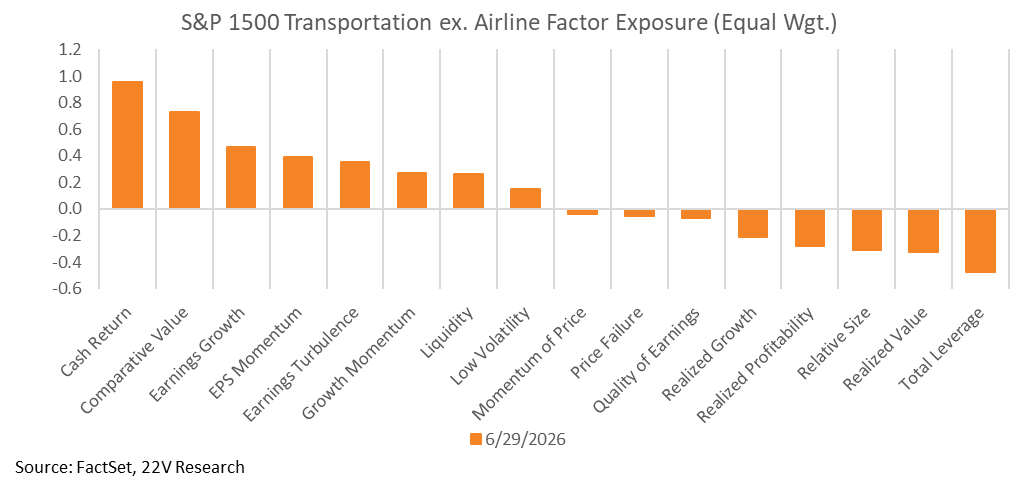
Transports are positively exposed to risk-on factors, highlighting the pressure they would come under IF financial conditions tighten. Their EPS Mo and Growth exposure, coupled with some AI tailwinds, may help, but they have not traded alongside AI buildout names (yet) this year.
The below names are the Transports who have mentioned AI as a tailwind.
Below are the Transports with the most positive sentiment about the forward outlook for their margins. Given how significant a headwind margins have been, this is a good list to start looking for individual longs.