

June FOMC: Hawkish Dots Drive the Show
- At least 9 participants on the FOMC believe that a hike in 2026 is the appropriate baseline policy outlook, 8 think no further change is appropriate, and only 1 submitter thinks a rate cut is a baseline.
- Inflation was revised sharply higher this year and a bit higher next year, inflation risks remain highly elevated, and risks to the labor market fell appreciably. These hawkish changes were matched by Warsh and the statement’s emphasis on ensuring that inflation returns to 2%.
- If policy in 2025 was driven by risk management cuts aimed at preventing nonlinear labor market easing after the tariff shock, 2026 may be defined by hikes preventing further, linear, inflationary overshooting.
- The new Chair announced the formation of 5 task forces focused on: communications, the balance sheet, economic data, productivity and jobs, and the Fed’s inflation framework (but not its target). How directly these bear on the policy path outlook and reaction function is unclear.
- While elevated inflation and the distance between policy rates and the zero lower bound have been pushing up interest rate volatility, it seems that Fed policy is likely to be volatility additive as well for some time to come. Some may favor increased shorter-term interest rate vol in exchange for plausibly reduced leverage and credit risks, but it will be a challenge to adjust to.
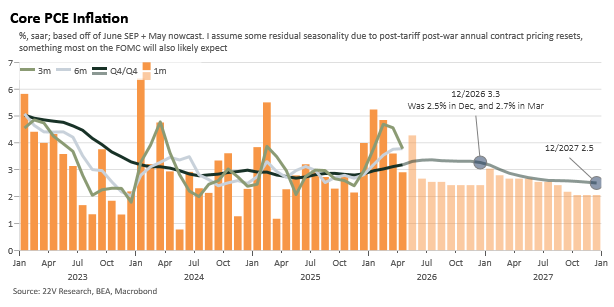
The summary of economic projections showed an appreciably worse inflation outlook with the core PCE forecast revised higher to 3.3% in 2026 (from 2.7% in March and 2.5% in Dec), 2.5% in 2027 (from 2.2%) and only returning to target in late 2028. Growth was revised down a small amount, largely reflecting the soft Q1 data in hand (an echo of the hot inflation which has pushed up the forecast), and the unemployment rate forecast fell just a 1/10th in 2026. Nearly as important, the FOMC’s assessed risks to inflation continued to move higher while the risks the unemployment rate fell sharply. The mild improvement of the labor market data since the beginning of the War has run counter to mild easing expectations. The Fed has long operated as though inflation is a largely linear problem while labor market risks tend to more about jumps into nonlinear recessionary environments so a decline in labor market risks and slightly upgrade in the baseline forecast has an outsized impact on policy.
The Dot Plot Was More Hawkish than Expected. While the shifts in the SEP largely reflected the incoming data with a bit worse inflation momentum added onto it, the FOMC’s patience for looking through those shocks has clearly fallen. 9 of 18 submitters expected that a hike would be the appropriate baseline policy choice this year, while only 1 saw a cut as appropriate. This is being driven by yet another upside inflationary surprise, the continued drift higher in the long-run dot (while the median did not move the distribution moved up and the average is now 3.2%), and surprising growth momentum (a higher rate path with an effectively unchanged growth forecast suggests that there is some overheating risk the Fed wants to guard against). While not explicit, nor would Warsh want it to be made so, the Committee has clearly shifted towards a more hawkish baseline while allowing for the possibility that with a reset higher in their inflationary path there is a chance that the data allows them not to have to hike this year. The hawks still have enough time to wait and see if their baseline views are consistent with the data over the summer before really pressing the issue but the data may well force a more aggressive sooner path too, and it seems that it will take only very small upside surprises to bring many at the median on board given how the more dovish part of the distribution shifted higher.
It is worth noting that above and beyond the still fairly benign post-May core PCE path, it only takes an extra 0.2pp of inflation (i.e. a couple of 0.3s or an 0.4) to match the maximal 3.5% core PCE forecast for this year, which was consistent with 2x or 3x hikes.
The Complete Rewrite of Statement Left Little but Hawkish Hints. With Warsh now Chair, the FOMC’s statement was dramatically shortened. This cut much of the explanatory text from the statement and left us much less communication to go off of. What remained was largely, but not entirely, hawkish in nature. As was widely expected he framed the elimination of the old easing bias as a broader elimination of forward guidance. The double reiteration of inflationary pressures felt hawkish (“the Committee will deliver price stability”) after noting solid growth despite uncertainty caused by the War. The inclusion of what Warsh noted was a supply-side sentence, “productivity growth and capital investment are strong,” served as a potential balance given the way he often framed AI and a potential productivity acceleration as serving as potentially disruptive and deflationary forces going forward.
Inflation in the Driver’s Seat. It may not be a particularly palatable point for many, but the basic fact is that policy skews and baselines are following inflation higher. This has been the clear message from many on the FOMC since even before the April meeting and it continued today. Notably Warsh did not push back all that much; his historic inflation hawkishness seems to be consistent with potentially more hawkish policy implementation here. That seems to match the broader tone heard from the White House recently, which has naturally found it more difficult to criticize their appointed Chair and clearly negative political costs from still elevated inflation. I suspect I will be returning frequently to his working definition of the Fed’s task when confronting volatile supply shock-driven inflation, which is to “[ensure that individual price changes] don’t broaden in the economy, [or] have second and third order effects.” This is quite hawkish, with more than a little flavor of the ECB, because it suggests that it is not a policy to look through supply-side shocks causally but rather to look through their near-term effects monetary policy can’t reasonably offset but to still try and counter their medium-term impacts.
Mixed Signals on Neutral but Moving Higher. Despite policy rates remaining roughyl5 50bps above the Committee’s median estimate of neutral, in his assessment of the stance of policy Warsh suggested that the signals there were quite mixed. This matches the recent tone from Powell and many others and hints at a somewhat less anchored model-centric approach to the subject. He noted that the housing market is still sluggish but he “would have a hard time managing to say those words if I were to see what’s happening in financial markets.”
Warsh Clearly Has a Reform Agenda. What it Means for Rates is Less Clear. The announced reform agenda from Chair Warsh meets his long-promised desire to shift a number of policy paradigms. The new Chair announced the formation of 5 task forces focused on: communications, the balance sheet, economic data, productivity and jobs, and the Fed’s inflation framework (but not its target). It is very early to come to any firm conclusion but I suspect there will be two more concrete rate path relevant shifts out of these task forces. First, the Fed is likely to restart QT or at least engage in a duration swap of UST for T-bills by 2026Q1; that will come with some attendant plumbing risks and regulatory and operational shifts which will be needed to offset them but seems manageable in time. Second, the SEP and dot plot are likely to be substantially modified and see reduced input. We could receive much less communication. It is also possible that the Fed moves towards a more analytical Monetary Policy Report-like model; examples from the ECB, BoE, BoC, and RBA, among others, all handle the issue somewhat differently but all feature a central forecast usually premised on market pricing, more rigorous backward looking information, and greater emphasis on scenario analysis than the SEP. This would not necessarily be a change for the worse, potentially just amounting to a different flavor of the semi-annual Monetary Policy Report from the Fed, but it would require notable shifts and potentially upset some internal political dynamics at the Fed. Warsh may push for an even simpler report without a forecast component or simply nothing at all, leaving us in a much more different world.
We have a lot to learn about a potentially appreciably differently reformed Fed and the new Chair over the next 6-9 months but the data and Fed’s dual mandate anchors remain the primary drivers of monetary policy. On those fronts the signal is clear enough.

