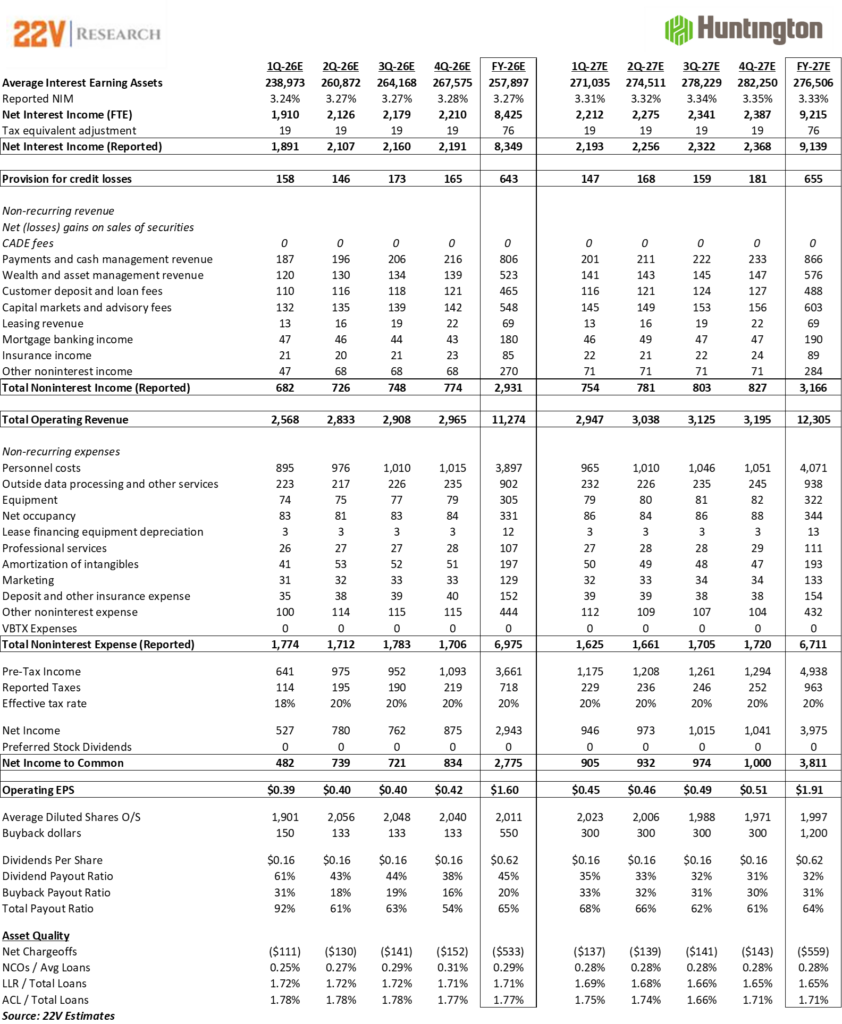
HBAN CFO Zach Wasserman delivered a “steady as she goes” message at an investor conference last week, reiterating their most recent targets and even opining that they feel incrementally better about the world relative to April when they gave guidance on their 1Q call. Zach cited both strong pipelines/customer demand as well as a higher long end of the curve as an even larger benefit to NII than originally expected and more sustainable into 2027.
Regarding the net interest margin, Zach mentioned that they were also on track relative to the April guidance of a high 3.20’s exit to 2026 followed by continued NIM improvement into ’27. As mentioned earlier, the higher long end helps on the fixed asset reprice. In the shorter term, HBAN mentioned that they will work to optimize the Cadence deposit costs more in 3Q once they are through conversion with the intent being to optimize some of the higher cost buckets of both core and wholesale funding. By implication, there may still be some inefficiency in the 2Q deposit costs but hard to get a handle at this point. We actually have NIM up 3bps QoQ which may or may not be too aggressive. Given the noise still moving through the P&L, we’re more focused on the NII for the full year which we have +39.1% in line with the low end of the +39-43% NII range YoY (which is the guide).
On the fee side, Wasserman highlighted the trifecta of payments, wealth & capital markets all three of which are growing double digits aided by the recent Janney acquisition.
On the expense front, HBAN once again reiterated the guideposts for both the Veritex and Cadence acquisitions. With the Veritex system conversion completed back in January, HBAN expects to realize the full run rate of $70mm in synergies this Q. For Cadence, the systems conversion is expected to be done in the middle of this month with HBAN realizing $365mm of cost synergies by end of the 4th quarter of this year for a total of $435mm between the two franchises.
Revenue synergies are also a key to the guidance for FY’26 & FY’27. HBAN is targeting $50-$75mm in FY’26, $150mm in FY’27 and $300mm+ in FY’28. The opportunities run the gamut of funding efficiencies which we highlighted earlier to new market penetration which comes along with it additional lending opportunities and value-added fee based services within wealth, payments and capital markets.
Capital return is also key to the story with HBAN continuing to expect to repurchase $550mm of stock in FY’26 and between $1.1 and $1.2bil in FY’27.
So what to do with the stock? Given the recent move higher in the group there’s been a focus on the laggards. While HBAN has now taken the lead relative to upside to our targets based off our ’27 estimate, the degree of difficulty is not small nor are the assumptions trivial. While expense saves are a common assumption in any deal/deals, rare have been the instances of revenue synergies being forecast as part of transactions let alone a total of $500mm over 3 years. In the past, management has been loathe to buy back stock, preferring instead to acquire. With the share count up over 2 billion shares, there has been some consternation regarding inflections being muted when it comes to bottom line impact. Again, as part of the deal, HBAN has committed to buying back $550mm this year and between $1.1-$1.2bil next which will help begin to make some progress on the share count issue. We think HBAN is headed in the right direction and should be looked at for those with a longer term horizon. We have been advocating a catch-up trade recently in US Bancorp (which we continue to do). We feel that in a number of ways, USB is illustrative of the journey HBAN now finds itself on. It took time post the Union Bank transaction to complete the integration, to rebuild the capital, to get the capital return engine firing, and to start seeing positive revisions. We think USB is now hitting their stride with both positive revisions and the increase of capital return all for a few percentage points less in upside, but we would argue for much less operational risk. We would still prefer to focus on USB here in the near term for our best catch-up idea. We tweak our HBAN estimates slightly for a model refresh from $1.61/$1.94 for operating FY’26 & FY’27 estimates to $1.60/$1.91 respectively and reiterate our $19.50 target which is ~10.2x our FY’27 estimate. We continue to rate a Sector Perform.
Company Statistics
Stock Rating:
Sector Perform
Price:
$17.32
Price Target:
$19.50
52-Week High:
$19.46
52-Week Low:
$14.89
Market Cap:
$34.887B
Dividend Yield:
3.6%
Financials
2025
2026
2027
Revenue (MM)
$8,166
$11,279
$12,305
EPS Estimates
Q1
0.34
0.39
0.45
Q2
0.34
0.40
0.46
Q3
0.41
0.40
0.49
Q4
0.30
0.42
0.51
$1.39
$1.60
$1.91
Consensus EPS Estimates
Q1
0.34
0.37
0.44
Q2
0.34
0.39
0.47
Q3
0.41
0.41
0.49
Q4
0.30
0.44
0.51
$1.39
$1.58
$1.89
P/E FY
$12.5
$10.9
$9.1
One Year Performance Chart
*Source: EOD Historical Data
HBAN 3 Year Price History
*Source: EOD Historical Data
Current Rating Distribution
Coverage Universe
Percent
Sector Outperform
31.25
Sector Perform
50
Sector Underperform
18.75
DISCLOSURES AND DISCLAIMERS
Analyst Certification
The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.
Analyst Certifications and Independence of Research.
Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.
22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.
22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.
Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.
SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).
SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).
SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).
Limitation Of Research And Information.
This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.
Reproduction And Distribution Strictly Prohibited.
No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.
Copyrights, Trademarks, Intellectual Property.
22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.