Back Portfolio Strategy

The Fed is Likely to Allow Growth to Slow Organically Rather than Hiking Rates + Long Domestic Brazil

Published on May 29, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Kevin Brocks

Sophia Wang

DAILY STRATEGY: A recurring question in meetings is whether the Fed will raise rates. Our view is that the Fed will likely accept slower growth rather than hike rates. The economy SHOULD slow from the current unusually strong pace of underlying demand* as the fiscal impulse and post-tariff reacceleration tailwinds fade (consumer, business activity-ex AI – and hiring trends seemed paused in 2H25). If growth slows as we expect, the Fed is unlikely to cut. I.e. they will accept slower growth. Our call supports some flattening of yield curves over the next 3 – 6 months but is not negative for risk assets. Slower growth reduces inflation risk and inflation is the major constraint on the cycle now (HERE). FYI – our longer term view is higher deficits = steeper yield curves (HERE), hence the 3-6 month flattening call.

*Underlying demand = the sum of consumer spending and investments components of GDP. Generally considered a cleaner measure of economic activity as it removes the noise from exports and inventory swings. Underlying demand is currently estimated to be running at +3% in 2Q26.

Long Domestic Brazil – we were lucky enough to host a webinar this week with João Landau, Founding Partner & CIO of Vista Capital, one of Brazil’s leading hedge funds. Replay link HERE.


João thinks there is asymmetric upside in domestic-facing Brazil equities, with the presidential election as a catalyst.

The background supports are: 1) real interest rates stabilized around 8% over the past year, 2) the unemployment rate has reached historic lows (~5%), 3) inflation has exceeded forecasts but remains relatively contained given the urate (this has been a major surprise), and 4) Brazil’s equity market valuation has reached decade lows, with IVBX P/E ratios around 12x.

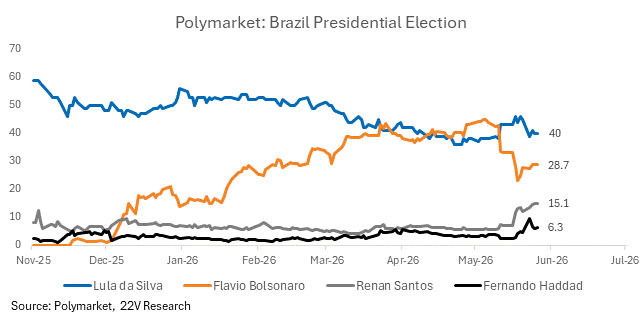
The upcoming election has been an overhang on the index. In short, investors REALLY dislike President Lula and Lula’s odds of winning have recently increased. But President Lula faces hurdles in re-election amid low approval ratings, especially among evangelicals and youth. The polls are misleading in Joao’s view. If Lula loses, there is asymmetric upside in Brazil equities that are more domestic facing. Joao made the case that local investors with money are likely to reallocate a significant amount of capital back to local Brazil if Flavio Bolsonaro wins.

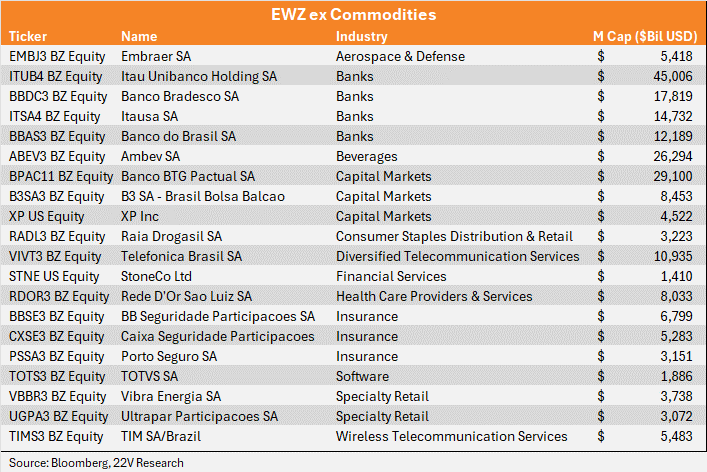
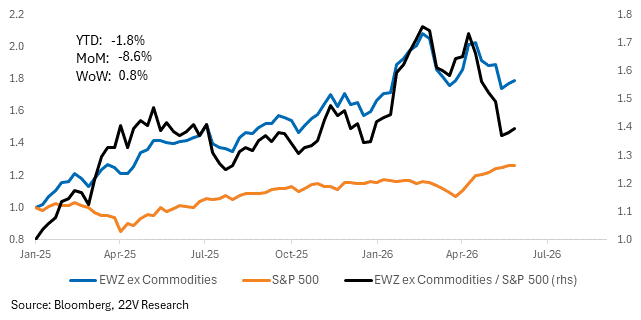
Joao notes it is underappreciated that fiscal adjustments, which are needed in some form, does not have to come with large hits to growth and significantly higher recession odds, particularly because the economy is starting from a point of strength. Own the EWZ ETF ex commodities. Commodities are largely driven by factors outside of Brazil but have large representations in indices. PBR (Petroleo Brasileiro) is an oil company with a 14.5% weight in the EWZ ETF. EWZ ex commodities, charted below, have fallen -14% as Lulu’s odds of winning the election have improved, which provides an interesting opportunity to be long now.

Charts below…
A graph of different types of stocks

AI-generated content may be incorrect.

A graph of a graph showing the results of the election

AI-generated content may be incorrect.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.