

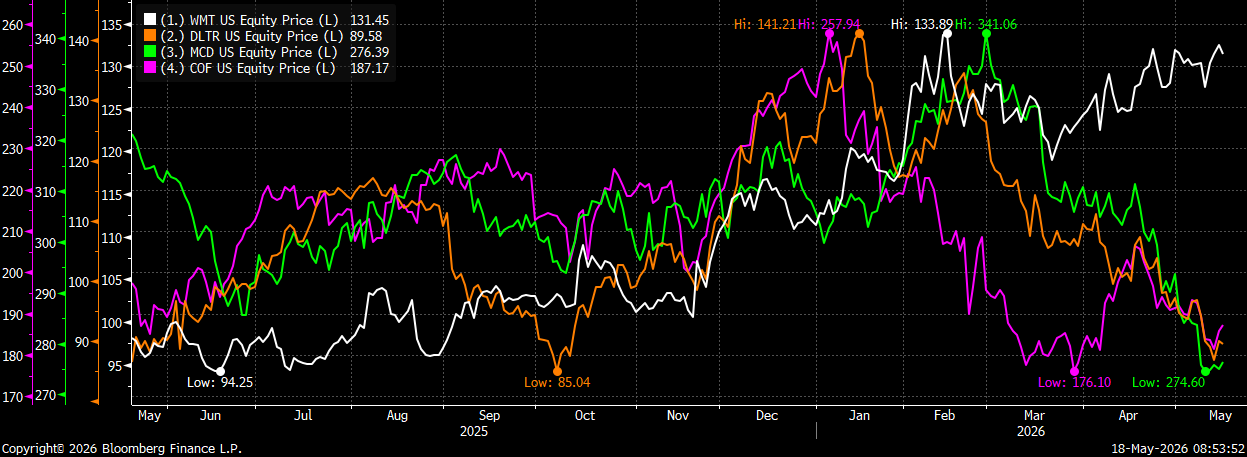
With Walmart (WMT) earnings expected to be announced later this week on 5/21, there are several things about WMT share price and valuation that stand out to me. First, with most (all) of the larger retailers coming under pressure as oil prices have spiked, WMT shares are up 18% YTD and are just below the all-time highs hit in Feb. What makes this outperformance to both the sector, and the overall market, even more astounding is that almost all of the other names that are more levered to the lower-end consumer are all trading at/near their YTD lows as well.
WMT shares are up ~ 18% YTD and are just below their all-time highs hit in February

WMT (white) has decoupled from the other names that are typically associated with the lower-end consumer (MCD,DLTR and COF)
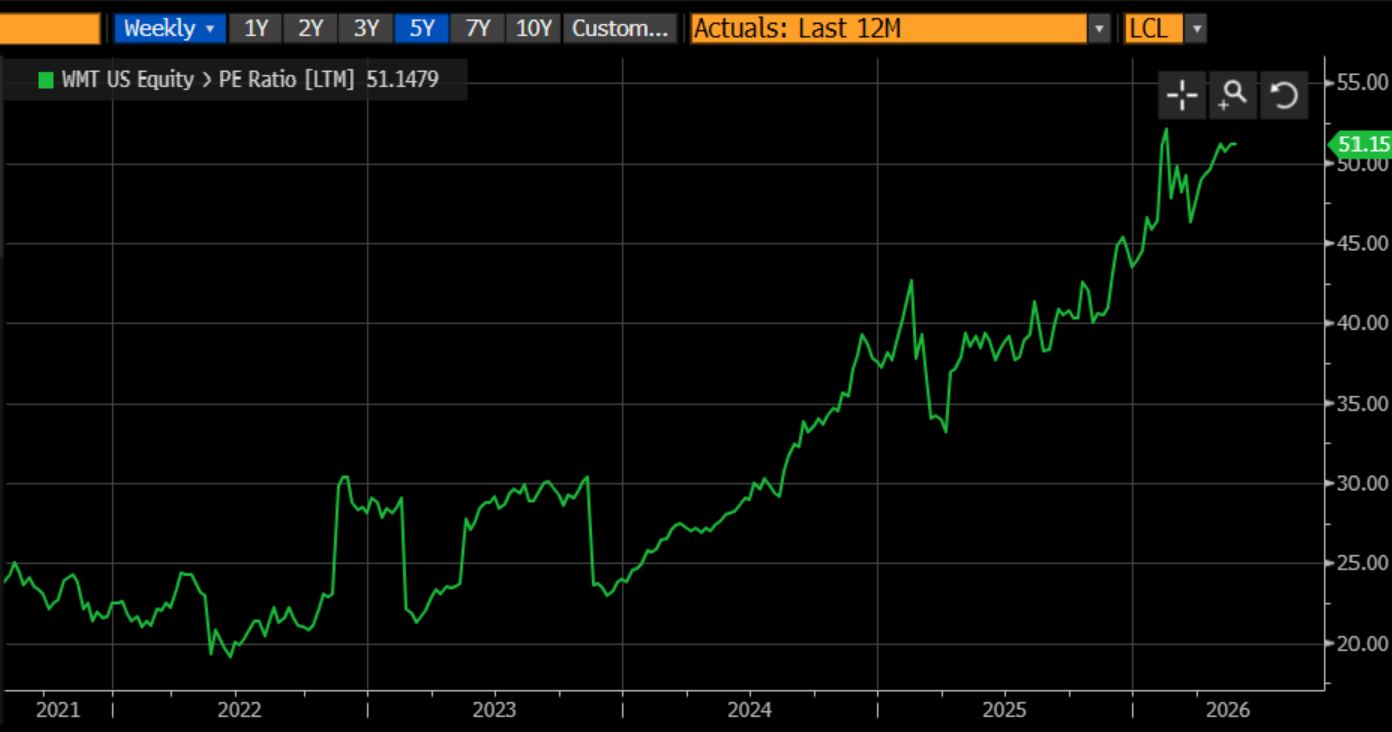
A big reason why WMT shares have performed so well is that we have seen massive multiple expansion in the name over the past few years. The multiple has more than DOUBLED from the 20-25x range to a current P/E that is closer to FIFTY. While still a retailer at heart, the market has afforded WMT with a multiple that is WELL above where most of the larger tech names trade.
WMT P/E has more than doubled over the past few years and it now trades at a much richer valuation that most of the Mag7 names
Given the sharp outperformance to the lower-end consumer names, coupled with a valuation that is “rich” by any measure, it seems that significant upside from current levels may be hard to come by for WMT. In addition, perhaps when they report later this week the market will not be too kind to them if they mention the potential negative impact that higher oil prices have had on their “average” consumer?
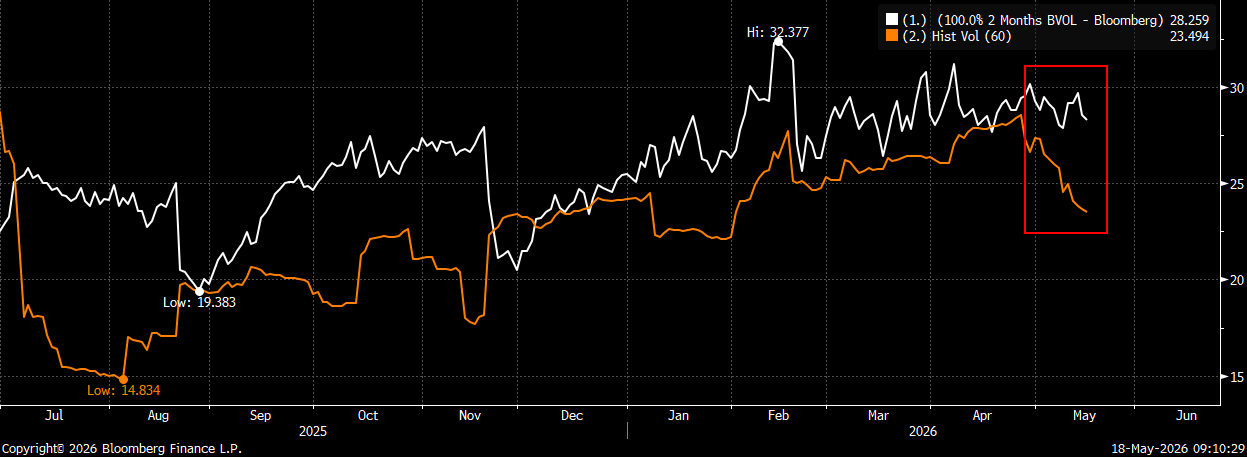
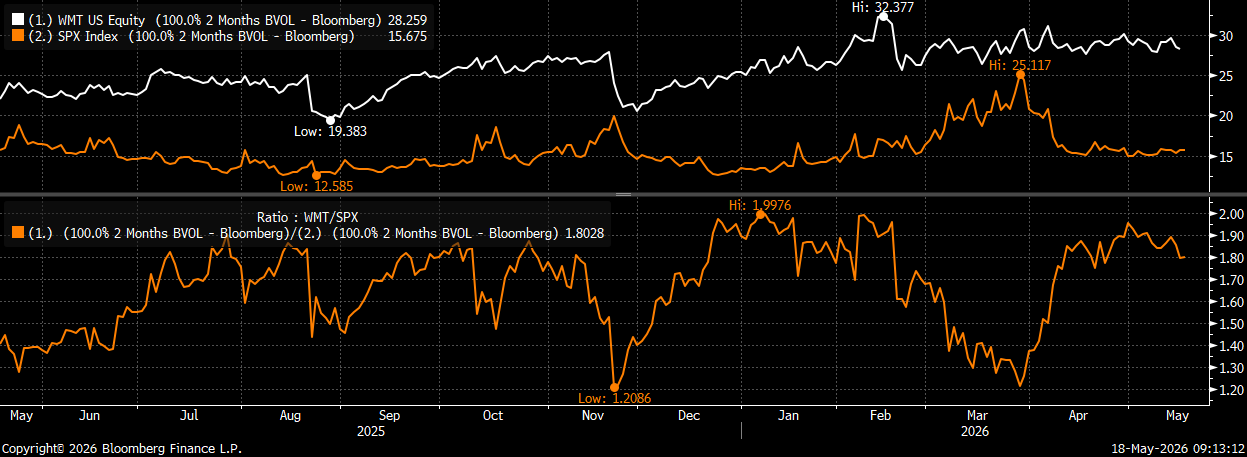
Finally, from a volatility perspective, WMT vol looks VERY “expensive” to me. Not only is 2-month (July) implied vol trading ~ 5 points over the 60-day realized vol, but WMT 2-month vol also trades at nearly TWICE the vol that 2-month SPY trades at. WMT has had a .5 beta to the S&P over the past 2 years, yet the options are trading at 2x the cost.
WMT 2-month (July) implied vol trading at a 5-point premium to 60-day realized vol
WMT 2-month implied vol trading at nearly 2x where SPY 2-month vol trades (even though it has had a .5x beta to SPX for 2 years)
Going into earnings this week, I just think the risk/reward for WMT shares are heavily skewed to the downside. It already trades at a VERY rich multiple, and perhaps we could see a “catch-up” trade lower to the other names that are also levered to the lower-end consumer that have done very poorly as of late (that also trade at much lower valuations). If long shares, or looking for downside structures, here are a few trades to consider:
July put spread collar trade:
Sell WMT July 145 calls
Buy WMT July 125/110 put spread
Costs ~ $0.50 (WMT $132.40 ref ref)
- Selling the 9%+ upside calls (with stock just below the all-time highs) to buy the 15-point wide put spread that starts ~ 5% below spot
- WMT vol is “rich” to both itself, as well as vs market (SPX), why I favor selling an upside call to own the downside protective put spread
- WMT has decoupled from the rest of the names that are typically levered to the lower-end consumer (could see a quick catch-up trade to the downside)
- Stock trades at/near FIFTY times earnings already, hard to see much more multiple expansion from here
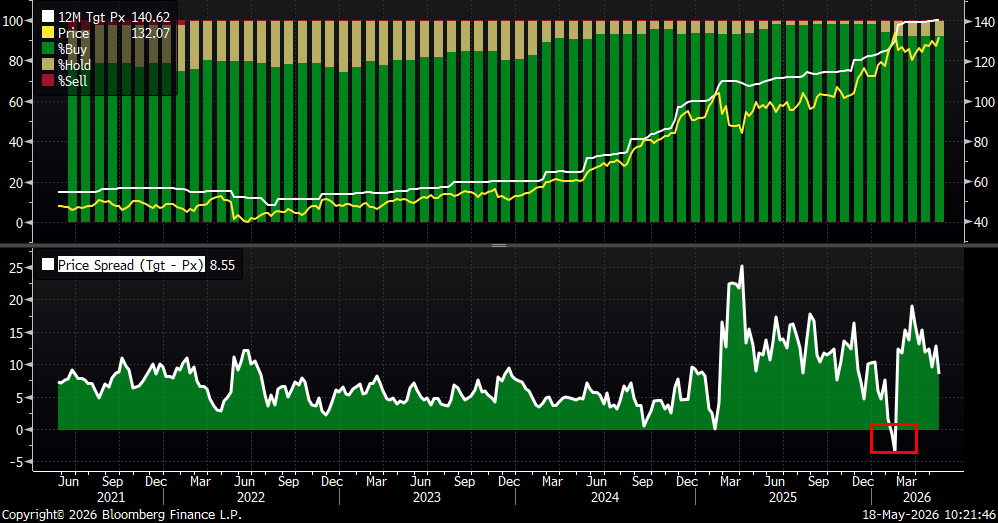
- Upside breakeven of 145 call strike is not only almost 10% higher from here, but is above the street’s average 12-month PT of $140.62 (WMT shares have traded above the street’s average PT ONCE in the last 5 years)
- Trade can be done against an existing long equity position, or as a synthetic short position with a large upside cushion (and minimal spend)
WMT current street 12-month PT is ~ $140. Have seen shares trade above that PT exactly ONCE in the past five years
July upside call sale
Sell WMT July 140 calls @ $3.15 (WMT 132.40 ref)
- Selling the 6% upside calls against an existing long equity position
- Stock is back at/near the all-time highs and already trading at nearly 50x earnings
- Call sale yields 2.3% (14% annualized), with an upside to $143.25 by July expiry (over 8% higher)
- Upside breakeven is also above the street’s average PT I mentioned above
- WMT vol is “rich” to itself (realized) as well as vs the market (why the upside covered call trade makes a ton of sense)
- Please reach out to me or the 22V sales team for updated pricing and execution capabilities

