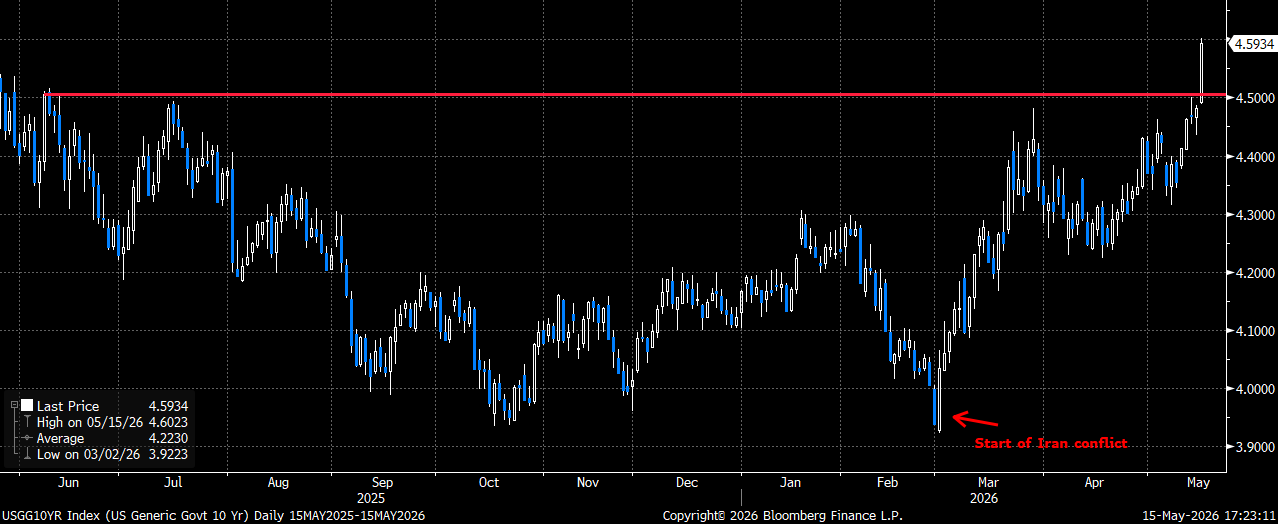
Yields in the US continued their sharp climb last week, with the 10-year yield gapping above the 4.5% threshold on Friday to close the week at just below 4.6%. The 10-year yield was below 4% at the end of February and has moved decidedly higher to coincide with the sharp rally in oil that started after the attack on Iran in late February. The equity markets thus far have done an incredible job of ignoring the sharp rise in yields (and oil), but at these levels in both it may be too much to bear should either move much higher from here.
10-year yields closed at their highest level in a year on Friday and have climbed by more than 65bps since the start of the war
The markets were clearly not happy with this latest surge in yields, as Friday was the worst day for all three of the major indices since the market bottomed out in late March. Given the massive rally we have seen of the March lows, it stands to reason that should we see higher rates and oil from here there could be more downside to come. While we have been very constructive on the markets for much of the rally since the end of March, we did start to suggest adding small-cap hedges last week (here). Given the action in the bond market on Friday, and the accompanying move lower in stocks, it appears the market has also reached its threshold for yields and oil.
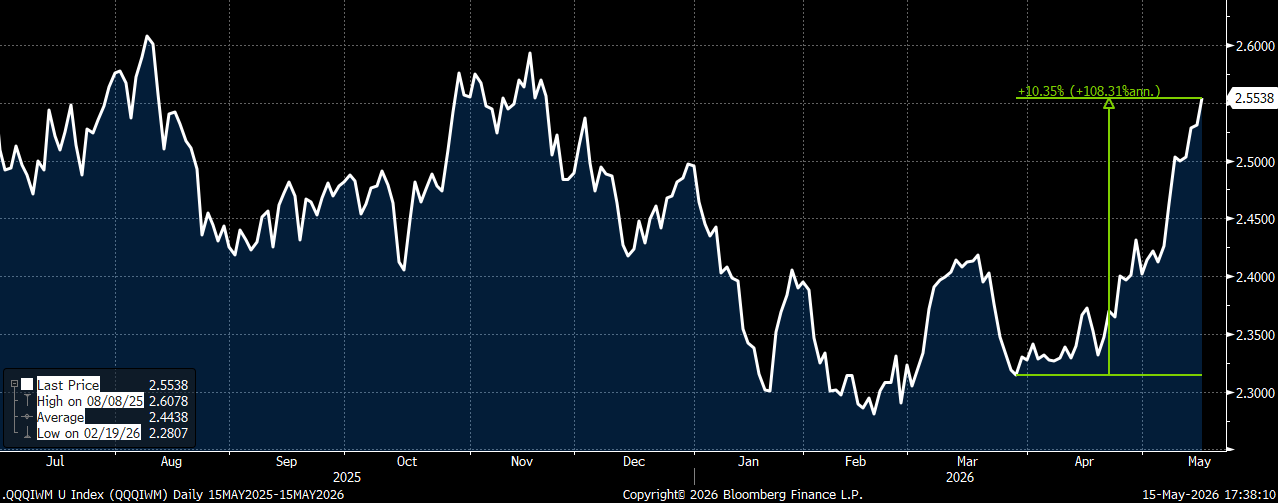
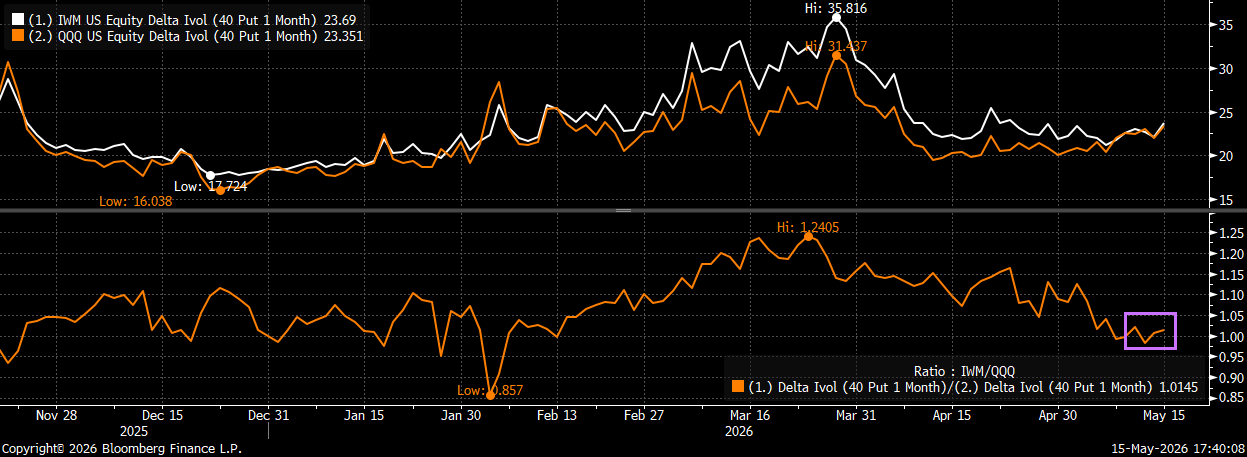
The action on Friday only reaffirmed why I believe small cap (IWM) hedges may be the preferred index hedge at this time. We saw IWM underperform SPY by a 2:1 margin, and even though the semis (SMH) were down nearly 4%, IWM still managed to underperform QQQ by a 1.6x to 1 margin. This underperformance to QQQ is even more impressive when you consider how much QQQ had already outperformed IWM off the March lows, as well as the fact that QQQ and IWM 1-month (June) 40-delta put vols are essentially the same (IWM puts are “cheap” to QQQ on a historical basis)
QQQ/IWM relative spread is up more than 10% from the March lows and shows no signs of stopping
IWM 1-month (June) 40-delta put vol is the same as QQQ 1-month 40-delta put vol (which is on the low-end of the 6-month skew)
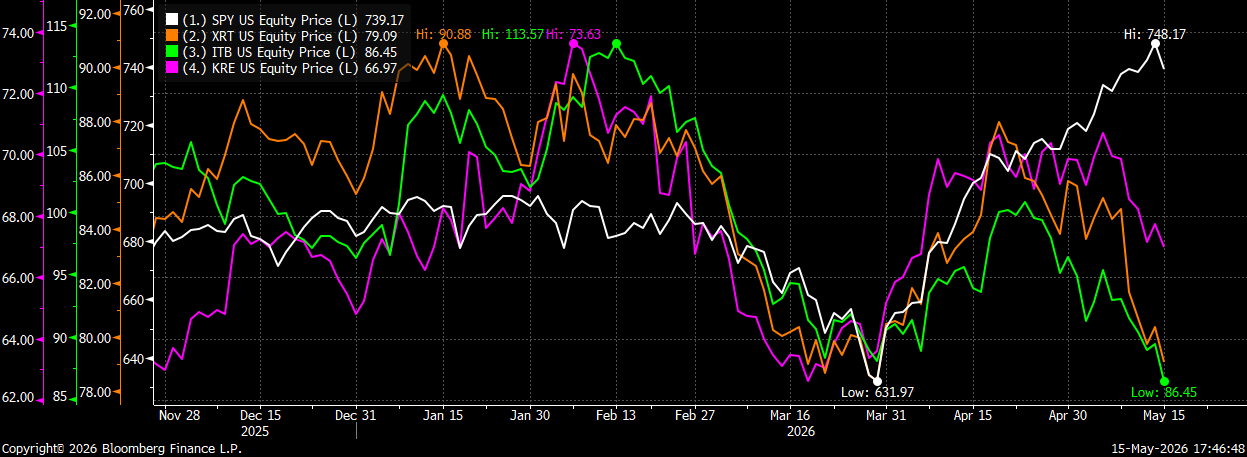
Why I also believe IWM can continue to underperform both QQQ and SPY on a move lower in the markets is that it has a larger weighting in sectors that are more negatively impacted by higher yields (regional banks, retailers, housing stocks). Most of these sectors peaked weeks ago, but the strength in the tech/AI parts of the small cap index helped buoy IWM to new highs. If we see further weakness in the tech/AI trade (after a huge rally), and the rate-sensitive areas of the market continue to decline as yields rise further, then I believe we can see a more meaningful decline in IWM on both an absolute (and relative) basis.
Regional banks (KRE), retailers (XRT) and Homebuilders (ITB) all peaked in mid to late April even as SPY continued to make new highs
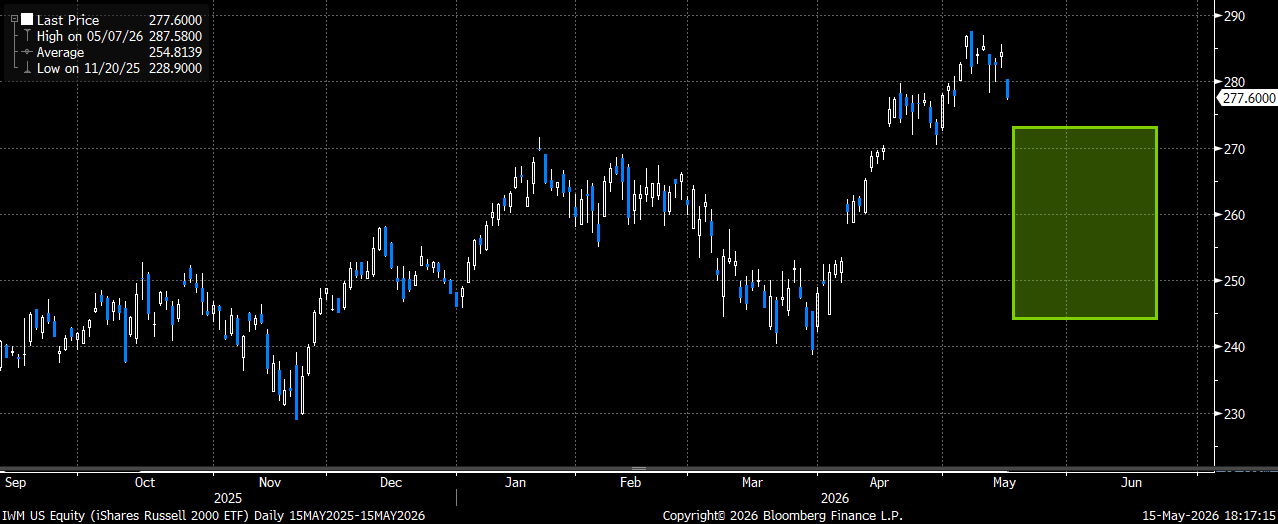
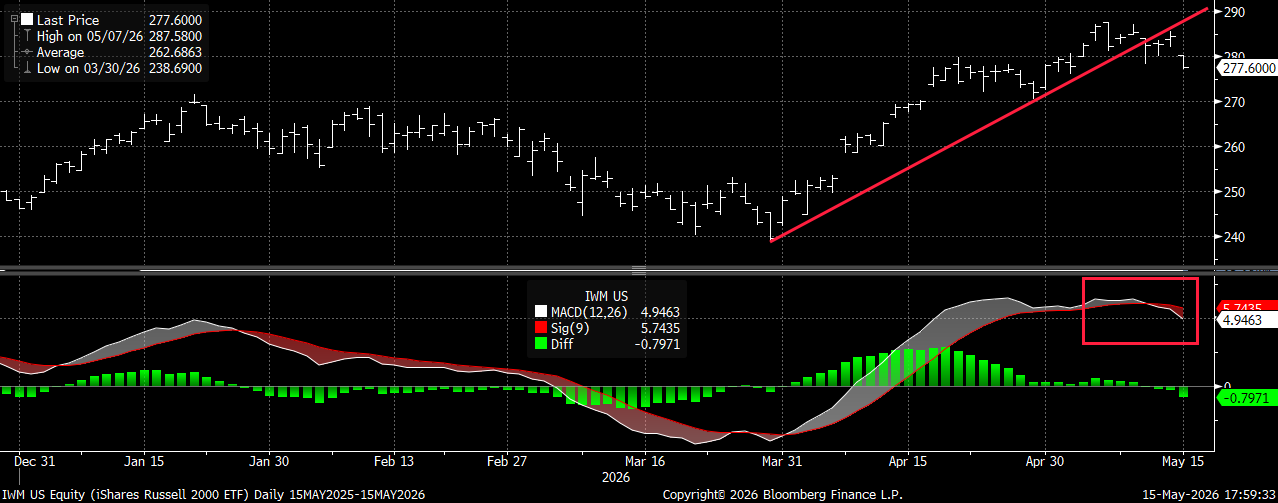
Even with the 2.4% decline on Friday, IWM is still only about 3.5% below the all-time highs that were hit in early May. In addition, with a 20.5% rally from the March lows to those May highs (even though both yields AND oil are higher) it stands to reason that we could absolutely see a larger decline/pullback. On a technical basis, the shorter-term setup for IWM appears to now be somewhat negative. Not only did IWM break below the March low uptrend support, but it also registered a “negative” MACD signal as well.
IWM with a clear break below short-term support, as well as a negative MACD signal (bottom)
While most of my hedging focus of late has been on low-cost “tail” hedges via VIX call spreads (a tail hedge trade I continue to favor), I believe now is the time to get more aggressive with index (IWM) protective hedges. I believe the biggest concerns for the market remain higher yields and higher oil, and if Friday was any indication, IWM remains the most attractive way to hedge that risk in equities in my opinion. With IWM down ~ $5 from the time the Portfolio Strategy team published my note on 5/13 recommending the June 18th 278/250 put spread for $5, I would just suggest moving the entire put spread down $5 when looking to establish new hedges now.
Trade:
Buy IWM June 18th 273/245 put spread for ~ $4.95 (IWM Fri close price ref of $277.60)
Trade Details:
- Buying the 10% wide June put spread that starts 1.6% below spot (IWM dropped by 2.4% on Fri)
- IWM continues to underperform both SPY and QQQ, and should be more negatively impacted by the two biggest concerns currently facing the market (higher yields and higher oil)
- Trade offers 4.7x to 1 max payoff at expiration
- Put spread is capped ~ 12% lower and just above the March lows
- IWM is only down 3.5% from the recent all-time highs, and is still ~ 16% above the lows hit at the end of March (keeping in mind that both yields and oil are now HIGHER than they were on that day)
- Please reach out to me or the 22V sales team for updated pricing and execution capabilities
The Green area shows where the June protective put spread targets should we see a continued pullback/decline after the sharp rally