Back AI Macro Nexus Research

Bubbles, Parabolas and Speed Crashes: The End of Human Market Structure

Published on May 10, 2026

Download the PDF Report

By

Jordi Visser

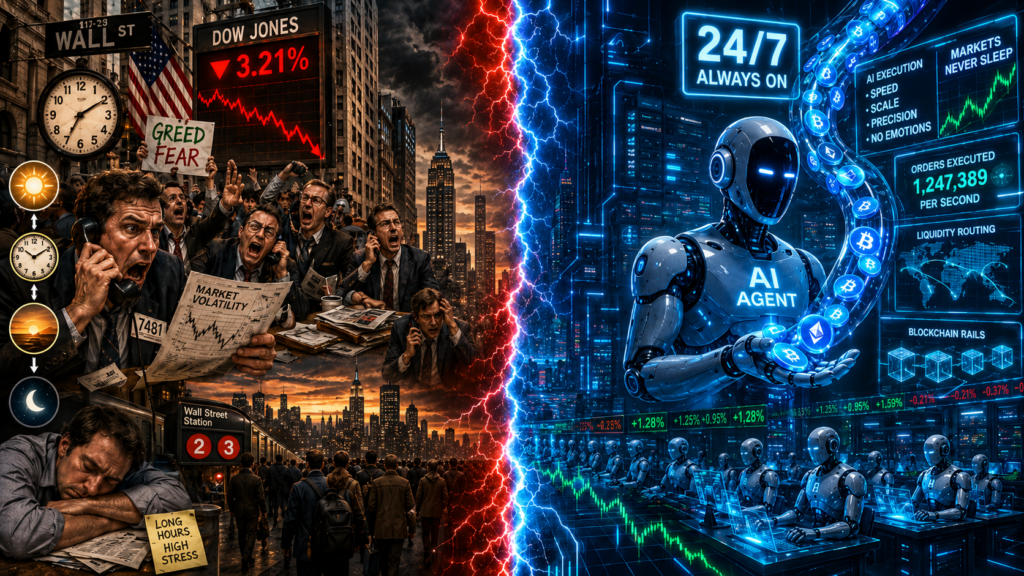
In this week’s video, I take on the “AI bubble” narrative head-on. Yes, charts have gone parabolic. Yes, the moves look uncomfortable. But this isn’t 1999, and it isn’t Kindleberger. The dominant force in markets is no longer human emotion, it’s AI agents that don’t anchor, don’t get FOMO, don’t remember Druckenmiller’s wisdom, and have one objective: make money. Markets are moving from “manias, panics, and crashes” to bubbles, parabolas, and speed crashes, faster up, faster down, and structurally different.

The facts cut against the bubble call. S&P earnings growth is running 27.1% Y/Y with 20% average earnings surprises across 320 reporters. Semi sales were +88% Y/Y in March. Anthropic is projected to surpass Alphabet in revenue by mid-2028, they planned for 10x annualized growth this year and got 80x in Q1. Cloud backlog is $1.3–1.4 trillion. The market’s PEG ratio is 1.03. Nvidia’s PE is at its lowest of the decade, versus Cisco’s 130 at the 2000 peak. This isn’t speculation, it’s a benchmark arbitrage. Passive money is structurally underweight the names doing the work, and they have to catch up. That rotation just started in late November when the agentic stage kicked off and Open Claude went viral.

The bottleneck has now shifted. The IQ stage was GPUs. The agentic stage is power-constrained. Tokens are the food of digital employees, and tokens are power plus chips. That forces capital into utilities, grid equipment, batteries, silver, copper, and advanced packaging. I’ve sold two-thirds of my Micron and rotated into Nvidia, silver, Bitcoin, and Ethereum, with Vistra likely next. We’re entering late cycle, bottlenecks, inflation, CPI tracking 3.7%, three-month bills heading below CPI for the first time since 2022. That’s the regime where Bitcoin and silver become core allocations, not satellites.

Timestamps

  • (00:00–02:30) Setup: Why the bubble narrative misses the point. Calling out the same crowd that was wrong on tariffs, oil, Bitcoin, and passive and now wrong on AI. Framing for why Kindleberger no longer applies.
  • (02:30–08:00) Manias, Panics & Crashes is over: Markets used to be human-dominated with information lags. Today, AI agents dominate flow and have no emotion, no anchoring, no memory. Druckenmiller’s 2000 FOMO story illustrates exactly the human bias the bubble-callers are anchored to.
  • (08:00–13:30) Open Claude & the agentic stage: November marked the shift from the IQ stage (GPUs) to the agentic stage. Token consumption is set to grow 15–50x. Benchmark arbitrage means passive funds are forced buyers of AI names and it just started.
  • (13:30–19:30) Demand reality: Greg Brockman says demand for intelligence is effectively unlimited. Anthropic planned for 10x growth this year, got 80x in Q1. Cloud backlog $1.3–1.4 trillion. Earnings +27.1% Y/Y. Semis +88% Y/Y in March. Unlike dot-com, the revenues are real.
  • (19:30–23:30) Valuation: Market PEG is 1.03. Nvidia’s PE is at its lowest of the decade. Cisco’s PE was 130 at the 2000 peak. The S&P PE correlates with consumer confidence and confidence is low, not euphoric. This is not 1999.
  • (23:30–29:30) Tokens = power + chips: Goldman, Morgan Stanley, and BlackRock’s Tony Kim all confirm the capex inflection. $8 trillion of combined market cap added by compute and model layers; $1.2 trillion lost by service apps that make up two-thirds of GDP. That is the benchmark arbitrage in action.
  • (29:30–35:00) Bifurcated economy: Breadth is weak, 47 stocks within 2% of 52-week highs, 31 in AI-sensitive groups. Information and financial activities jobs are negative again, AI knowledge-work disruption is showing up. Trade, transportation, manufacturing turning positive on the PMI side.
  • (35:00–42:00) PMI regime shift: March logistics index at 69.9, fastest expansion since March 2022. John Roque’s “frozen rope” charts cluster around power, copper, grid, utilities, transportation, capital goods, agriculture. Oil shortages building. Food inflation coming via fertilizer.
  • (42:00–50:00) Late cycle & thematic rebalancing: New subscriber tools, technical, fundamental (PEG), and exhaustion sheets. Sold two-thirds of Micron after extreme exhaustion readings. Power basket breakouts: Hon Hai, Vistra, Eaton, Fluence, Sterling Infrastructure. Advanced packaging, ABB electrification, Soitec.
  • (50:00–1:00:35) Silver, Bitcoin & tokenization: CPI forecast 3.7%, three-month bills heading below CPI for the first time since the 2022 inflation period. Negative real yields = Bitcoin tailwind. Bitcoin ETF outstanding shares at new highs as boomers allocate. Tokenization rollout scheduled for July 26. Speaking at the III Fort Lauderdale event May 13–15 on tokenization.

Watch here

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.