

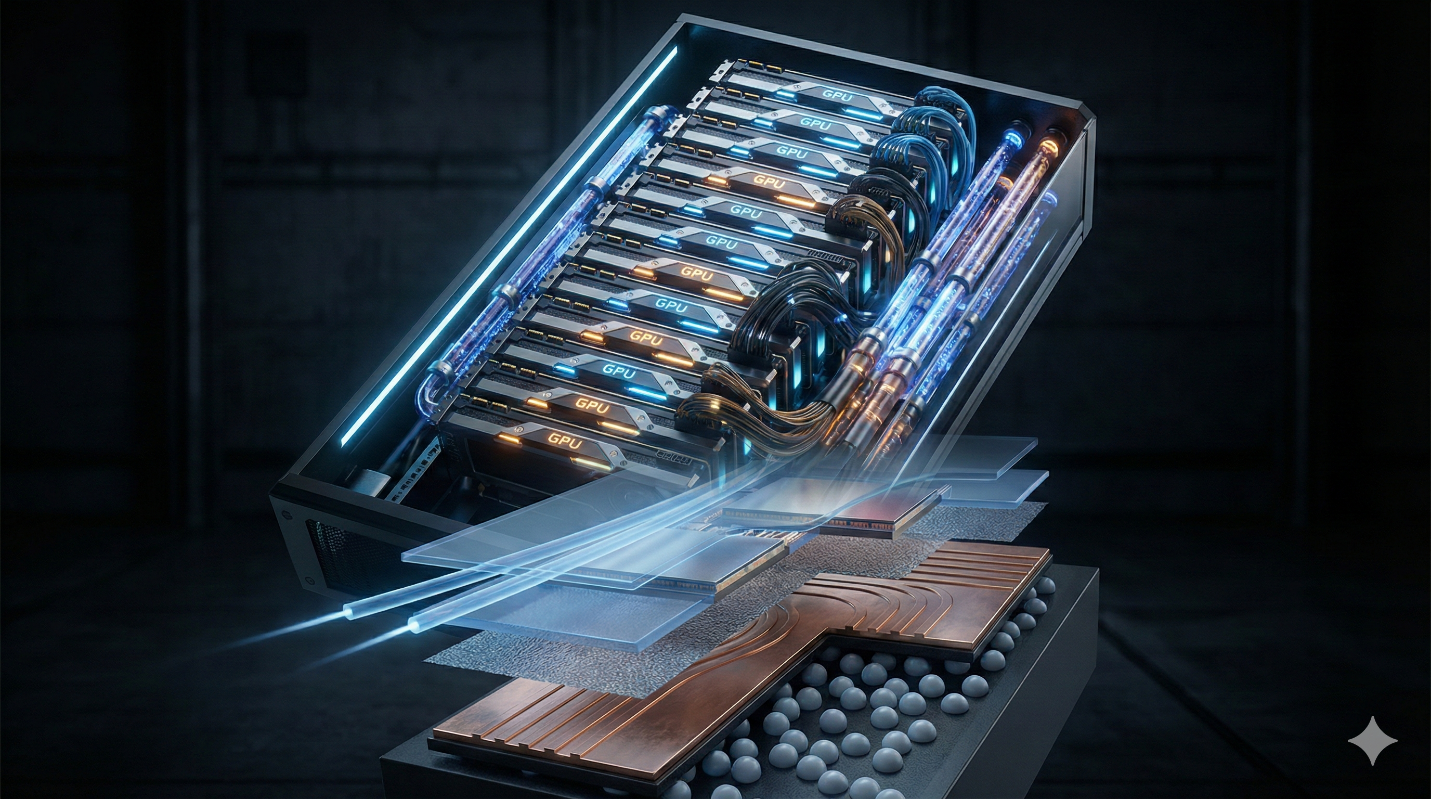
The artificial intelligence infrastructure trade is fundamentally broadening. For the past three years, the market’s focus has been fixated on the logical layer of the AI buildout, silicon architectures, algorithms, and data-center power. However, as models scale to unprecedented sizes, the physical constraints of generating, moving, and cooling gigawatts of compute are forcing a structural shift. The binding constraints are migrating into the physical layer: materials science, molecular engineering, and specialty chemistry.
The next decade of AI infrastructure will be gated not just by the volume of GPUs, but by the performance of the polymers and specialty materials that allow those GPUs to operate at higher density without melting, warping, or losing signal integrity. And that’s where the next scarcity shows up: in the industrial supply chains that expand with manufacturing cycles, the “PMI-sensitive” chemical and materials complex, not just in chip foundries. The Physical World Upgrade continues.
The Trigger: The Phase Transition from Bits to Atoms
The clearest signal that the AI infrastructure buildout has crossed this phase boundary occurred on January 27, 2026. Meta Platforms announced a multi-year agreement worth up to $6 billion with Corning to supply optical fiber for its AI data centers. This deal, which drove Corning’s stock up 16% in its best single-day performance in two decades, is funding a massive expansion at a North Carolina facility that will become the largest fiber-optic cable plant in the United States.
While the market priced the optical fiber needs, it systematically underweighted the molecular supply chain that makes that fiber functional. Fiber optic cable is a complex glass-polymer composite system. It relies on UV-cured acrylate coatings, Low Smoke Zero Halogen polymer jackets, and precision adhesives. Corning’s CEO Wendell Weeks highlighted the core physics driving this: moving photons requires five to twenty times less power than moving electrons. As Meta prepares to deploy 8 million miles of fiber in its Louisiana Hyperion data center alone, the reality becomes clear: every mile of fiber deployed is a mile of advanced polymers deployed alongside it.
To put that scale into perspective, a typical Fiber-to-the-Home installation requires roughly 400 to 500 feet of fiber optic cable to connect a house to the street-level network. At that rate, the 8 million miles of fiber Meta is deploying in its Louisiana Hyperion data center alone would be enough to wire roughly 85 to 105 million individual homes, equivalent to connecting more than half of all the households in the United States. With this context, the reality becomes clear: every single one of those 8 million miles is a mile of advanced polymer coatings, adhesives, and jackets deployed alongside it.
The Three Walls of AI Infrastructure
Three structural forces have converged to make the late 2020s and 2030s the “golden age” for semiconductor and infrastructure chemistry.
1. The Thermal Wall
NVIDIA’s transition from the Blackwell architecture (exceeding 1,000 watts per package) to the Rubin platform (targeting 1,500W+) has pushed rack densities from a traditional 40kW to over 120kW. At these power densities, traditional air cooling fails physically, as the volume of air required generates destructive acoustics and vibrations.
- The Polymer Solution: The thermal stack is being entirely rebuilt. Traditional silicone greases physically pump out of the interface gap under extreme thermal cycling, causing catastrophic chip failure. The industry is rapidly adopting advanced Thermal Interface Materials, including Phase Change Materials, liquid metal compounds, and carbon-fiber aligned pads.
- Liquid Cooling Compatibility: As data centers adopt liquid and immersion cooling, every wetted material, from seals and O-rings to hoses and adhesives, must be validated for chemical compatibility to prevent dissolution or embrittlement.
2. The Interconnect Wall
Data rates are scaling to 1.6 Terabits and 3.2 Terabits per port, pushing copper interconnects against hard physical limits. At speeds of 200G+ per lane, the effective reach of copper shrinks to mere inches due to signal loss.
- The Polymer Solution: The industry is executing a wholesale replacement of copper with optics. Beyond cables, this requires co-packaged optics (CPO) and polymer waveguides made from fluorinated polyimides or siloxanes. These materials must route light directly on the processor package while surviving 260°C reflow soldering temperatures without deforming.
3. The Packaging Wall
To bypass the “reticle limit” (the maximum size of a single chip), manufacturers are stitching multiple chiplets together using 2.5D and 3D packaging architectures.
- The Polymer Solution: A critical physics problem emerges during manufacturing: silicon expands at roughly 2.6 ppm/°C, while organic substrates expand much faster at 15-17 ppm/°C. Heating causes the package to warp, delaminate, or break solder connections. The solution relies on advanced Epoxy Molding Compounds (EMCs) and underfills loaded with precisely calibrated spherical silica to match silicon’s thermal expansion. These highly engineered polymers act as the mechanical glue locking the geometry of $30,000 GPUs, making them single points of failure.
The Four Domains of the Polymer Opportunity
The chemical value capture in AI infrastructure spans four distinct growth vectors over the next decade.
Domain 1: AI Compute (The Brain)
Advanced semiconductor packaging materials represent the most mature and highest-moat domain. Every high-bandwidth memory (HBM) stack and chiplet package requires precise encapsulants.
- The transition to 2.5D/3D stacking increases material intensity per package by 3-5x.
- The global advanced semiconductor packaging materials market is forecast to double from $41.55 billion in 2025 to $83.35 billion by 2034, expanding at an 8% CAGR.
- Sub-segments like high-moat underfill adhesives ($350-500M market) and EMCs ($2.2-2.5B market) are heavily dominated by Japanese oligopolists controlling over 70% of the premium market.
Domain 2: AI Connectivity (The Nervous System)
The shift from copper to optics relies on photonics-grade adhesives, polymer waveguides, and specialized cable jacketing.
- The silicon photonics market is projected to soar from $2.2 billion in 2024 to between $9.7 and $13 billion by 2030 (a 25-30% CAGR).
- Corning’s enterprise optical communications business grew 61% year-over-year in 2025, validating this immediate, multi-year demand.
Domain 3: AI Thermal Management (The Circulatory System)
As GPU power spikes, the TIM and immersion fluid markets are rapidly expanding.
- The global TIM market is forecast to reach $5.6 to $11 billion by 2029-2033.
- The AI-specific premium segment (materials capable of handling >1,000W) is growing at a 15%+ CAGR. Recent industry trends show an architectural shift toward unified “TIM1.5” layers that eliminate interfaces and collapse the thermal path length, unlocking massive margin expansion for formulators.
Domain 4: Edge AI (The Body)
As AI scales out of the data center and into the physical world via humanoid robotics, drones, and autonomous vehicles, material requirements will multiply.
- The global humanoid robotics market is projected to hit $38 billion by 2035.
- With an estimated $150-$250 in polymer material content per robotic unit (potting compounds, structural adhesives, conformal coatings), edge AI represents the longest-duration growth vector for specialty chemicals.
Where Value Accrues: The Choke Point
The AI materials value chain is shaped like an hourglass. At the top, broad chemical majors provide commodity resins at thin margins. At the bottom, hyperscalers and foundries integrate the materials. The immense value capture happens at the narrow choke point: the specialty formulators.
Companies like Shin-Etsu Chemical, Sumitomo Bakelite, and Henkel synthesize proprietary molecules and hold deep qualification relationships with fabs. Because a single kilogram of qualified semiconductor-grade underfill prevents a $30,000 GPU from failing, these formulators enjoy immense pricing power.
- Gross Margins: High-end electronic materials command 40-60% margins, compared to 10-15% for commodity chemicals.
- The Qualification Flywheel: Qualifying a new packaging material takes 18-24 months per fab. Once approved, materials are locked in under strict “Copy Exact” protocols for the product’s lifecycle, creating exceptional revenue visibility and prohibitive switching costs.
Second-Order Catalysts Shaping the Decade
Three secondary dynamics will further accelerate the chemical industry’s integration into AI infrastructure over the next ten years:
- The Reshoring of Chemical Formulation: As the US and EU onshore semiconductor manufacturing via CHIPS Acts, chemical supply chains must follow. Transporting hazardous precursor chemicals is risky and costly. The Meta-Corning deal’s focus on North Carolina manufacturing serves as a template for localized, regional formulation buildouts.
- The Reformulation Supercycle: Pending US and EU regulations targeting PFAS (“forever chemicals”) create a massive catalyst. Fluoropolymers are heavily used in coolants, low-friction coatings, and wire insulation. A restriction forces the requalification of the entire liquid cooling and cabling stack, actively benefiting companies with pre-qualified, PFAS-free alternatives.
- Materials Informatics: AI is now being used to accelerate materials discovery itself, potentially compressing polymer formulation cycle times from 5 years to 1 year. This disproportionately favors large incumbents with massive data lakes, likely driving further industry consolidation and widening the moats of top players.
Key Risks to the Theme
While the structural tailwinds are robust, the chemical expansion relies on several dependencies:
- Capex Cycles: Electronic materials are highly cyclical; an AI capex slowdown directly hits material orders.
- Technological Disruption: The shift to hybrid bonding (copper-to-copper) eliminates the need for some traditional capillary underfills, though it shifts value to ultra-precise dielectric bonding polymers.
- Diluted Exposure: For many diversified chemical giants, AI-specific electronic materials represent less than 15% of total revenue, diluting the pure-play investment narrative. A broader PMI cycle involving what Jensen Huang has called a 90 trillion dollar build over the next decade is needed to hit all revenue lines.
Conclusion: Pricing the Chemistry
The AI infrastructure buildout has irrevocably shifted from a silicon story to a materials story. Hyperscaler investments, highlighted by Meta’s $6 billion commitment to glass and polymer composite fiber, prove that the logical layers of AI cannot scale without fundamental upgrades to the physical substrates.
The companies formulating the epoxies that bind chiplets, the TIMs that cool gigawatt racks, and the protective jackets that wrap millions of miles of optical fiber represent the ultimate “picks and shovels” trade of the next decade. The market has heavily priced the chips, the networking, and the power. It has not yet priced the chemistry.

