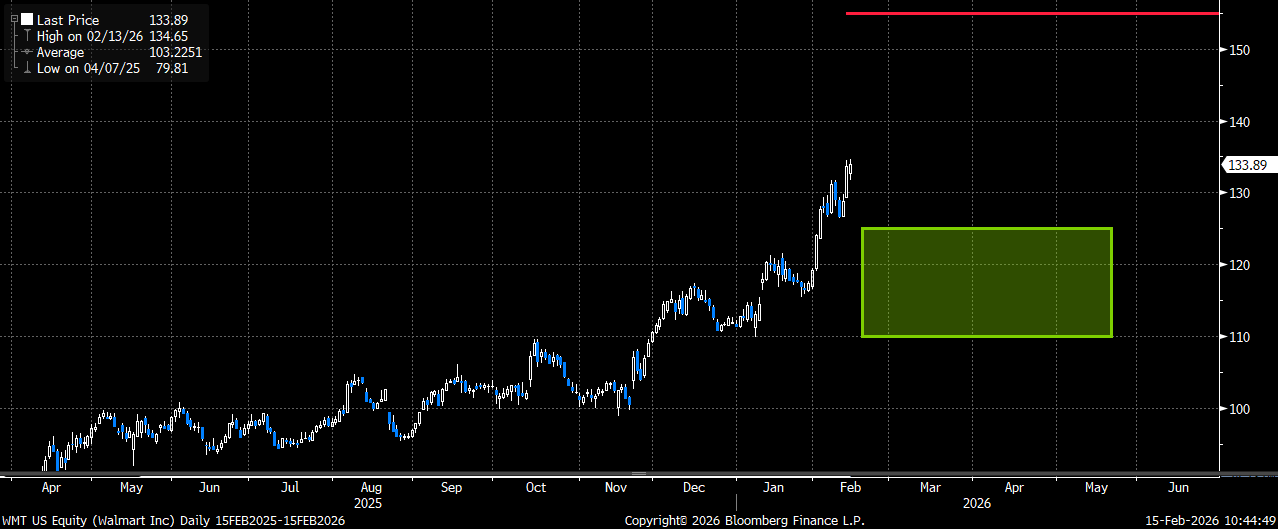
Walmart (WMT) reports their next earnings on Thursday morning before the open. The stock has become the poster child for the rotational trade out of the crowded Mag7 names into the more “defensive” parts of the market as of late. That being said, the sharp move higher in a company this large and established seems very unsustainable. Perhaps when they report earnings this week that may throw some cold water on this upside momentum? To put this move into some perspective, WMT has added ~ 200bln in market cap in just the last five weeks. In other words, they added FOUR Targets (TGT) or a McDonald’s (MCD).
Here are some more numbers from this recent move higher in WMT that should support either collaring a long equity position or at a minimum selling “expensive” upside covered calls:
1) Shares are up 35% from their November lows

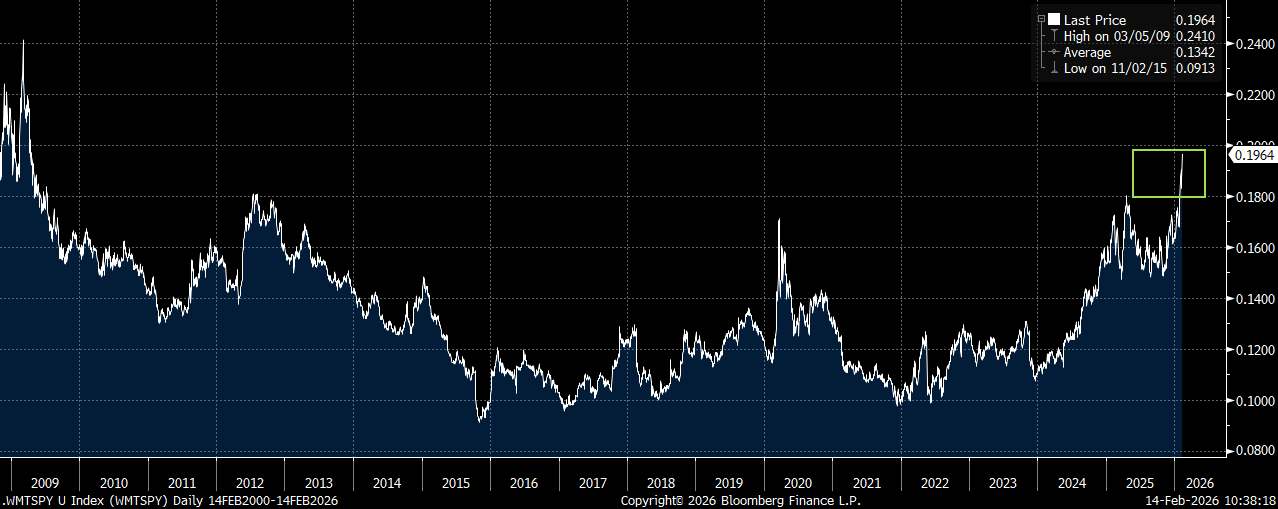
2) WMT/SPY relative spread is up 32% from the November lows and at a 17-year high (now at levels that last occurred after the GFC)
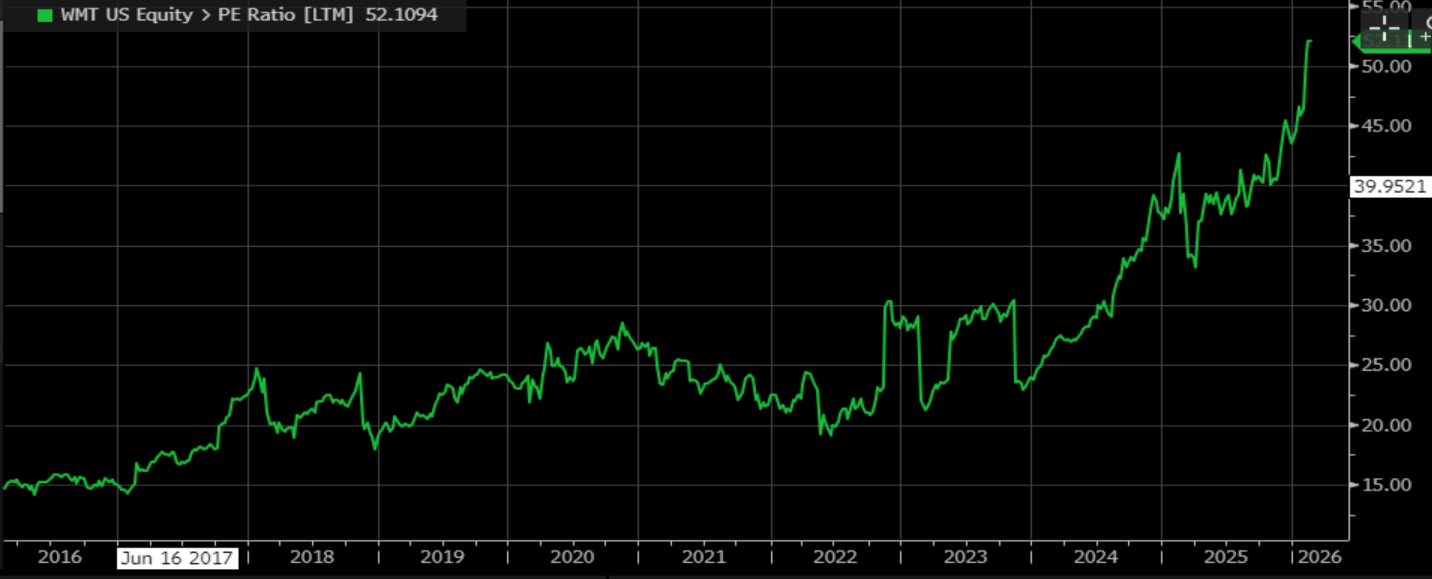
3) WMT P/E is now OVER 50x (it was under 20x as recently as 2022 and was closer to 15x back in 2016-2017)
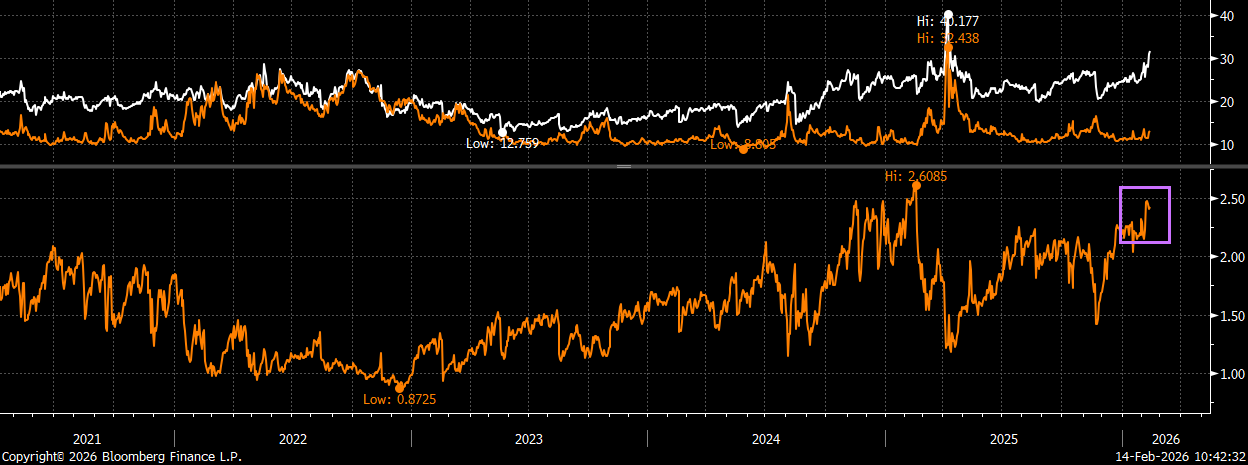
4) WMT 10% upside 3-month call implied vol is OVER 31, and more than double where it traded 2 years ago
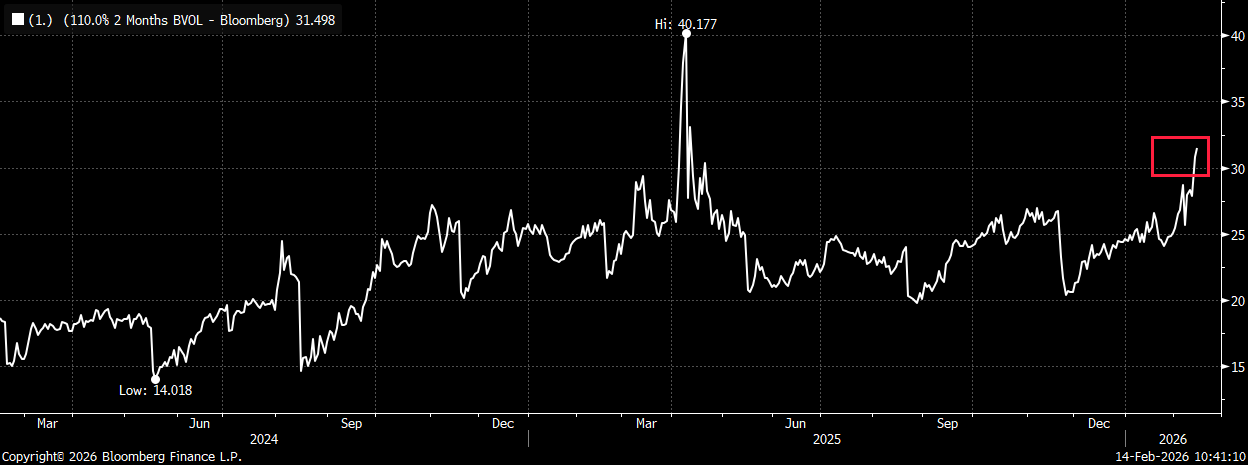
5) WMT 10% upside 2-month call implied vol trading just below the highest levels to 5% 2-month SPY call implied vol
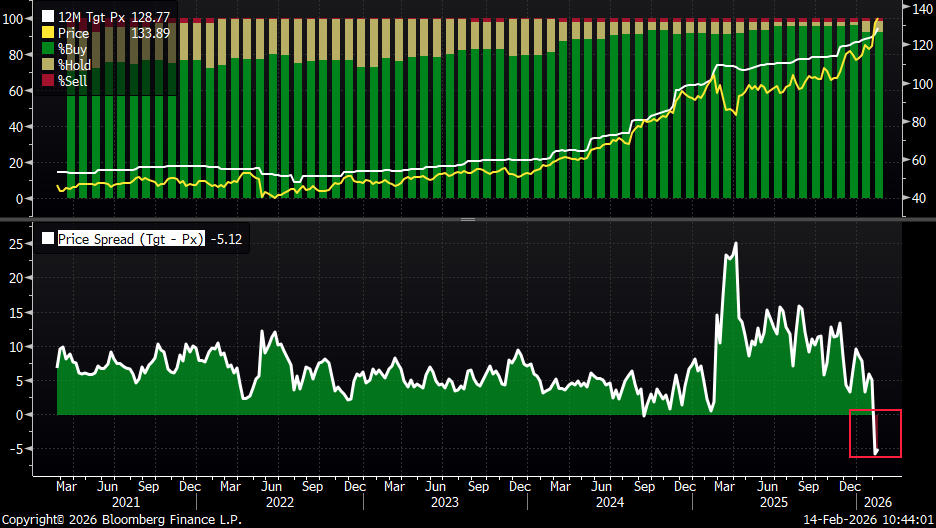
6) WMT is trading above the street’s average 12-month PT of 128.77. This is the ONLY time in the last 5 years where WMT has traded above the street’s current 12-month PT
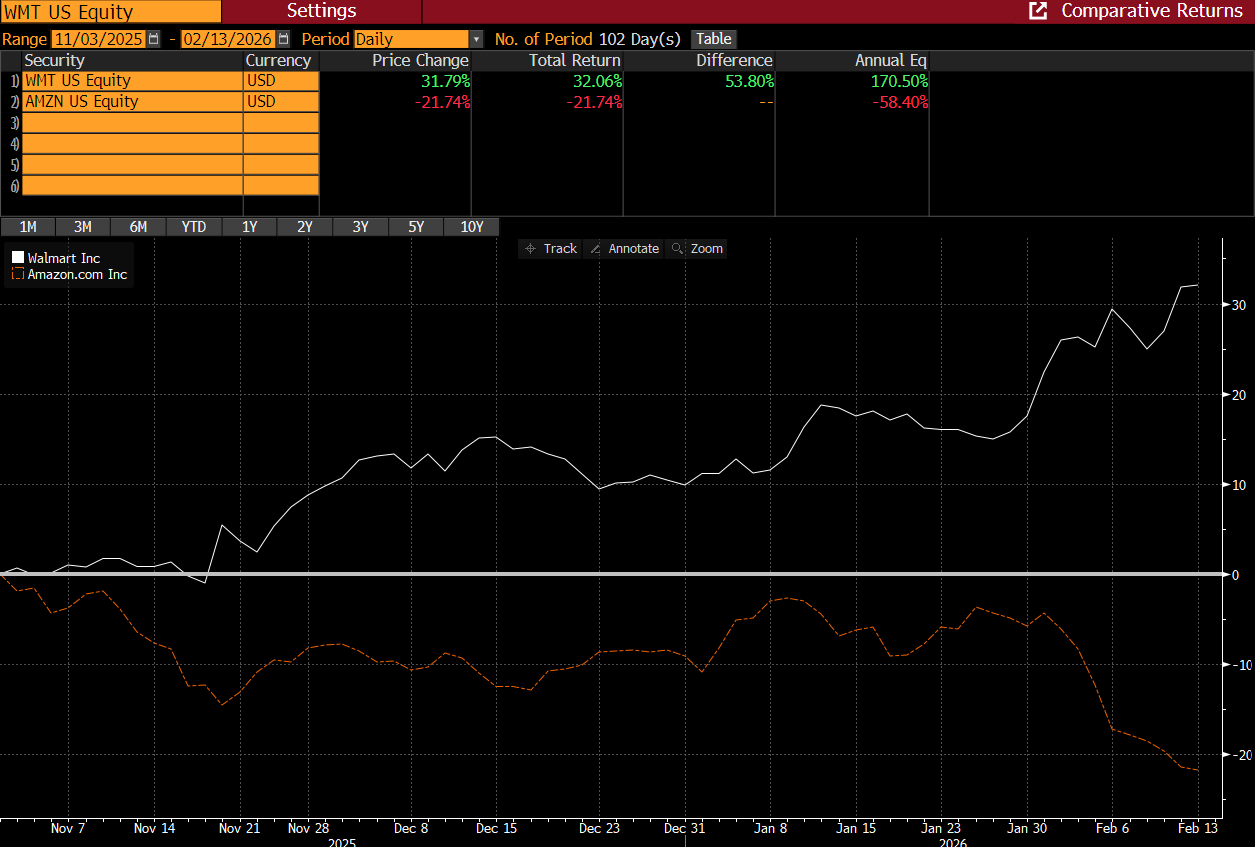
7) Since early November WMT is up 32% and AMZN is down 22%
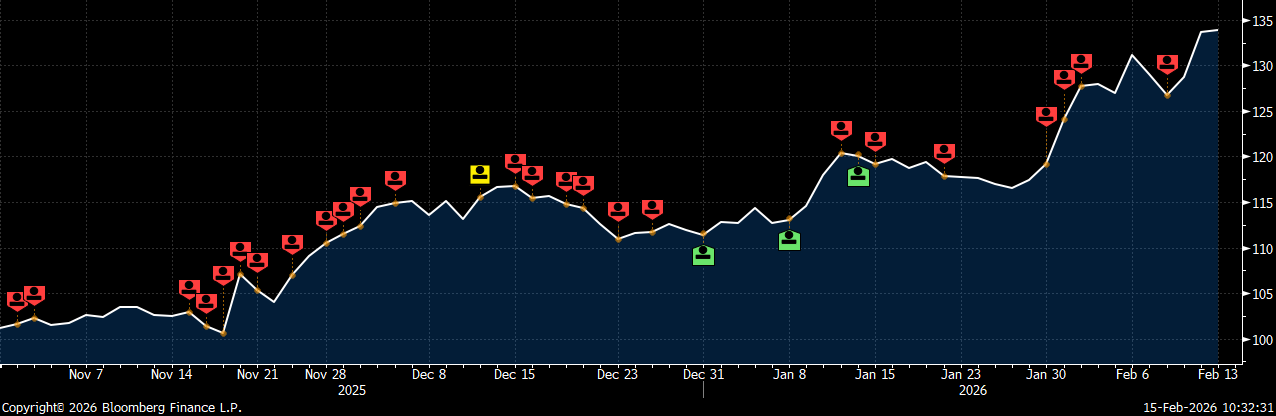
8) Insider sales outnumbered insider buys by a 25 to 3 ratio since the start of November
If long shares of WMT, I believe now is the time to consider either selling “expensive” upside calls and/or collaring part (or all) of the position. Here are two trades I suggest at this time:
Trade #1 – Sell upside covered calls
Sell WMT April $145 calls $3 or better (WMT 133.89 Fri closing price ref)
Trade Details:
- Selling the 8.3% upside April calls in WMT after an extremely large move higher on both an absolute and relative (to SPX) basis
- Lofty valuation of over 50x is likely to come into play at some point, even if money continues to flow out of the Mag7 names into more “defensive” areas of the market
- Call sale yields 2.2% (12.8% annualized) and has an upside breakeven at 153 by April 17th expiry (14.3% higher from here)
- Great way to take advantage of large increase in upside call vol (as shares have risen) while naturally reducing long exposure at higher levels
- Can do trade against a portion of long WMT equity position
- Please reach out to me or the 22V sales team for updated pricing and execution capabilities
Trade #2 – Add low-cost May collars
Sell WMT May 155 calls
Buy WMT May 125/110 put spread
Costs ~ $1.25 (WMT 133.89 Fri closing price ref)
Trade Details:
- Selling the 16% upside May calls to buy the 15-point wide downside put spread that starts 6.6% lower
- Lofty valuation of over 50x is likely to come into play at some point, even if money continues to flow out of the Mag7 names into more “defensive” areas of the market
- May expiry should capture the next two earnings (either could be catalyst for profit-taking or weakness)
- Put spread is capped to the downside 18% lower and back at what should be support at the 110 level (Jan lows and former highs from October)
- Implied vol is very elevated, why I favor selling the upside call to buy the downside put spread
- Please reach out to me or the 22V sales team for updated pricing and execution capabilities