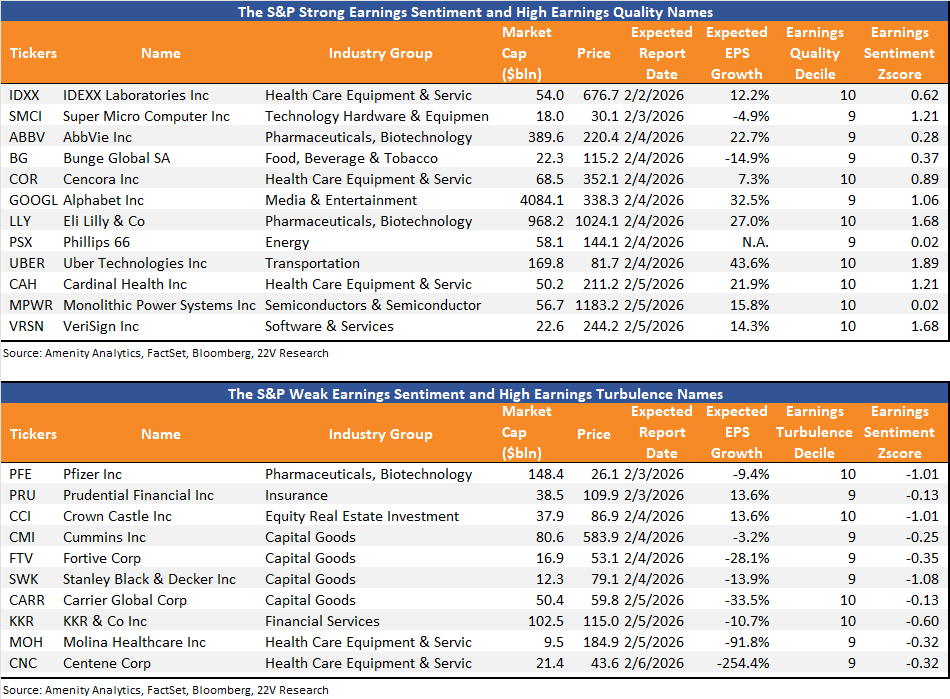
Next week will reach the peak for earnings with 129 S&P names reporting, we list the names with higher beat potential and miss risk at the end of the report.
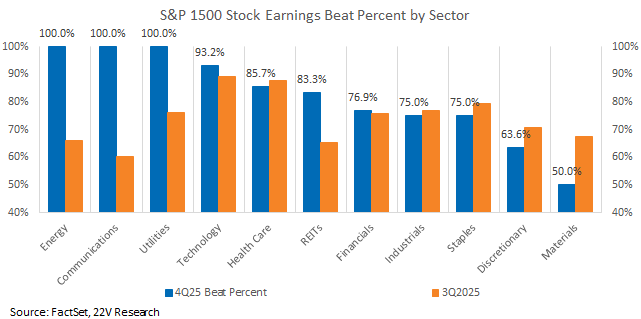
Based on currently reported S&P 1500 names, half the GICS sectors have beat rates better than last quarter and ALL sectors have beat rated above their long-term medians. Energy, Comms, and Utilities all have 100% beat rates.
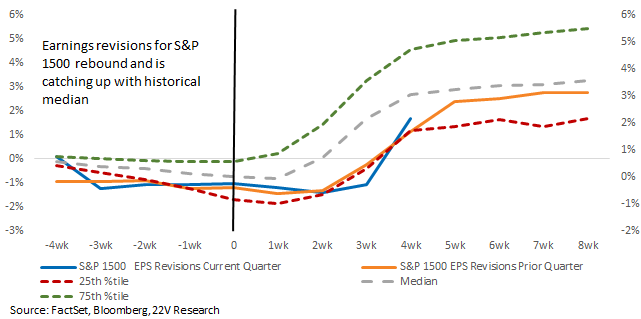
The bottom line is that fundamentals (sales, margins, EPS) all remain strong. Analyst consensus estimates for 4Q picked up, rising to +1.7%, just under the median level for the S&P 1500 at this point in reporting. Upward revisions were driven mostly by large caps, while mid cap estimates were roughly flat. Small cap growth remains the strongest at +3.7%. Strong fundamentals continue to support the broadening-out trade.
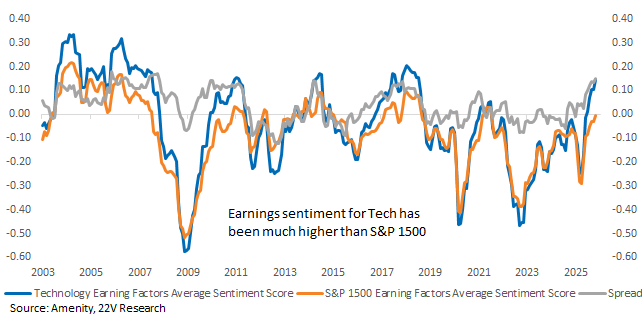
For now, earnings sentiment for Techn continues to improve and its spread with S&P 1500 earnings sentiment widened (96th percentile). That suggests the earnings outlook for Technology expressed by management continues to be better than that of the overall index even as broad sentiment moves higher. As a sector highly tied to the AI theme, strong earnings outlook helps alleviate some concern about capex and profitability.

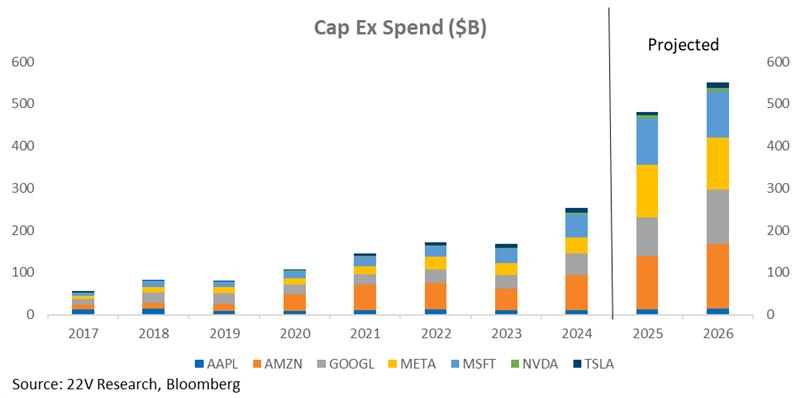
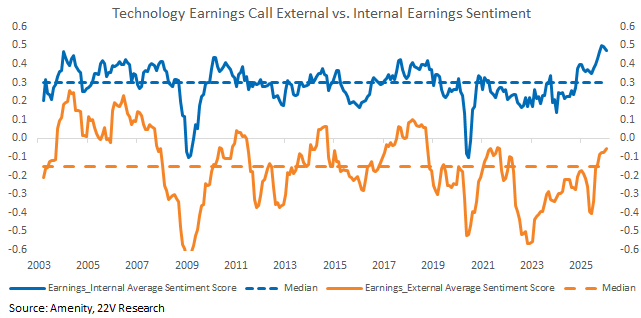
The AI theme remains an idiosyncratic driver and we are seeing more divergences within the theme. In aggregate, capex projections for the Mag 7 continue to grow, reaching $550bil for 2026. That is 120% above spending in 2024 and 15% above 2025 levels. Supporting the strong CAPEX trend is strong internal (company specific) and external (macro related) earnings sentiment. Management teams are signaling strong earnings trends.
Earnings Trends Strong While AI Outlook Grows More Mixed: Using currently reported S&P 1500 names, half the GICS sectors have beat ratios better than last quarter and ALL sectors have beat rated above their long-term medians. Energy, Comms, and Utilities all have 100% beat rates for now.
Analyst consensus estimates for 4Q picked up this week as well, rising to +1.7%, just under the median level for the S&P 1500 at this point in reporting. Upward revisions were driven mostly by large caps, while mid cap estimates were roughly flat. Small cap growth remains the strongest at +3.7%. Strong fundamentals continue to support the broadening out trade.
4 of the Mega 7 reported this week. Their earnings all beat estimates, but market reactions were mixed. Concerns about MSFT capex dragged the stock lower while META benefited from AI momentum. As we discussed (HERE), the AI theme remains an idiosyncratic driver and we are seeing more divergences within the theme. In aggregate, capex projections for the Mag 7 continue to grow, reaching $550bil for 2026. That is 120% above spending in 2024 and 15% above 2025 levels.
For now, earnings sentiment for Techn continues to improve and its spread with S&P 1500 earnings sentiment widened (96th percentile). That suggests the earnings outlook for Technology expressed by management continues to be better than that of the overall index even as broad sentiment moves higher. As a sector highly tied to the AI theme, strong earnings outlook helps alleviate some concern about capex and profitability.
On the other hand, the breakdown of earnings outlook sentiment shows External than internal readings. The implication being that company specific trends are weakening, AT THE MARGIN, while macro supports improve. Keep in mind, the level of both sentiment readings is very high, and internal sentiment could stabilize as more companies report. This is an at the margin point that does not change the trend. Management teams are signaling strong earnings trends. As we noted last week, within Tech sector, Hardware and Semis are expected to perform better than Software (HERE).
Week Ahead: Next week 129 S&P names are scheduled to report. Names with highest beat potential (strong Earnings Quality and positive earnings sentiment), and names with higher miss risk (high Earnings Turbulence and negative earnings sentiment) are listed below.