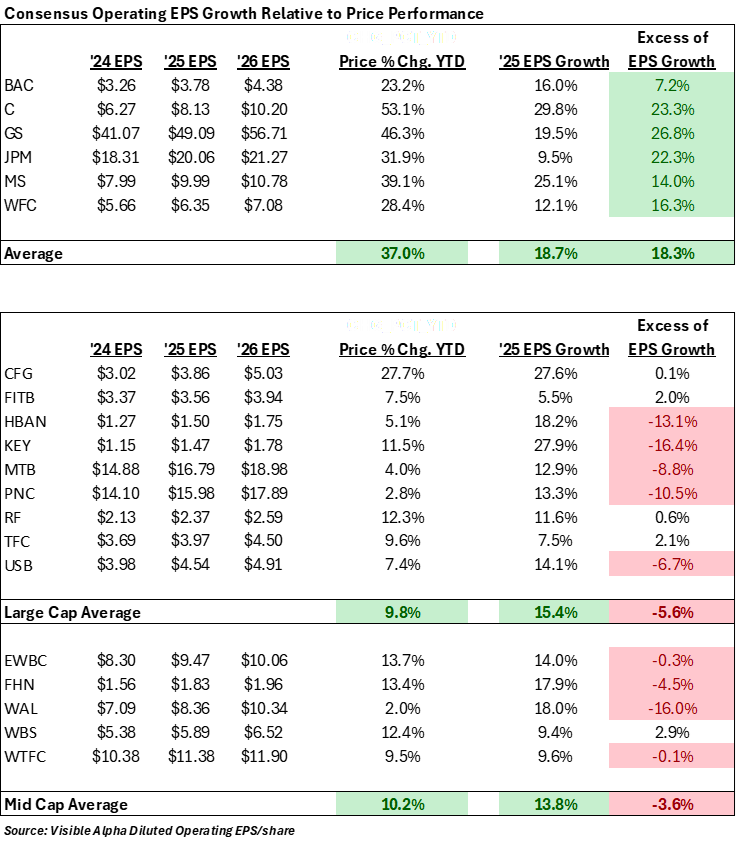
- We had also postulated that the mega cap universal banks and brokers could see some relative weakness given the market swoon/factor rotation from the growth/momentum trade. That has clearly not happened with the Big 6 (BAC, C, JPM, WFC, MS & GS) now up ~37% vs. 11/20’s ~26% return suggesting that they have very much kept up with their regional peers and continue to re-rate relative to the ~19% earnings growth. While the mega cap universals may very well continue to perform, we continue to be of the opinion that the regionals have more room to run into year end given the credit volatility that took the stocks off track in 3Q.
What do we expect from the conference next week?
- While we largely expect the banks to refrain from giving detailed ’26 guidance until the 4Q calls in January, we do think they will update the 4Q tracking and may leave at least a few breadcrumbs out to ’26.
- The recent round of rate cuts combined with the wrapping up of quantitative tightening should help alleviate any lingering deposit price pressure and we expect to hear the banks talk about a rational deposit pricing backdrop.
- In addition, we expect to hear a continued solid backdrop for investment banking continuing into 4Q.
- The real lynchpin will be credit. As we already saw at BAAB, the banks have given more disclosure on their NDFI portfolios and were largely upbeat on consumer credit (both card and auto). We would be surprised to see much change over the past 4 weeks.
Some names to focus on:
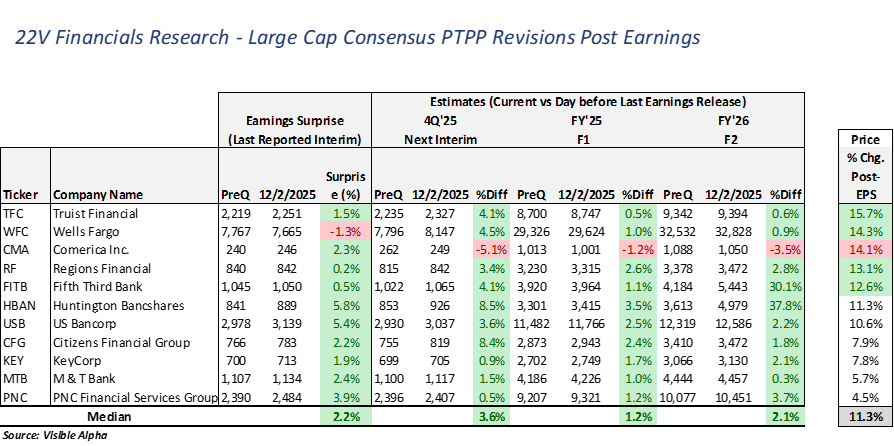
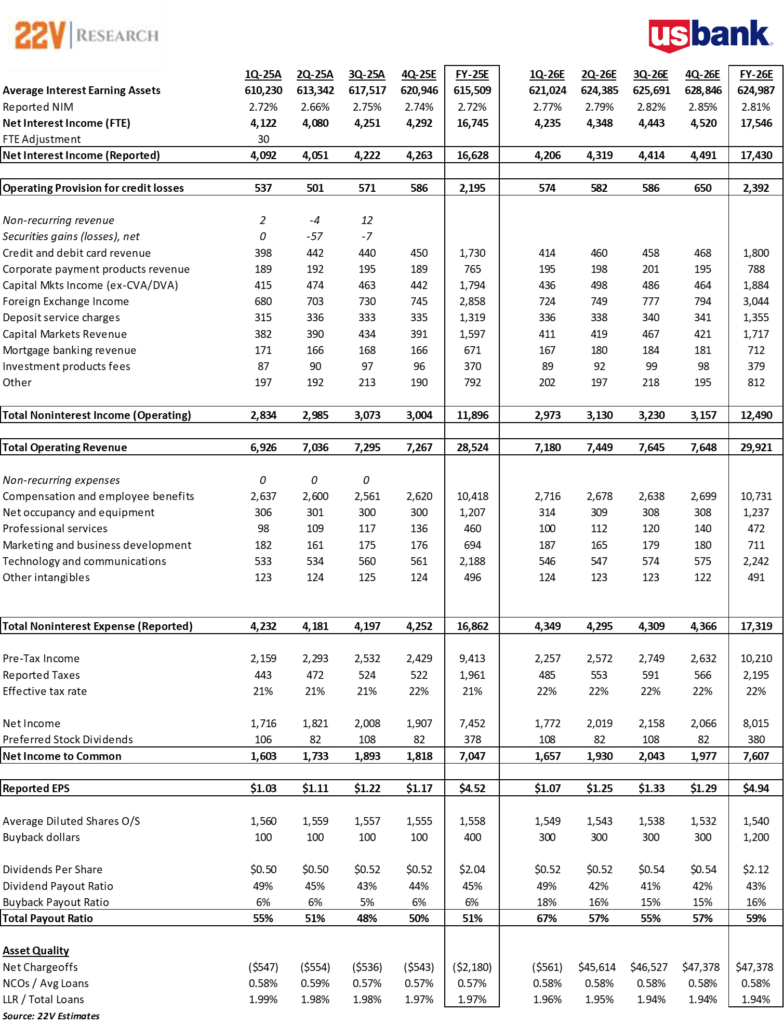
- US Bancorp (USB) – Upgrading from Sector Perform to Sector Outperform – In terms of 4Q, we think the update should be largely positive with the current NII guide of relatively stable having an upward bias to it. While not necessarily a surprise given their 3Q call commentary of “biased to the upside” to the stable 4Q NII guide, we do think USB will be a beneficiary of the recent Fed cuts (including one likely in Dec.). We have NII up 1% QoQ vs. the stable guide which puts us ahead of the Q by 0.3% on PTPP and our ’26 estimate is ~1% higher on PTPP. As a bit of background, when we look back to what ’25 was vs. what could have been for USB, we’d make a couple of observations.
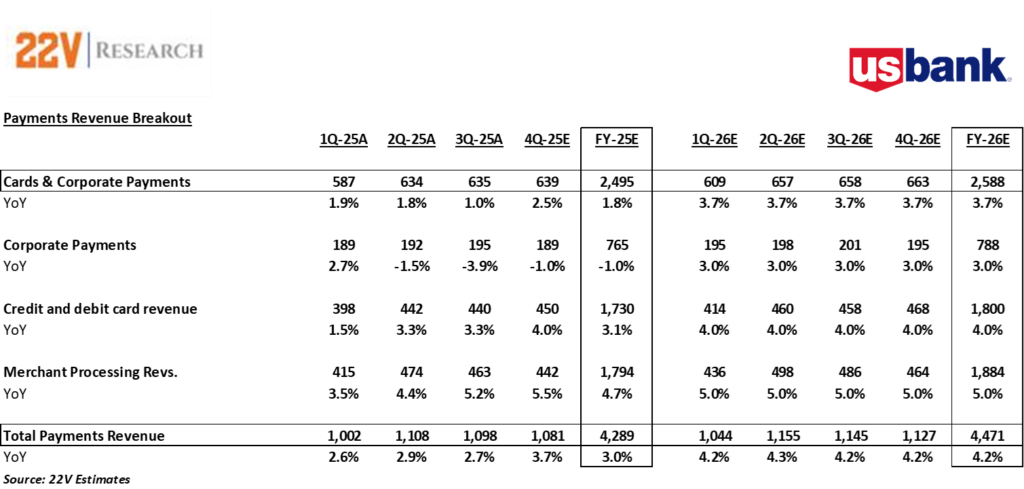
- Coming into ’25, USB was hoping for a more sustained rate cutting cycle and ideally a relatively stable macro environment vis a vis the payments side of the business. Instead, the rate cuts were back-end loaded, and the general economic disruption caused by the tariff policy to corporate T&E but also the government efficiency programs weighed on the corporate payments side of the business. USB was also dealing with the lingering effects of their pullback in pre-paid card right through 2Q’25 given their election to scale back in that area. In sum, not the environment USB would have hoped for at the beginning of the year, and one that weighed on NII and the payments growth rate for most of the year.
- Fast forward to today and we believe the script is starting to flip and would note the following key points as to why we think USB can be a good relative outperformer from here:
- The Fed has already cut twice in the last 45 days (and likely a 3rd time next week) which will help ease deposit costs for USB. In addition, USB is benefitting from fixed rate repricing to the tune of 2-3bps/Q.
- The prepaid headwind is behind them as of 2Q and the drag on the growth rate already began to diminish in 3Q which we expect to continue into 4Q.
- The corporate payments YoY comparison likely bottomed last Q at a (4%) and should begin improving from here.
- Merchant processing revenues are already comping above 5% YoY growth in this most recent Q. Important to point out that merchant processing is ~40% of the payments line such that the 5%+ growth helps pull the total payments growth rate towards mid-single digits.
- Higher gearing to fee income at 42% relative to peers. Should not only act as a stabilizer to the extent that NII runs into any volatility, but will also benefit from the upswing in payments revenue.
- Medium term (’27) ROA target of 1.15% -1.35%, high teens ROTCE, mid-high 50’s efficiency and ~3% NIM in ’27 do seem doable. While we do not have published ’27 estimates as of yet, a first pass indicates that those assumptions are broadly reasonable.
- In sum, we have total payments revenue improving from +3% this year to +4.2% next year all in, and total fee income +~5% in line w/USB’s mid-single digit guide for fees in the medium term.
- We mentioned the recent series of rate cuts benefitting deposit costs for USB and the industry broadly. In the case of USB, at a ~40% cumulative beta post Q3, we feel like we’re not stretching to get to a beta slightly below 44% at YE’26. Recall that USB has called out getting to ~50% through the cycle beta but similar to the rest of our coverage, we’ve been having rate cut “mini-cycles” like the cuts in ’24, and now the cluster of likely 3 in the back end of ’25 which makes assessing what the true “through the cycle” activity will look like a bit more difficult. Regardless, we believe that our assumptions look very reasonable on a go forward basis and leave room for potential upside.
- While the stock comes into the conference as a recent outperformer, we believe the story will likely be one of continuous improvement well beyond the current Q, particularly in the profitability metrics that will take place over the next 6-8 quarters making USB a good later cycle play within the space. We move our estimates up from $4.41/$4.79 in ‘25/’26 to $4.52/$4.94. We revise our target up to $55 from $49 or ~11x our ’26 estimate.
Other select names:
- KeyCorp (KEY): We would expect the focus to be on capital markets revenue post management’s commentary on their earnings call expecting capital markets revenue to be roughly in line with where it was in the year ago Q (~$221mm). Part and parcel will be any additional expense associated with any incremental revenue. The other topics investors will likely focus on were their comments at BAAB on buyback where they spoke about being comfortably above the buyback guide of $100mm (we’re at $150mm) and any further contemplated balance sheet actions. On a PTPP/share basis, we’re 1.6% ahead for 4Q and 0.7% ahead in ’26 which sets up well relative to peers. The other area of focus will likely be M&A where KEY has sent some conflicting messages. Our price target remains $20 as the glidepath to their mid-teens ROTCE/LT ROA ~1.2% will likely take into ’28 to achieve making further significant re-rate more difficult barring any further balance sheet restructuring.
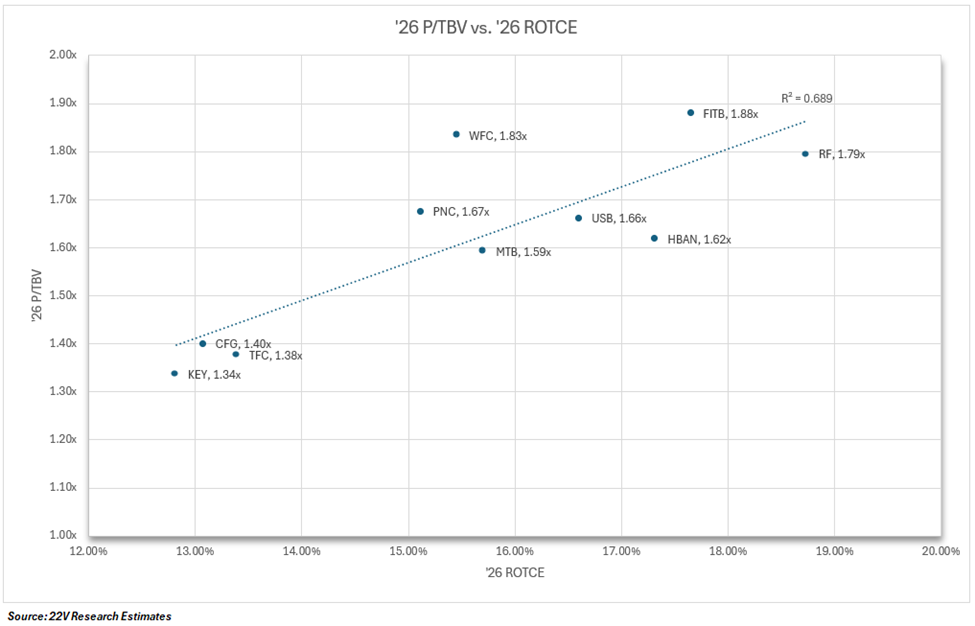
- Citizens (CFG): Like KEY, we expect the focus at CFG to be on the investment banking revenue which benefitted from the pull through in 3Q and which should continue to be solid in 4Q. While we’re a bit ahead for 4Q PTPP (+0.2%), we have a higher expense run-rate in ’26 with our PTPP estimate 0.4% below consensus. We believe the positives are well understood at CFG and are baked into consensus expectations. While eps will be up ~30% in ’26 due to less drag from swaps/private bank build out, we still have CFG shy of a 1% ROA at 0.95%. While CFG’s ROTCE does move up from ~11% this year to ~13% next, CFG still has a way to go before getting to the 16-18% medium term ROTCE guide suggesting that it has closed much of the recent valuation gap relative to our regression analysis (see chart below). As such we reiterate the sector perform rating and our $55 target or 11x our ’26 estimate.
- M&T (MTB) – Fee income strength has been the key driver of PTPP this year relative to NII thanks to a smaller balance sheet due to the attrition of the commercial real estate portfolio/loan sales. Management has highlighted that while production has picked up, maturities/payoffs have been elevated and have been a headwind all year. While that should abate in ’26, the degree and timing make it difficult to call a bottom in CRE attrition. We continue to struggle with consensus balance sheet assumptions which we still consider too high and the reason we’re ~ 1% below for PTPP in 4Q and full year ’26. That being said, if management was more definitive on calling a bottom in CRE attrition, we think it would go a long way towards helping sentiment for the stock. While this year arguably hasn’t been what M&T would have hoped when it comes to aggregate balance sheet size, their excellent fee income year, controlled expenses, substantial buyback and best in class tangible capital put M&T in the position to “make their own luck” if you will and could drive further PTPP/share growth whether it be more capital return or selective inorganic opportunities. Our price target is $209 or ~11x our ’26 estimate.
- Regions Financial (RF) – For Regions, we think the conference is less about this Q and more about setting up FY’26. As we’ve noted in the past, we’re modeling ~1.1% NII growth QoQ while the guide is 1-2%. We’ve been more focused on the 20% drop in the commercial criticized loan book and the remaining $300mm in non-core loan runoff which we think puts RF on solid footing going into ’26. On a PTPP/share basis, we’re essentially in-line for 4Q’25 and ’26. We continue to believe RF has further to rerate relative to their profitability metrics (see regression below). We reiterate the sector outperform and $29 target or ~11x’26.
- Truist (TFC) – Also a beneficiary of lower rates and sustained performance in the investment bank, we’re largely in-line with consensus for 4Q and 0.9% ahead for PTPP. Our NII estimate is +1.7% LQ relative to their guide of ~2% and consensus of 2.1%.
- “The M&A Group” (FITB, PNC & HBAN): While we would expect continued updates on merger progress, we’d note that HBAN while a median performer still appears to have room to re-rate relative to the regression below. PNC has languished post earnings as the worst performer we believe largely due to a lower NII starting point post 3Q than we would have assumed going into the Q and lacking a mean reversion catalyst as can be seen below.
Exhibits: