Back Portfolio Strategy

10yr Yields Biased Higher + We Like Being Long Discretionary Now

Published on November 26, 2025

∙ Download the PDF Report

By

Dennis DeBusschere

Brian Herlihy

Kevin Brocks

Sophia Wang

DAILY STRATEGY: With 10yr yields back to ~4% and high frequency data looking solid, being short 10yr bonds (long yields) is interesting now. A move higher in 10yr yields would be a headwind for high dividend paying stocks and the Low Vol factor in general.

The 10yr has had a tough time moving meaningfully below 4% even when concerns around the labor market were more intense. That is a result of nominal GDP growth consistently tracked 4.5%. Hard data or corporate commentary (banks, travel cos, and retailers this earnings season) and the recent stabilization of the labor market continues to support personal consumption. All else equal, 10yr yields have an upward bias. Especially if the Fed is easing lowers 2yr yields.

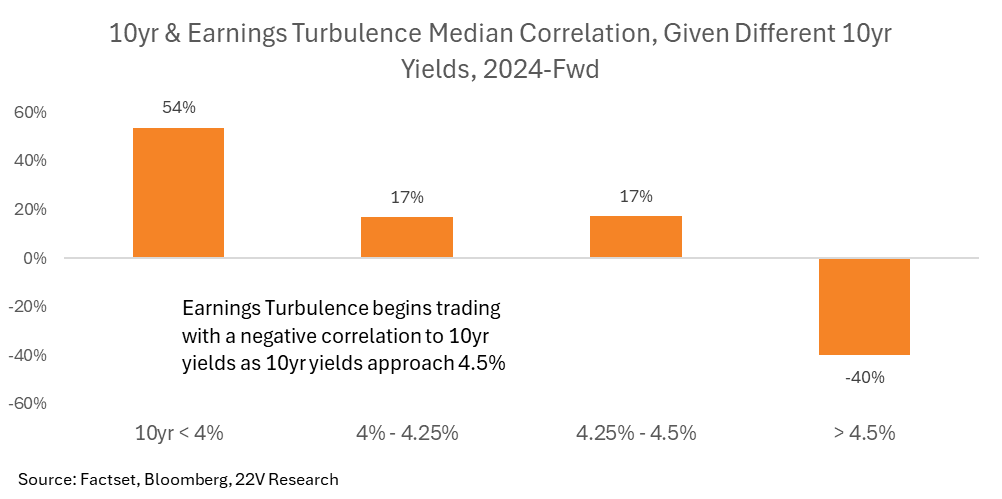
Banks should benefit from a steeper 10s-2s curve from here. All things equal, the riskiest factors (unprofitable small, debt risk, Retail investor favorites) should EVENTUALLY face headwinds as 10yr yields move higher. At first, stronger growth driving 10yr yields higher is not an issue when starting at 4%. Historically, it has not paid to fade risky factors until 10yr yields move toward 4.5% (HERE).

FYI – Yesterday, Michelle Meyer, the Chief economist of Mastercard’s Economic Institute said consumer spending had ACCELERATED into the first half of November vs October. Spending is tracking +3.6%, in line with Mastercard’s holiday spending forecast. Economic growth is firm, and the Fed is accommodative.

We Like Being Long Discretionary Now – 3Q Retailers earnings have been better than expected and the macro backdrop is supportive. Taken in aggregate, XRT company managers had an 81st percentile business trend sentiment score in 3Q. Labor market tail risks have been a significant overhang on the group along with tariffs. Both those headwinds seem to be fading. The lower end has struggled, but they should see short term relief from the OBBB in 1H26.

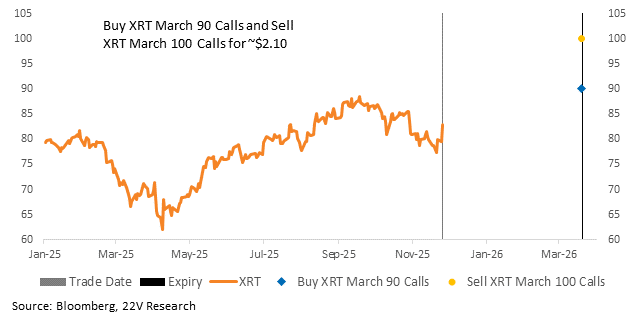
Jeff Jacobson, 22V Derivatives specialist, structured two trades to take advantage of a continued 1mo bounce or sustained rally in XRT. 1) Buy XRT Dec 26th 86 calls for ~ $1.60 (XRT 83.55 ref) 2) Buy XRT March 90/100 call spread for ~ $2.10 (XRT 83.55 ref). More in the charts section below.

Charts…

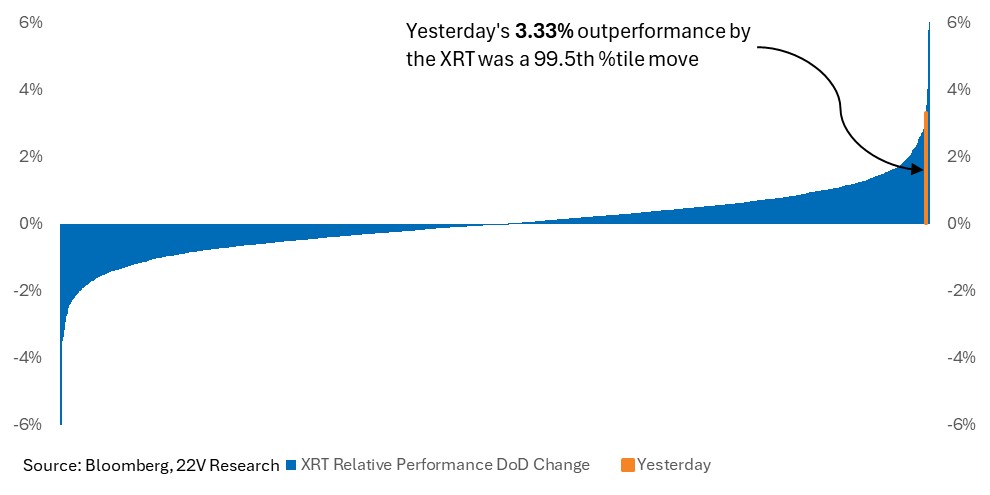
XRT outperformed by +3.33%, a 99.5th %tile relative move, yesterday. Retail is both consumer-sensitive and sensitive to rate expectations, so this kind of surge typically reflects shifting macro assumptions around household strength.
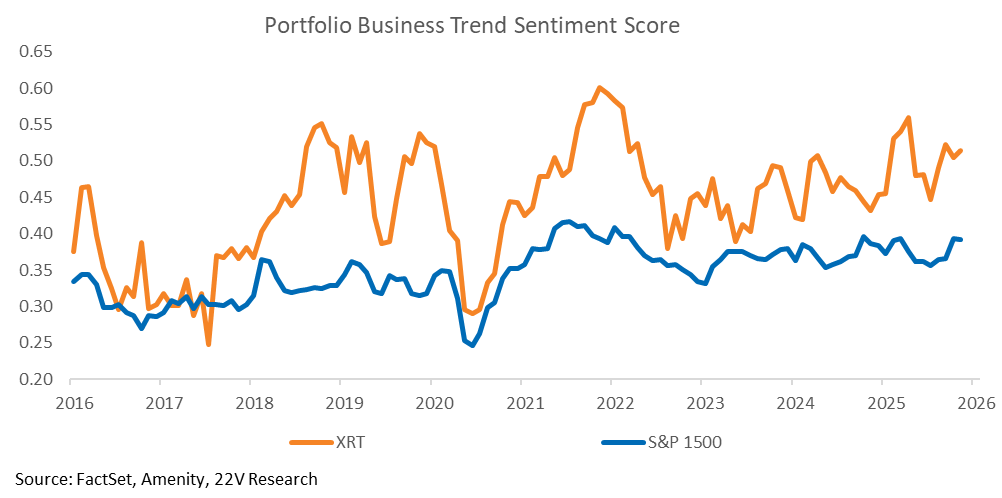
XRT management teams are expressing lots of optimism about their business trends. Sentiment, measured using the Amenity natural language processing tool and objectively scoring each earnings transcript, is at its 81st percentile.
A graph of a trend

AI-generated content may be incorrect.

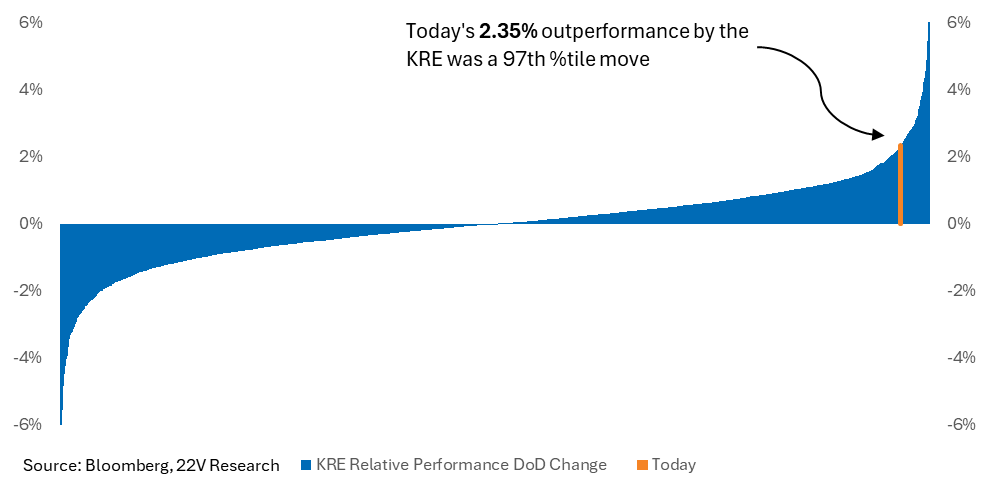
The KRE outperformed by 2.35%, marking a 97th%tile relative move.
A blue and white graph

AI-generated content may be incorrect.

Here are 2 trades Jeff likes in XRT to play for further upside even after the large rally yesterday.

1) Buy XRT Dec 26th 86 calls for ~ $1.60 (XRT 83.55 ref)

  • Shorter term trade to play for a breakout above the recent downtrend resistance and perhaps for a move back to the highs
  • Even with the large, realized moves, vol remains “fair” to cheap (XRT is up $4 just today)
  • Dec 26th expiry will capture more earnings from the sector, the black Friday updates, as well as a slew of economic data

2) Buy XRT March 90/100 call spread for ~ $2.10 (XRT 83.55 ref)

  • Buying the longer-dated upside call spread that starts just above the former highs
  • March expiry allows time for bullish thesis to play out and will capture next earnings period for the group
  • Call spread has a nearly 4x to 1 max payout on the limited-risk upside bullish bet
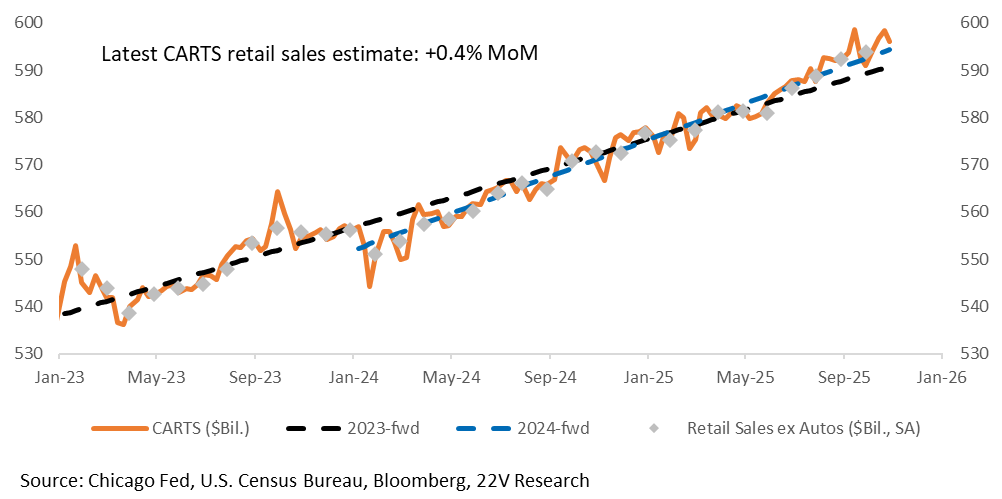
Retail sales data and the Chicago Fed’s aggregation of high frequency data, which is more current, indicate consumer spending continues at a strong pace.
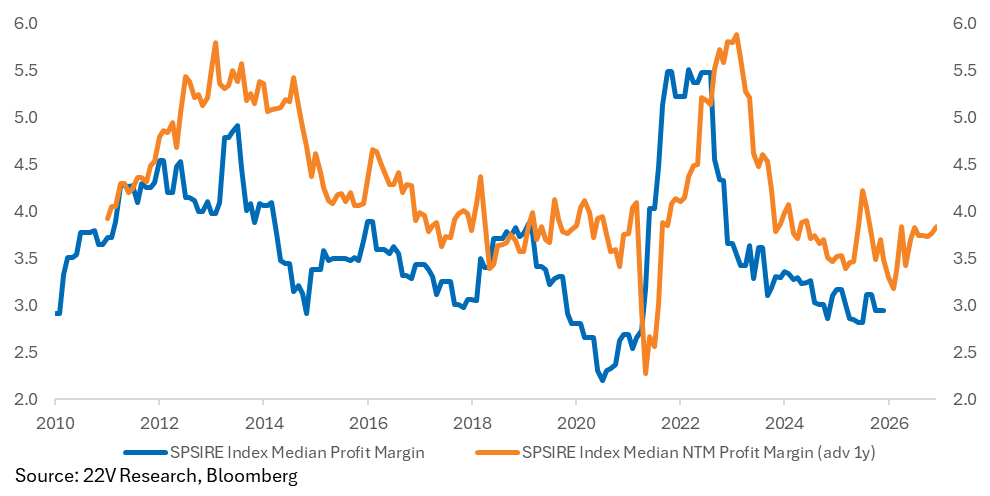
Discretionary has some work to do on margins…
A graph of blue and orange lines

AI-generated content may be incorrect.

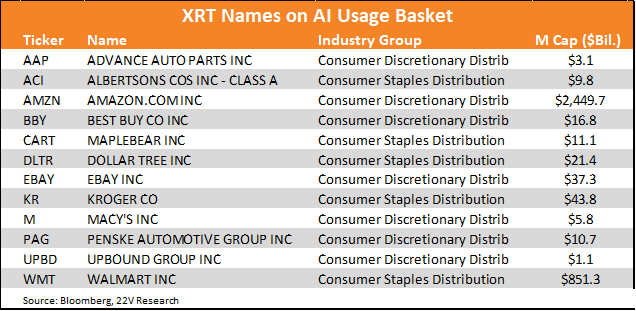
AI usage may be a good place to start looking for names that can improve margins. The Discretionary companies who have referenced specific use cases for AI are here…
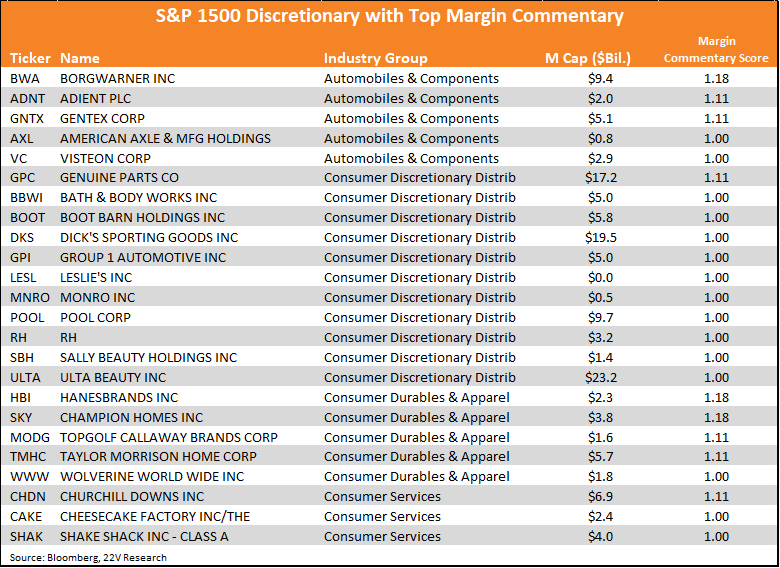
We can also source the Discretionary companies with the best margin sentiment. That list of stocks is here.
A table with a list of companies

AI-generated content may be incorrect.

Risk factor betas to yields falls as yields approach 4.5%. At 4%, the correlation is positive.
A graph with numbers and text

AI-generated content may be incorrect.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.