Back Portfolio Strategy

The Market Will Be Violently Flat through Year-end

Published on November 19, 2025

∙ Download the PDF Report

By

Dennis DeBusschere

Brian Herlihy

Kevin Brocks

Sophia Wang

DAILY STRATEGY: Our longer-term market views are risk positive. Less monetary policy easing is not inherently negative for markets if the labor market remains stable, growth stays firm, and core inflation (excluding tariff effects) is below 2.5%. The effective tariff rate appears to be trending lower (by policy, most recently evidenced by grocery tariff reductions, and courts) which will lift real incomes and support economic growth as OBBB provides an additional tailwind in 1H26.

However, the setup into year-end is tricky: there’s no strong case to buy aggressively, but it’s also not a clear shorting environment. Markets will remain “violently flat,” with sharp moves but no real direction short term. Uncertainty around AI capex returns for leveraged names (e.g., ORCL, Private Equity) likely won’t clear up until January earnings. Messy data is driving narrative-based trading that can swing hawkish or dovish, and there is a lot of data coming over the next couple months. The Fed is still expected to cut toward ~3% over time, but the committee is already split and that may muddle Fedspeak. Speculative stocks look overextended after a 99th percentile run-up, but we would take advantage of oversold conditions to buy high-quality cyclicals. Strong fundamentals will work best in a muddle-through.

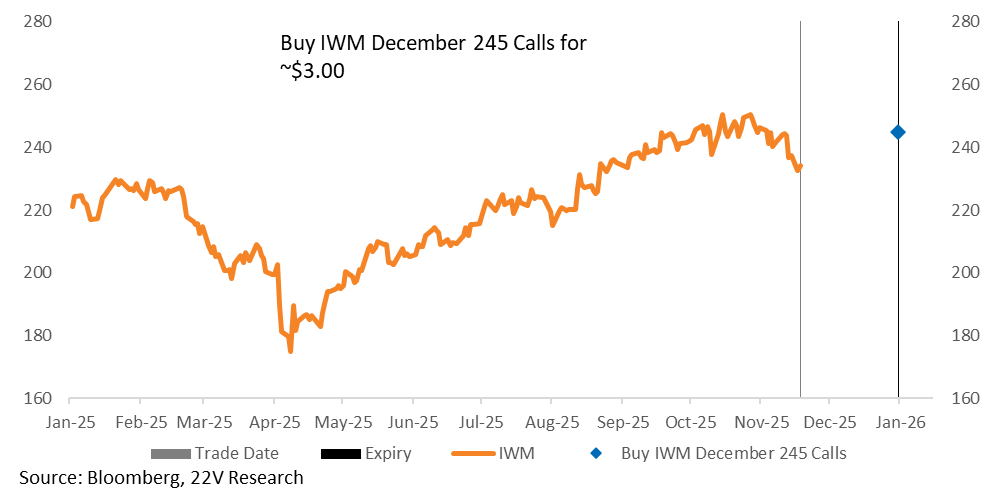
If the data ends up cleaner than we expect and/or there are data points that assuage AI capex concerns (looking at you, NVDA), go long small caps. Small caps did outperform yesterday in a down tape. Keep in mind small cap vol is elevated thanks to the growing contribution of speculative small caps to returns, but if things break the right way, they have a lot of upside after falling – Jeff Jacobson, 22V Derivatives specialist, put together an options trade to go long small caps: buy IWM Dec 31st 245 calls for $2.85 (IWM 232.60 ref).

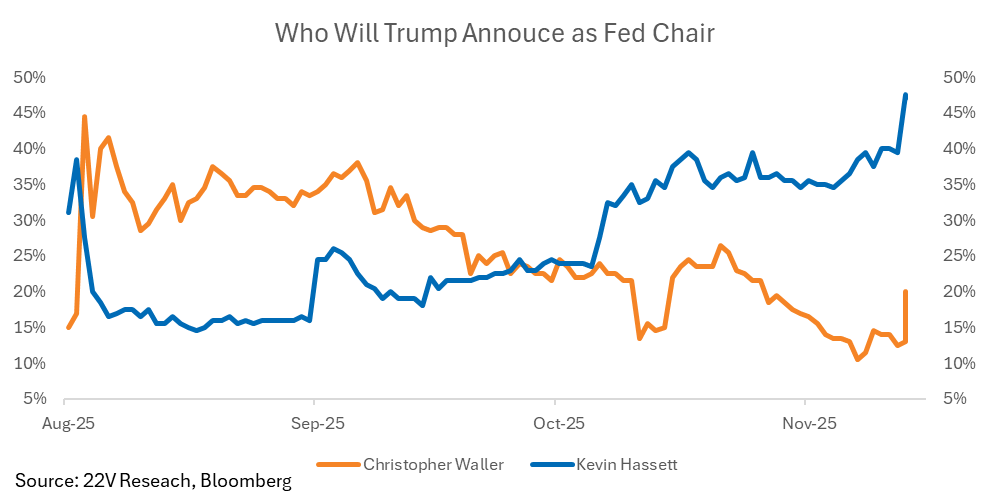
Quickly on Fed chairs… Trump’s latest comment that the administration “may go the standard way” on the Fed chair selection appears to have modestly boosted Waller’s odds on Polymarket, though Hassett remains the frontrunner. This continues to look like a Waller (dovish, conventional) versus Hassett (dovish, slightly more unconventional but with a more traditional background) race.

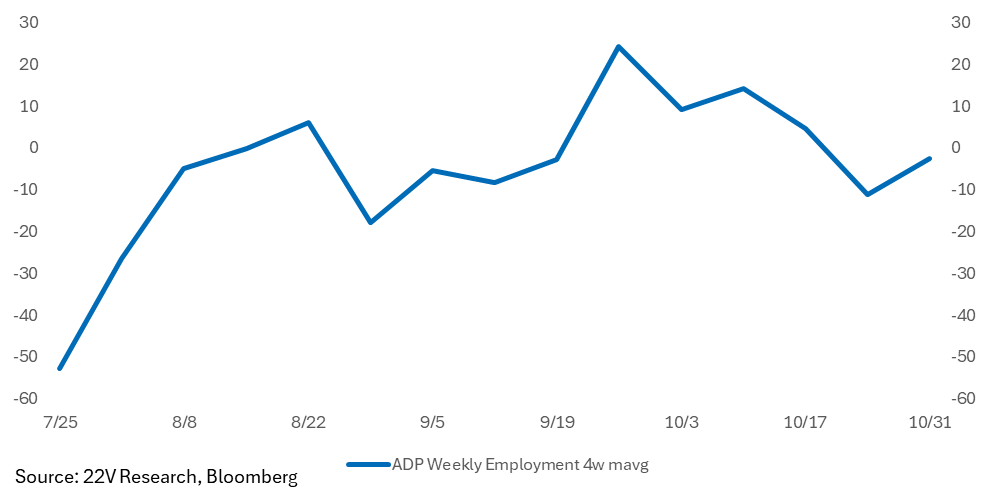
LABOR DATA – ADP data improved on a four-week basis ( -11k to -2.5k) but was still slightly negative. The odds of a December rate cut are still roughly 50%, with ADP not materially shifting expectations. Peter Williams, 22V Economist, notes ADP sees sequential hiring rising, but net hiring looks weak because retirements and workforce aging offset gains.

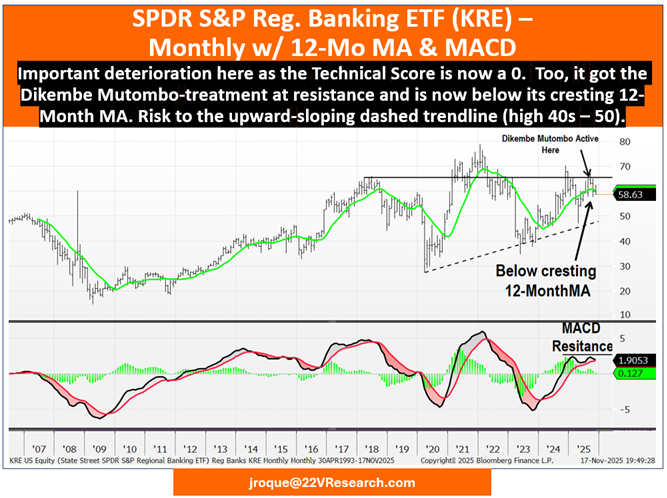
BANKS – 22V’s technical analyst, John Roque flags “advancing correction” traits in market internals and breadth. 22V Financials analyst, Bill Hebel, notes that if the economy can handle fewer cuts, it’s ultimately constructive for financials, though likely more of a 2026 story. XLF is holding its 200-day while KRE has broken below it. Still, benign credit conditions, supportive regulatory trends, and improved capital frameworks are positive for financials, and the Fed’s recent pushback has steepened the belly of the curve since earnings, aiding fixed-rate repricing. These dynamics should help the sector over time for patient investors.

Charts below….

We don’t have a compelling reason to aggressively buy right now, nor is this a clear environment for pressing shorts. Rather, it feels like a “violently flat” trading regime of sharp swings without durable direction. Oversold conditions support cyclical names with strong fundamentals, but speculative tech has run up unusually fast and now trades at stretched valuations.

A graph with blue and orange lines

AI-generated content may be incorrect.

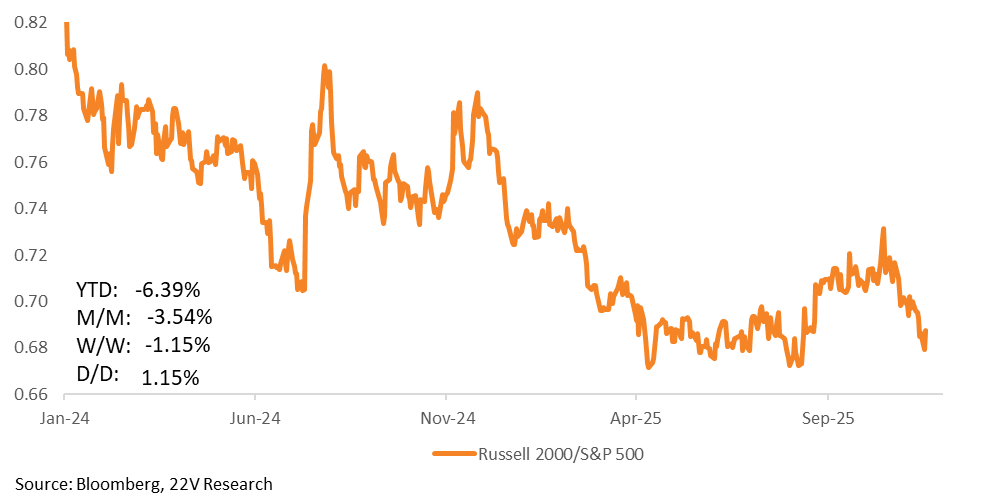
Small caps have begun diverging positively. Coming into yesterday, IWM had retraced much of its relative underperformance. While this could align with firmer economic data, we need to see it persist.
Given the choppy environment, short-term trading observations are particularly relevant. Jeff Jacobson, our head of options strategy, recommends buying IWM Dec 31st 245 calls for $3.00 (IWM ref 233.45 ref). These 27-delta calls offer limited risk and six weeks of duration. Implied vol is elevated but justified by realized vol. Importantly, IWM traded above 245 less than a week ago and has sharply lagged SPY and QQQ, creating catch-up potential if markets rebound into year-end as cleaner data arrives.
LABOR MARKET – ADP data yesterday morning was “less bad” on the four-week trend, improving from -11k to -2.5k, though still negative overall.
A line graph with numbers and a line

AI-generated content may be incorrect.

FINANICALS – Technically, XLF is holding its 200-day while KRE has broken below it. Still, benign credit conditions, supportive regulatory trends, and improved capital frameworks are positive for financials, and the Fed’s recent pushback has steepened the belly of the curve since earnings, aiding fixed-rate repricing. These dynamics should help the sector over time for patient investors.
A graph with lines and numbers

AI-generated content may be incorrect.

Quickly on the Fed… The Fed chair selection appears to be Waller vs Hassett, although Hasset is the main front runner.
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.