We continue to see weakness, both on an absolute and relative basis, in the consumer related trade. Whether it is housing, travel (see the airlines, hotels and cruise stocks) and now the retailers, all of those sector peaked in either Sept or early October and continue to be massive underperformers to the overall tape (which is back at the highs). Perhaps there are concerns by the consumer about the state of the job market, or they are just fed-up with the constantly rising prices of once “affordable “items?
According to 22V Economist Peter Williams:
From a macro perspective consumer spending has been solid but sentiment remains very weak given the spot data (lagging inflation and low churn likely the culprits there), and it seems likely that tariffs may be leading to another round of rotating weakness in consumer spending. The early evidence points more towards a modest hit to lower- and middle-income particularly younger, consumers who are feeling the new pinch on top of some building pressures since 2022 (post-covid demand and sectoral whipsaws another possible culprit too).
I continue to read and hear all about the concerns that the restaurants and fast-food companies have been saying on their earnings calls about the consumer pulling back, yet the relative performance of DoorDash (DASH) really stands out to me. According to an article in the Wall Street Journal regarding Chipotle earnings miss the other day:
Young people and low-income customers, buffeted by inflation, unemployment, and slower wage growth, are eating fewer burritos, Chipotle Chief Executive Scott Boatwright told analysts on a Wednesday conference call. Guests with household incomes below $100,000 represent 40% of the chain’s sales.
“We’re losing them to grocery and food at home,” Boatwright said. “They feel the pinch and we feel the pull back from them.”
So younger people have stopped buying $15 burritos, but we are expecting they will continue using DoorDash, where fees and tips can add as much as 30%+ to the already high food bill? Throw in the strong performance in shares off the April lows (+65%) and a “rich” valuation and I think there could be downside risk from these levels. DASH reports earnings on 11/5, and I am very curious as to what they have to say regarding customer demand given the very poor performance from many of the companies they work with (CMG, SHAK, SBUX, etc).
DASH has significantly outperformed many of the fast food companies it typically works with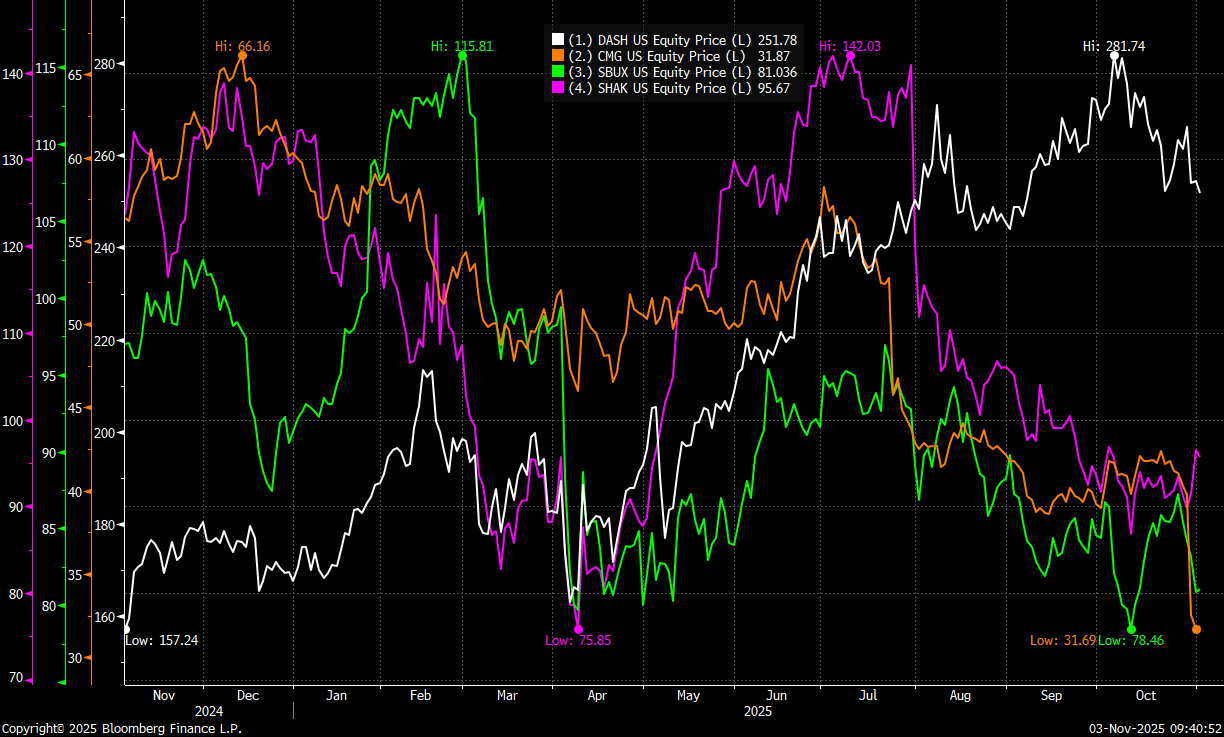
Looking at DASH stock it is now right in the middle of the well-defined 240-285 range it has effectively been trading in since July. I would argue that the risk of a break below 240 support seems greater than a breakout to new highs, especially given the evidence we are already seeing on the consumer demand side. One other thing that I wanted to highlight is the large open interest in the DASH November 240 calls (52.5k). The risk here in my opinion is IF the stock should break below that 240 level (which is also support) that we could see further selling pressure from the dealers who have delta-hedged their exposure to the sizeable short call position (by buying DASH shares). I don’t think this fact should be understated. Considering those calls currently carry a nearly 70-delta, the delta hedge long position could be as high as nearly 4mm shares on the dealer side. The stock only averages 4mm shares a day in volume, so I can absolutely see a scenario where if the stock breaks support we could see heavy selling pressure both from dealers who are long shares on their hedge as well as any momentum/technical buyers who would now be “forced” to sell based on price.
DASH has been trading between 240 and 285 since July. A break below 240 support could bring additional selling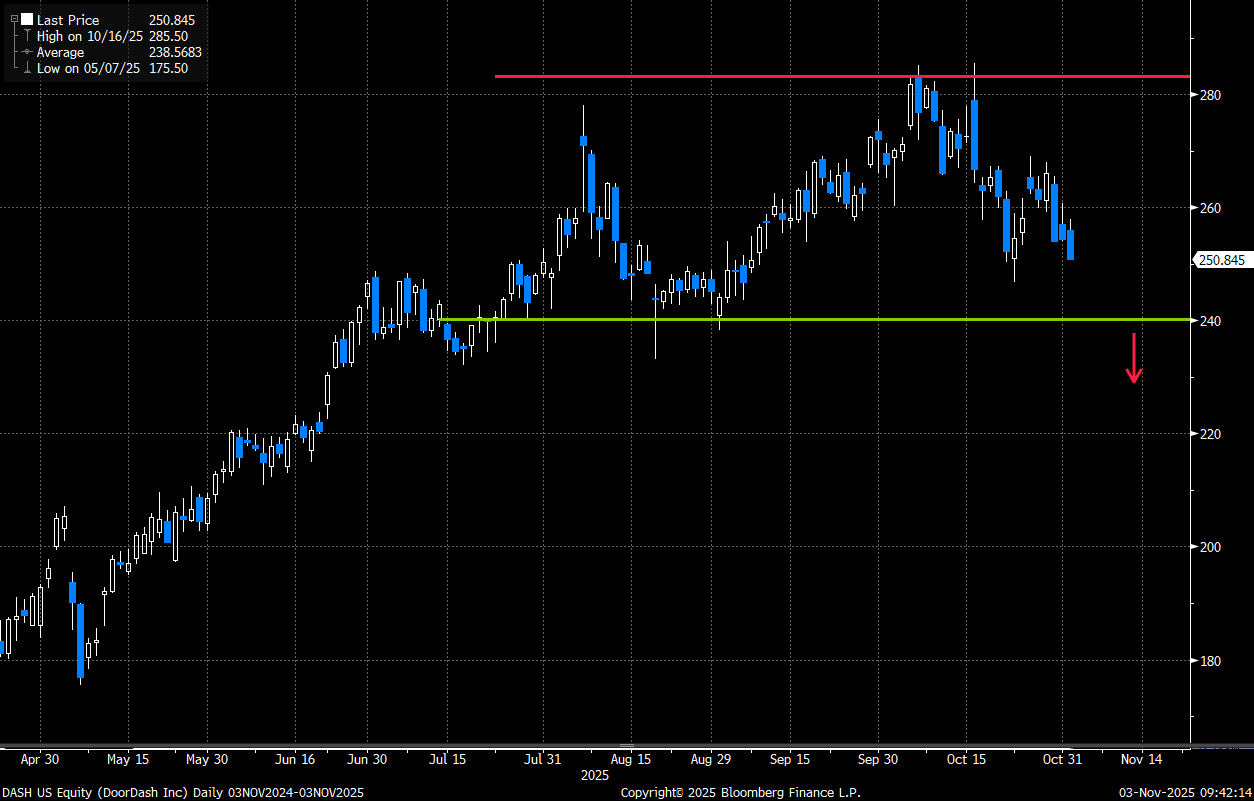
Very large open interest in the DASH Nov 240 calls. This could work against the shares on a move below 240 before Nov 21st expiry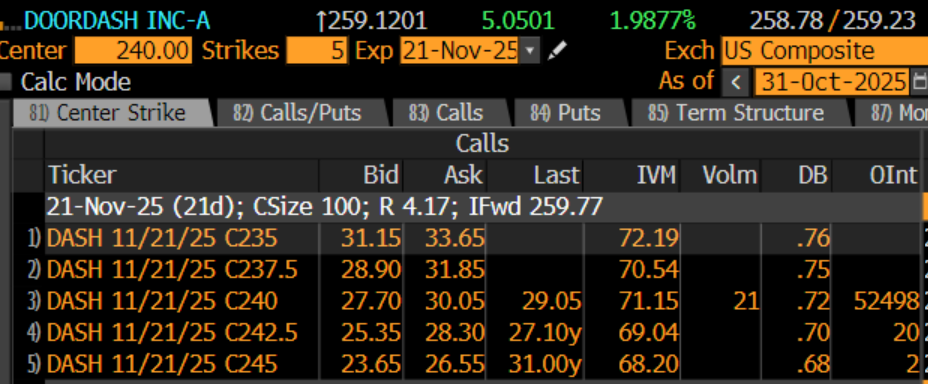
Given this setup, I think collars (if long) make a ton of sense here ahead of earnings. I would also consider low-cost collars for anyone looking to play for a downside move, while also allowing for an upside cushion. While I am targeting the Nov 240 call open interest as a possible catalyst for a real “break” lower, I prefer to look at Dec collars here as my preferred hedge/trade since that allows more time for trade to play out and also allows for a higher strike call sale to make trade less costly.
Trade:
Sell DASH Dec 280 calls
Buy DASH Dec 240 puts
Costs ~ $7 (DASH 250 stock ref)
Trade Details:
- Selling the 12% upside Dec call (near the highs) to buy the 4% downside Dec put ahead of earnings on 11/5
- The call sale will cover ~ 55% of the cost of owning the protective put, while also allowing a very sizeable upside cushion
- Weakness in several of the fast food/consumer names could be a sign that DASH momentum could start waning
- Large open-interest in the DASH Nov 240 calls (over 52k) could work against the shares should we see a move below that 240 strike
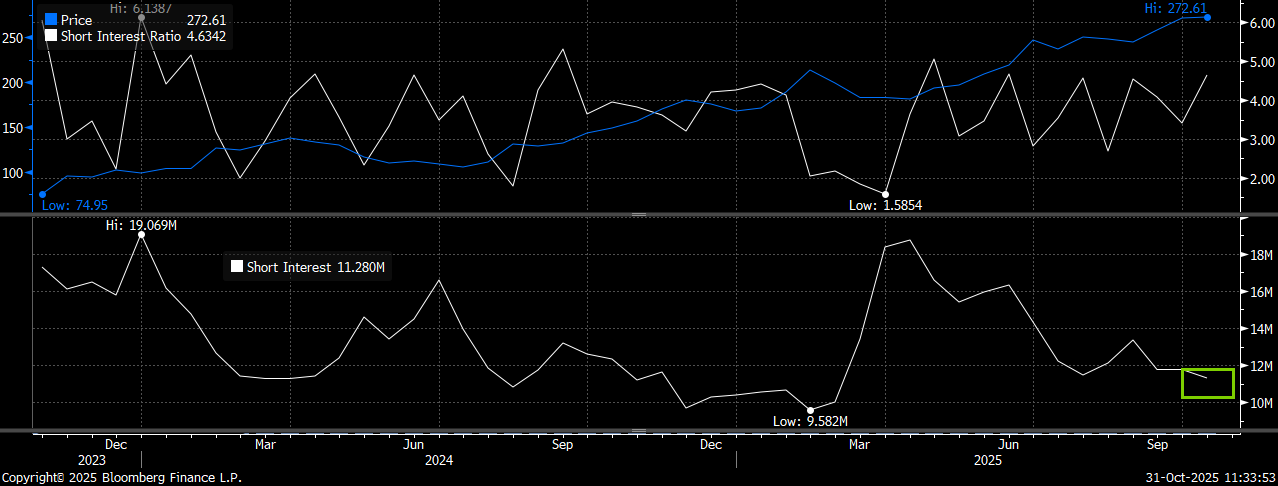
- DASH short-interest down from a high ~ 19mm in April to ~ 11mm currently. This could also support the collar as; 1) perhaps we have seen a fair amount of short covering already and 2) less buyers on a decline who would be looking to cover their short position
- DASH 2-month (Dec) implied vol is up ~ 50% from the August lows. Another reason why I prefer the low-cost collar to an outright put buy at this time
- Please contact me or the 22V sales team for updated pricing and execution capabilities
DASH 2-month implied vol has been steadily rising since August. Why I prefer the collar trade to buying puts outright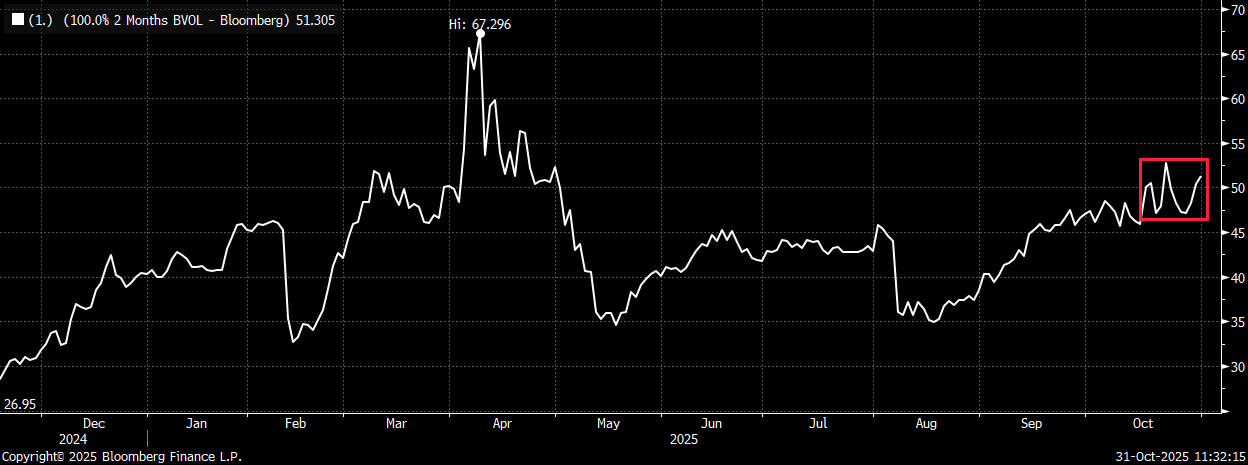
DASH short interest has been coming down from the April highs. This could explain some of the strength in the shares. It also means less ready buyers on a decline