As the market will now shift some of its focus away from macro concerns back to earnings, I like targeting sector ETFs where implied vol trades “cheap” to its top constituents, and where we could see some weakness/profit-taking after a sharp rally off the April lows. Why I also like the tactical setup to own hedges for these sector ETF’s is that besides the earnings, there are also a slew of potential catalysts over the next few weeks. Those catalysts will start this week with economic data (CPI on 7/15, PPI on 7/16, retail sales on 7/17 and then housing starts and U Michigan sentiment/inflation expectations on 7/18). We then will get the next FOMC rate decision on 7/30, followed by the Aug 1st tariff deadline and the July jobs report (also on Aug 1st). With volatility still very low on the index/sector front, I think this is an opportune time to consider adding sector hedges that will not just capture earnings season, but all these known potential catalysts for a market hedge. Here are two sectors where I believe adding hedges makes a lot of sense (especially if exposed heavily to some of the top-weighted names):
Communication Services (XLC)
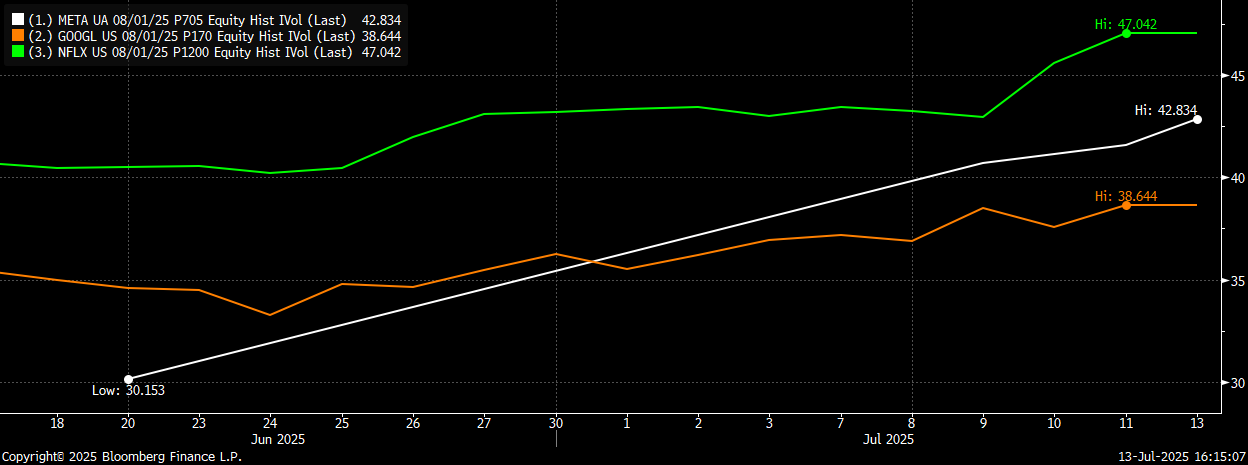
The main communications ETF rallied ~ 30% off the April lows to the highs hit on June 30th. It has since started to pull back a bit, especially as the market has started to rotate away from some “winners” to many of the laggards. What I especially like about owning XLC vol (puts) is that you get a lot of exposure to three names that have either performed very well off the lows, and/or where we have seen decent realized moves on earnings in the past. XLC has a 19% weighting in META, an 18% weighting in GOOGL, and an 8.35% weighting in Netflix (NFLX). All three of these companies will report before Aug 1st, along with all the other potential market moving catalysts I mentioned above that will occur by August 1st. With all three of those names having an implied vol on the 40-delta Aug 1st puts trading somewhere between 38 and 47, XLC puts for that same expiry are trading at an implied vol of ~ 19. Put another way, XLC has nearly 50% of its current exposure in these three names, yet the implied vol is less than HALF.
What I also like about owning XLC puts is that we are currently in the middle of some form of market rotation from winners to laggards. With the XLC/SPY relative spread having moved up nearly 13% from the Oct lows to the recent highs, we could continue to see more relative weakness from groups such as the communications sector that have sharply outperformed. With the XLC vol trading cheap to the main weightings, and all the other catalysts you capture, I like owning these puts at current levels.
Trade:
Buy XLC Aug 1st 104 puts for ~ $1.10 (XLC 106 ref)
Trade Details:
- Buying the puts that start ~ 2% below spot that capture bulk of earnings from the sector as well as economic and tariff-related data points
- XLC vol trades at a 50%+ discount to the top 3 names (META, GOOGL and NFLX) who combine for nearly 50% of the total exposure in the ETF
- XLC/SPY relative spread starting to move back lower after a nearly 13% outperformance by XLC since October
- Puts can be used to hedge exposure to the sector, or as a limited-risk bearish bet given attractive setup
- Please contact me or the 22V sales desk for updated pricing and execution capabilities
XLC rallied nearly 30% from the April lows to the June highs and is now starting to break below recent support

XLC/SPY relative spread also starting to move lower after a sharp outperformance by XLC since October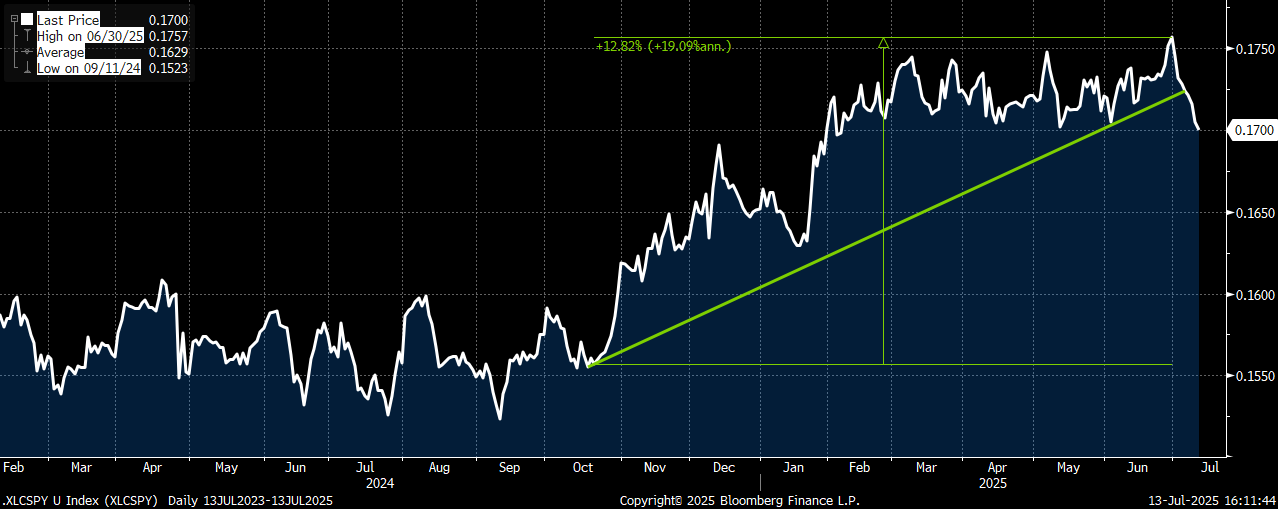
META, GOOGL and NFLX implied vol on the 40-delta Aug 1st puts traded between 38 and 47 (XLC vol is < 20)
Consumer Discretionary (XLY)
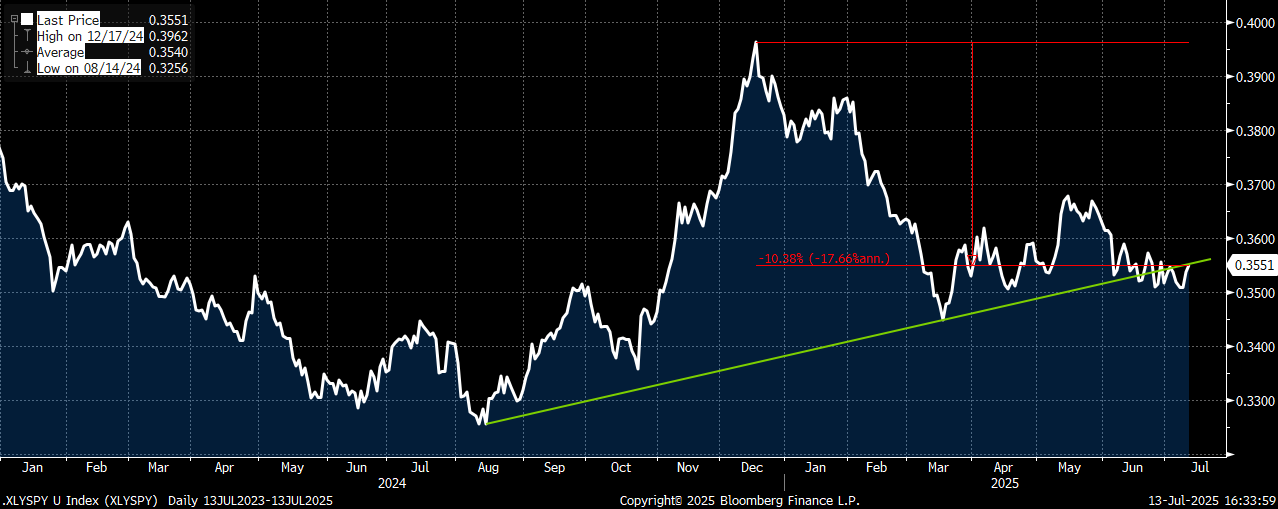
Don’t let the consumer discretionary name fool you, XLY is very much a “tech” ETF as Amazon (AMZN) is the top-weight at 23.5% and Tesla (TSLA) is the second largest weighting at nearly 16%. These two names comprise ~ 40% of the total weighting for XLY, and as they go so does XLY. AMZN is expected to report 7/30, and TSLA is confirmed to report on 7/23. We have seen large realized moves for both names on earnings over the past year or two (especially TSLA), so owning XLY vol (puts) also looks like an attractive way to position for a possible move lower in the sector or market, but at a much lower vol. The vol disparity is also large for XLY versus the largest weightings with AMZN implied vol ~ 38 and TSLA vol ~ 59 (while XLY vol trades closer to ~ 22).
As opposed to XLC, XLY has already been underperforming the market. The XLY/SPY peaked on a relative basis back in December, and has since lagged by more than 10%. With the sector already displaying relative weakness, it could be susceptible to another leg lower as the relative spread has already broken below the August ’24 uptrend support.
Trade:
Buy XLY Aug 1st 217.5 puts for $2.70 (XLY 221.43 ref)
Trade Details:
- Buying the Aug 1st (3-week) puts that start ~ 2% below spot
- Aug 1st expiry will capture TSLA earnings on 7/23, and then AMZN earnings on 7/30
- XLY vol trading at a decided discount to both TSLA and AMZN, and they comprise ~ 40% of the entire ETF
- Cheaper way to hedge both these well-owned names, as well as overall market hedge
- XLY peaked relative to SPY back in December and continues to underperform
- Please contact me or the 22V sales desk for updated pricing and execution capabilities
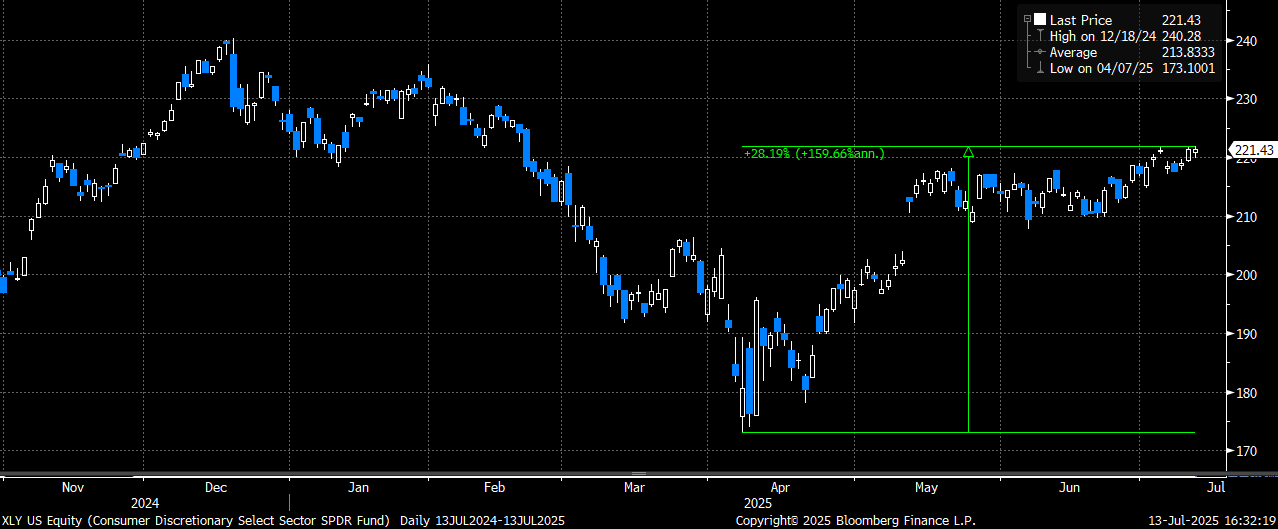
XLY has gained more than 28% since the April lows
XLY/SPY relative spread remains 10% below the Dec highs and recently broke below the Aug 2024 uptrend support