

In my note last week (here) I suggested that volatility likely put in a near-term bottom given the divergent action I was seeing (vol unable to make new relative lows even as the market continued higher). We certainly saw that thesis play out last week as the VIX was up nearly 30% and we saw weakness across the three major sector etf’s (SPY – 2.54%, QQQ -2.35% and IWM – 3.47%). Owning puts outright was a “win/win” as not only was the market lower across the board, but with the sharp rise in volatility the puts also benefitted from the vol (Vega) component as well. Even though we saw declines last week, and a rise in volatility, I am still in the camp that you want to own vol/hedges at this time. The sharp rise in yields, and now the news from Friday of tariffs on products coming from the EU potentially starting as early as June 1st, should continue to keep markets volatile for the foreseeable future.
After failing to make a new low even as markets continued to rally the week before, VVIX index rose sharply last week

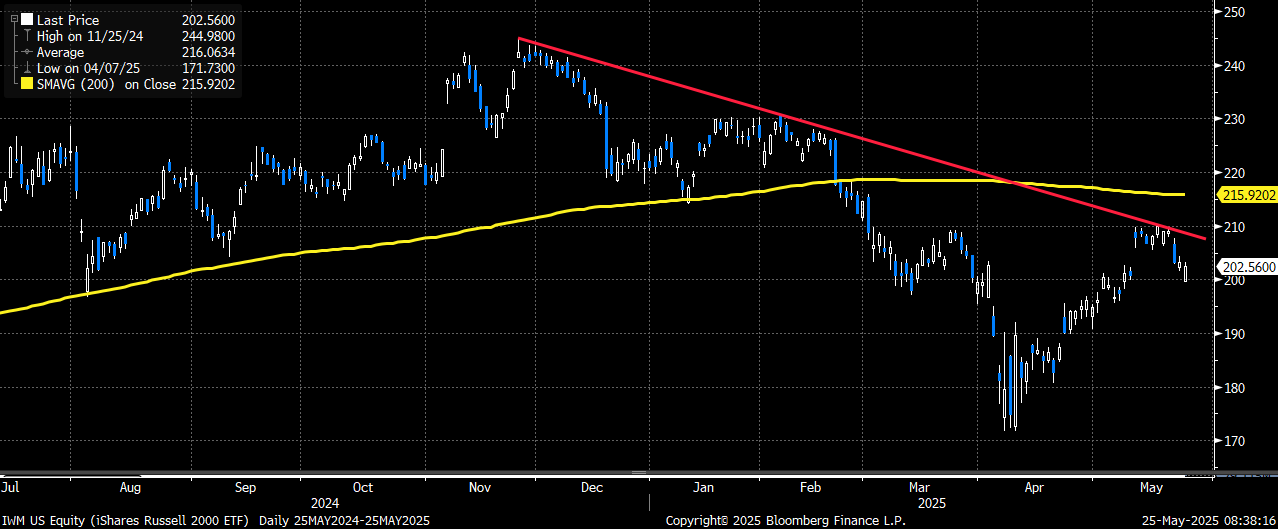
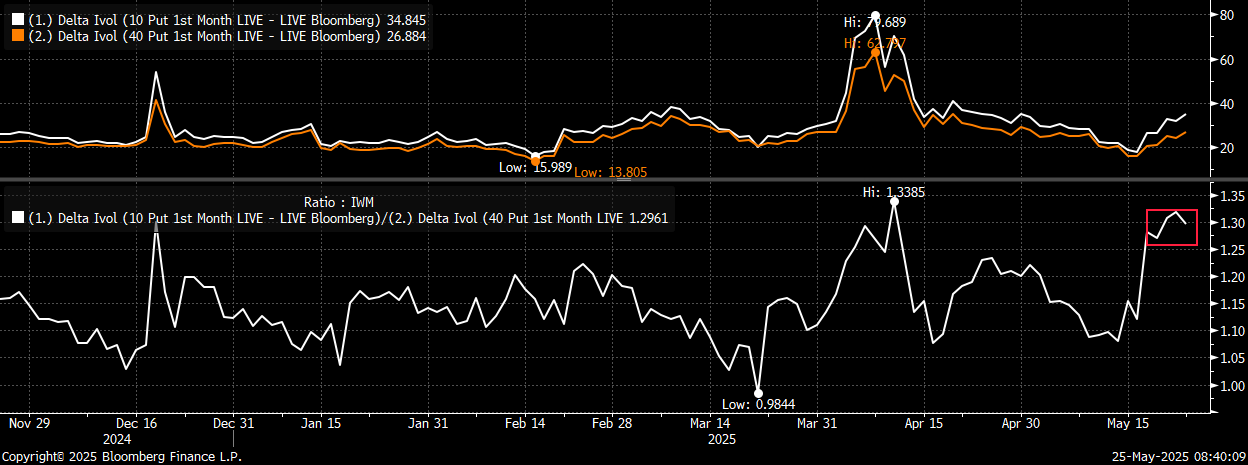
As far as which macro portfolio hedge to own now, I continue to prefer owning IWM puts (or wide put spreads). IWM failed to break above the December downtrend resistance or the 200-day as the market rebounded off the April lows, and now appears to be in jeopardy of moving back lower. As I have been saying recently, IWM put vol remains “cheap” to both SPY and QQQ puts, and we continue to see IWM perform better as a hedge when we do see market weakness (especially on a volatility adjusted basis). Last week was a good example of that as IWM underperformed SPY to a 1.37x beta and underperformed QQQ to a 1.48x beta. Vol adjusted, IWM continues to offer the best bang for the buck and until we see that dynamic change I want to continue to own it. I would still look at June expiry puts or wide puts spreads (as 10d/40d put skew is now back at the 6-month highs).
Here is a IWM put spread I would consider now if looking to add new portfolio hedges:
Buy IWM June 198/180 put spread for $3.00 (IWM 202.56 Fri close ref)
Trade Details:
- Buying the June put spread that starts just over 2% below spot
- Selling 35 vol vs buying 27 vol
- Selling the 180 puts (10% lower) covers more than 20% of the cost of owning the puts that start ~ 2% lower
- Trade offers a 5x to 1 max payoff
- We continue to see IWM perform as a “better” market hedge on a vol adjusted basis
- Please contact me or the 22V sales desk for updated pricing and execution capabilities
IWM failed to climb above both the December downtrend resistance or the 200-day moving average on the sharp rally back in the markets off the April lows
IWM 10-delta/40-delta put skew now back to the 6-month highs
Hedging Nvidia (NVDA) earnings with SMH options
The big earnings release this week will be on Wednesday (5/28) when NVDA reports after the close. While investors who are long the name may want to use NVDA options to help protect some of the recent gains (NVDA shares are up ~ 52% from their April lows), I wanted to highlight the main semiconductor etf (SMH) as an alternative way to play/hedge NVDA earnings.
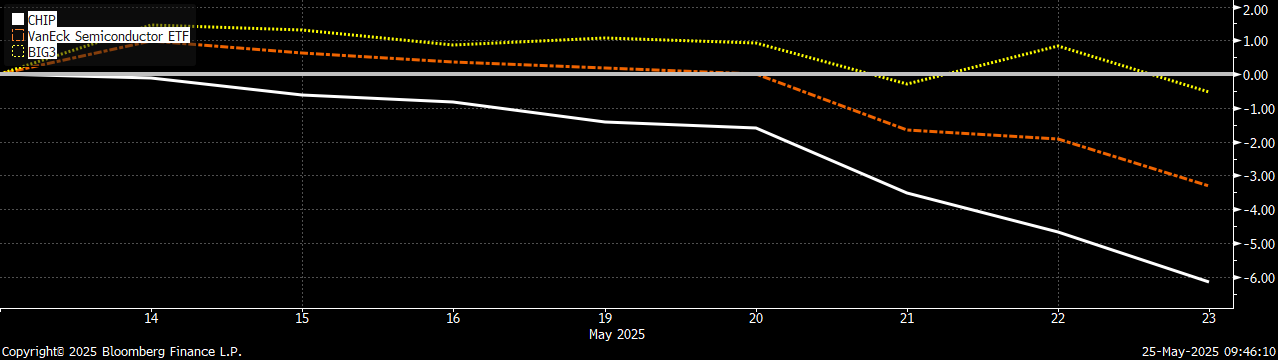
For some background, NVDA is the largest weighting in SMH at ~ 21%. The next two largest weightings, TSM 11.4% and AVGO 9.5%, are also closely tied into the AI “chip” trade and have all performed very well since the April lows. Recently, however, I have noticed a dislocation between these three names and the rest of the semi trade. I created an equal-weight index using the next 16 largest weightings in SMH (all with 1% weightings or higher) to highlight this divergence. Since peaking on 5/13, this index has since declined on each of the last eight days (down ~ 6.2%) and has sharply underperformed both the SMH and especially the “big three” of NVDA, TSM and AVGO (which are barely down during that time). The strength in these three names (which make up ~ 43% of SMH) seems to be masking the weakness in the rest of the semis. My feeling is if NVDA should disappoint on earnings or guidance, we could finally start to see the real impact on SMH (especially if the overall market continues to pullback from the post-tariff highs).
Since 5/13 the equal-weighted chip index (ex NVDA, TSM and AVGO) has sharply underperformed SMH (Orange) and the “big 3” (yellow)
Perhaps the weakness in the rest of the group stems from some disappointing earnings we have already gotten from some of the other players? In just the past few weeks we have seen large declines on earnings from several names (ASML -7.9%, AMAT -5.3%, QCOM -8.9%, ADI -4.6%. INTC -6.7% and NXPI – 6.9%). Also keep in mind, these negative reactions all came with the overall market, and especially the tech/growth trade, moving higher off the tariff lows. If SMH should “lose” the AI chip bid, it would appear that SMH, which is STILL up 40% off the April lows even with the numerous earnings disappointments, likely has decided downside risks.
We have already seen the impact that NVDA earnings could have on SMH. Back in late Feb, the last time that NVDA reported, we saw SMH drop by 6.2% when NVDA declined by ~ 8.5%. When we consider the volatility discrepancy between NVDA and SMH, it does make owning SMH hedges an interesting play in my opinion (especially given how poorly the rest of the group acts). In addition, if NVDA should perform well on earnings, I am not so sure that would have the positive impact to the rest of the semi trade and perhaps we just continue to see the divergence between the AI trade and the rest of the group widen?
Here are two trades I wanted to suggest in SMH ahead of NVDA earnings:
Trade #1 – SMH July put spread collar:
Sell SMH July 260 calls
Buy SMH July 230/190 put spread
Costs ~ $3.10 (SMH 237.44 Fri close ref)
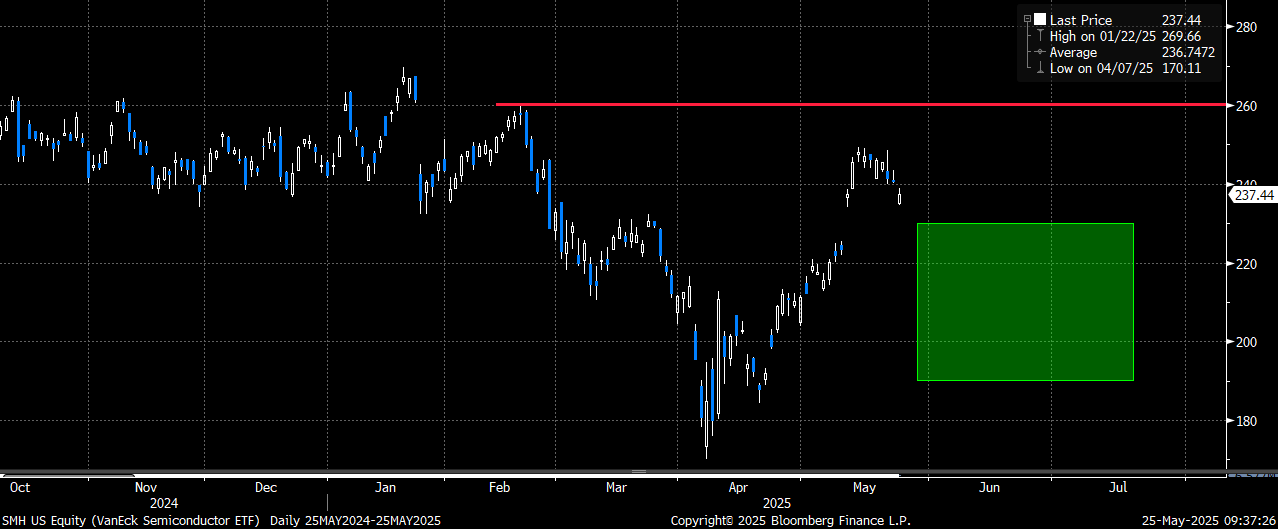
Selling the 260 calls (which are the Feb post-Deepseek highs) to buy the 230/190 put spread in July
Trade Details:
- Selling the 9.5% upside calls (at the Feb highs) to buy the wide put spread that starts ~ 3% below spot
- SMH is up 40% from the April lows, and given the weakness we are starting to see below the surface could see selling intensify if the AI chip trade comes under pressure
- Even if NVDA continues higher, the weakness we have seen from the rest of the group likely means the large upside move is a much smaller probability (why I favor selling that upside call at the Feb highs)
- SMH declined by 6.2% on the last NVDA report, so NVDA earnings could certainly impact the entire sector negatively again
- Please reach out to me or the 22V sale desk for updated pricing and execution capabilities
Trade #2 – Buy SMH June put spread
Buy SMH June 230 puts (35-delta, 40.5 vol)
Sell SMH June 205 puts (10-delta, 48.2 vol)
Costs ~ $4.75 (SMH 237.44 Fri close ref)
Trade Details:
- Buying the June put spread ahead of NVDA earnings on 5/28
- SMH up 40% from the lows, with a lot of the recent strength only coming from the AI trade
- June options will capture NVDA earnings on 5/28, and the AVGO on 6/5
- Cheaper way to hedge NVDA (and AVGO) then buying puts/hedges on those names individually
- Trade offers a 4.25x to 1 max payout on the limited-risk put spread
- Please reach out to me or the 22V sale desk for updated pricing and execution capabilities

