The market notched its ninth straight winning day (the longest such streak in twenty years) to end the week up nearly 3%. Optimism over a trade deal with China, as well as earnings coming in better than feared and a strong job report on Friday, were the main drivers of the rally. As the market continued to move back higher, VIX ended the week at 22.68 (down nearly 9%) and at its lowest levels since right before the tariffs were announced on 4/2. The market is now up ~ 18% from the lows on 4/7 and is now higher than when the tariffs were officially announced.
Given the strength of the rally off the lows, even with no official trade deal in place, it would stand to reason that protecting these gains with market hedges makes a lot of sense (especially given the sharp move lower in VIX). When looking at the current market/vol landscape, I keep going back to small caps (IWM) as my new preferred portfolio hedge. Here are several reasons why I would now consider IWM puts/put spreads over both SPY and QQQ hedges:
1) IWM puts are trading near their cheapest levels to SPY puts in the last 5 years
Because of their higher beta, we typically see IWM (2-month) 25-delta puts trading at a 30-40% premium to the same duration/delta SPY puts. However, on the recent market decline and accompanying move higher in implied vol, put skew between IWM and SPY has converged and IWM vol now only trades at a 17% vol premium to SPY. Since 2023 there have been five noteworthy declines in the market, and the average beta for IWM to SPY on those declines was ~ 1.55x (with no beta move of less than ~ 1.2x). With current vol skew only implying a 1.17x beta, I find this very attractive and would prefer to own IWM puts over SPY puts in case the market was to turn lower again after the sharp rally.
IWM 2-month 25d puts are only trading at a 17% premium to SPY 2-month 25d puts (bottom chart). The average premium over the last 5 years has been closer to a 35% premium (and they traded at over a 70% premium in December)

2. The Mag7 names are starting to outperform again
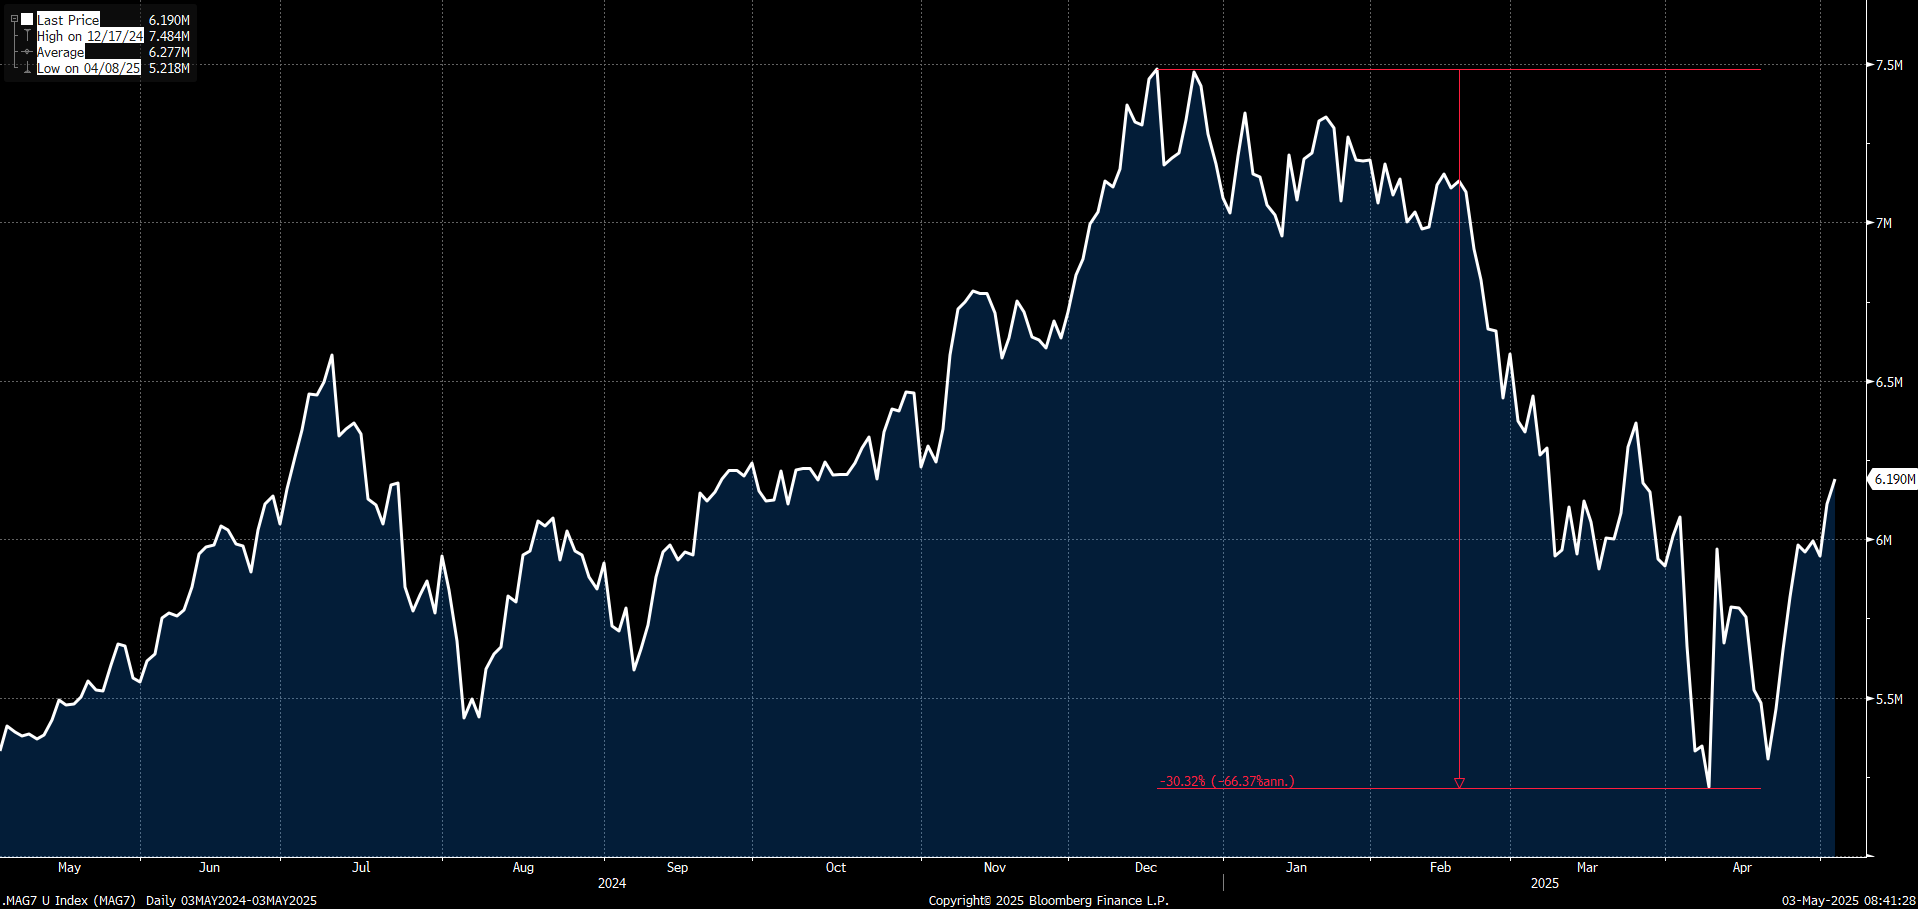
I created an equal-weighted Mag7 index that shows that they peaked on an absolute basis in mid-December and declined by as much as 30% at their April lows. Not only have they rebounded sharply off the lows (much like the overall market), but they are now starting to outperform the index (even with the move lower in AAPL on Friday after their results). These seven names comprise ~ 30% of SPY (and more than 40% of QQQ), and if they continue to outperform it likely means the index should hold up better on a market decline. Perhaps even more concerning for the small cap bulls is that during the time that the Mag7 had their largest drawdown, IWM STILL underperformed SPY by nearly 700 bps (-24.2% vs -17.3% or a 1.4x downside beta). If the small caps couldn’t manage to outperform the large caps when the top names were all underperforming, what chance do they have now that they are starting to outperform should we see another risk-off decline?
The equal-weight Mag7 index peaked in December and dropped by more than 30% at the April lows
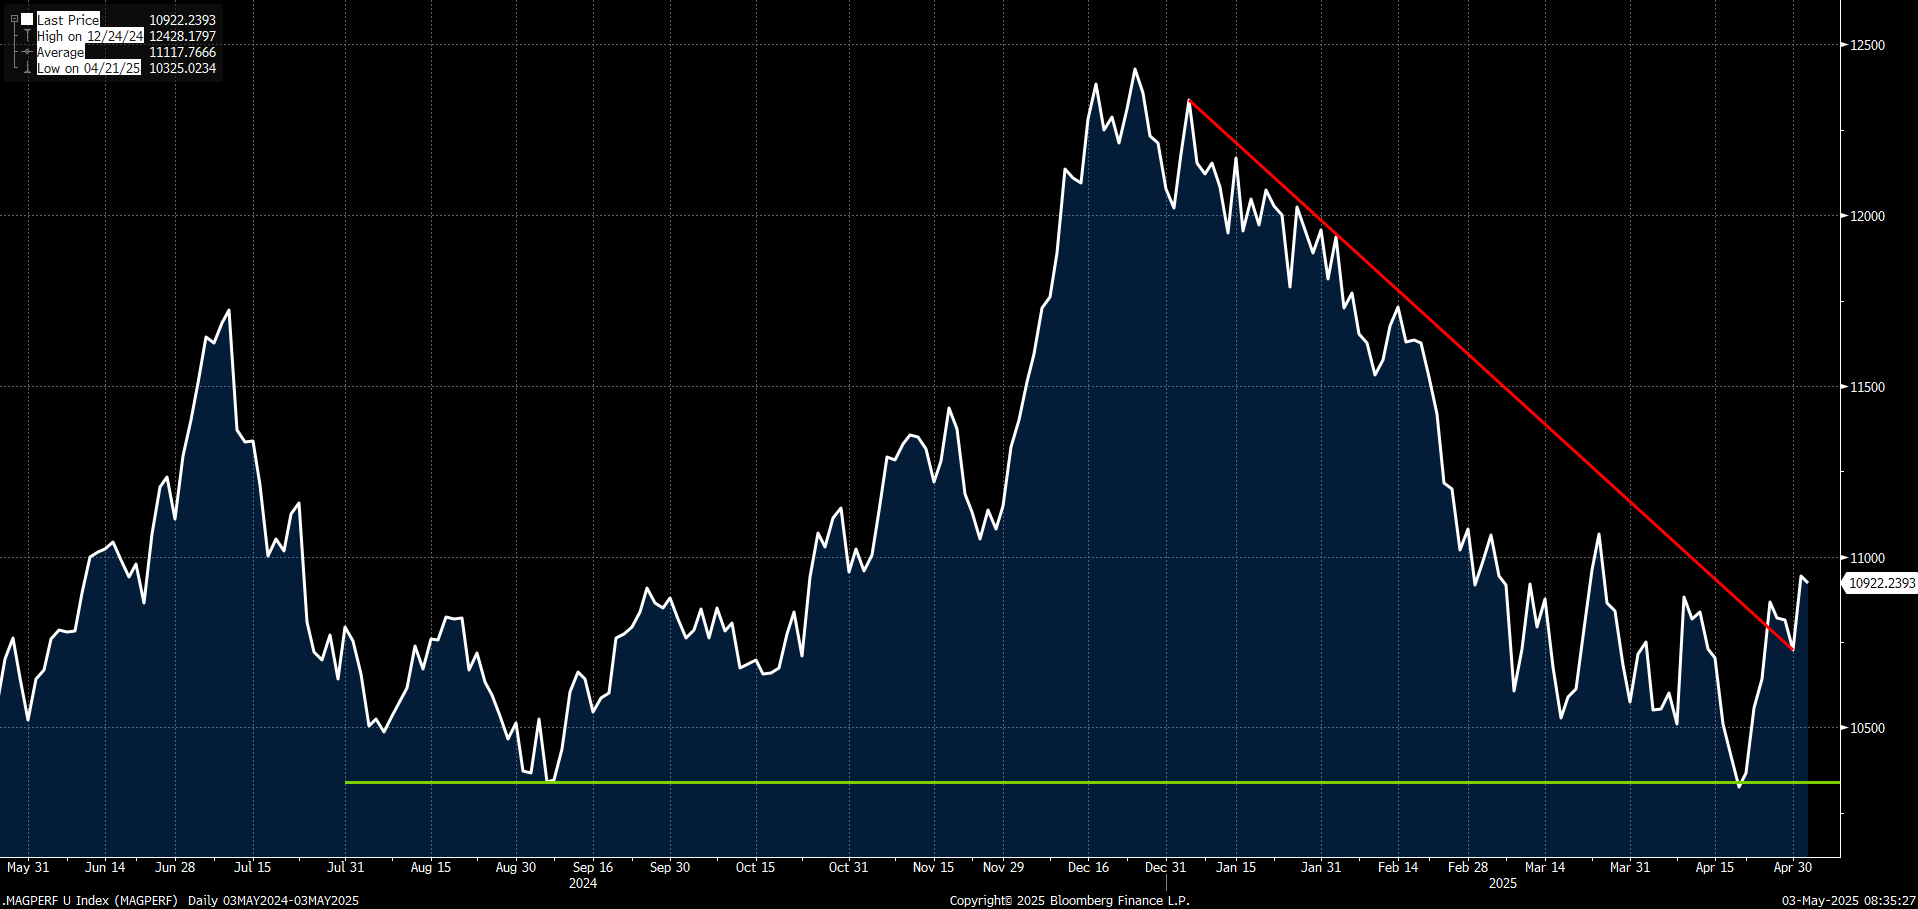
Here is the Mag7 equal-weight index to SPY relative spread chart. After a pullback to the September lows, the Mag7 are once again starting to outperform
As the Mag7 underperformed from mid-Dec thru early April, IWM still underperformed SPY by ~ 7% (1.4x beta to the downside)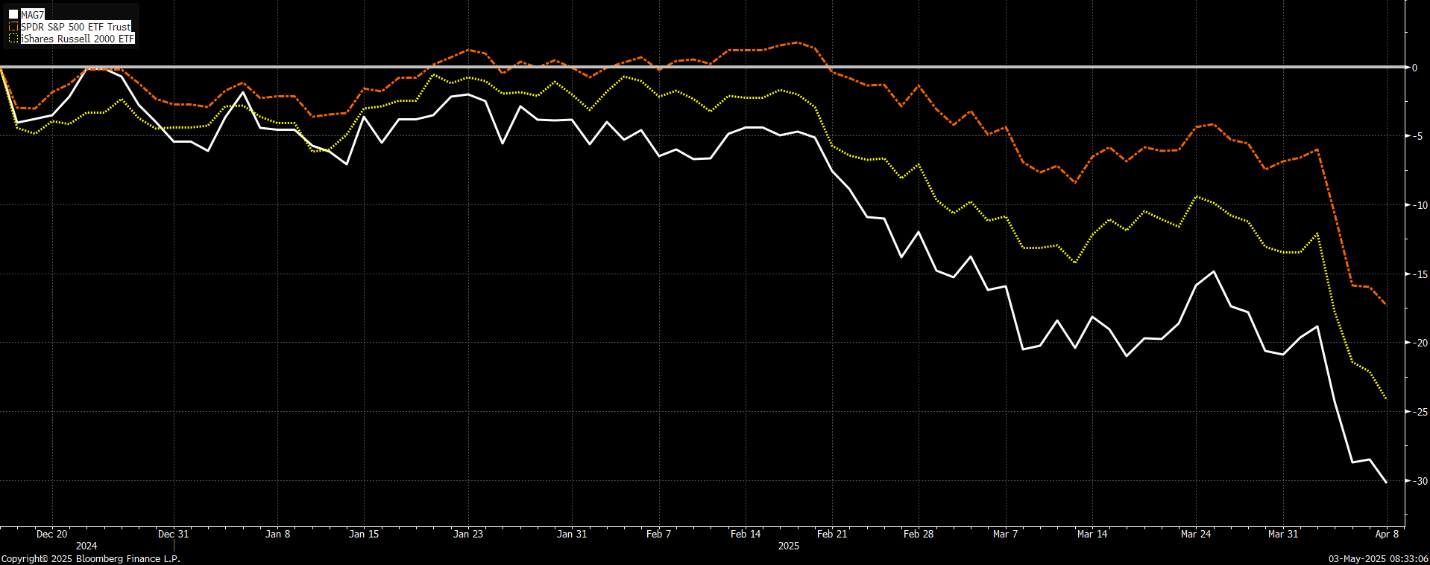
3. The two biggest risks to the market right now are a trade war or an inflation spike
This was in the 22V Portfolio Strategy note from Friday:
Small caps have acted poorly relative to large caps. As Peter Williams has pointed out, the “risks from tariffs are concentrated in small-to-med firms”. It seems like the China tariffs at 145% are a particular problem for small and medium sized business. Small caps came into this shock with lower margins and margin sentiment has deteriorated more than large and mid-cap stocks during 1Q25 EPS reporting season.
Since the markets bottomed on 4/7, IWM has also basically traded flat to SPY, while underperforming QQQ by 2.4%. if they have been unable to offer any upside beta on the relief rally on possible trade war deals, what chance do they have of offering outperformance should the optimism of a deal fade?
Given this backdrop of attractive skew, Mag7 names starting to outperform and small caps more negatively exposed to a trade deal not being able to be worked out, I absolutely prefer owning IWM hedges to either SPY or QQQ at this time. Here are two new hedge trades I would consider:
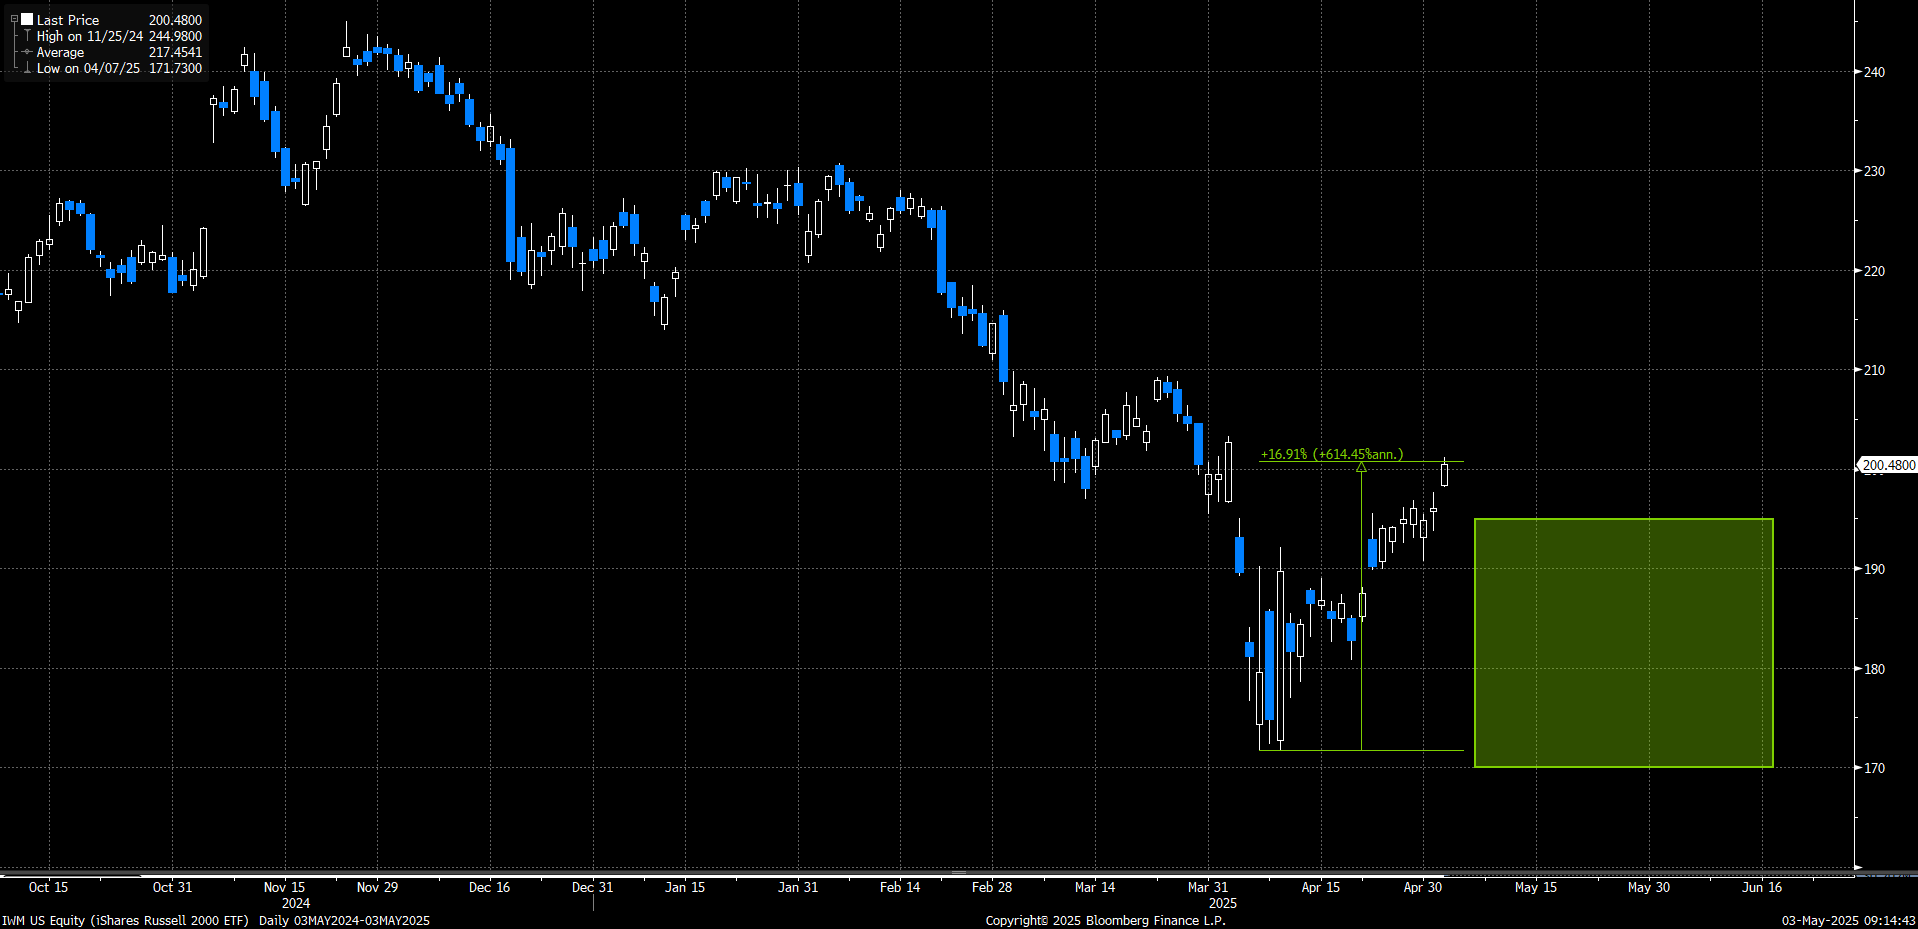
Buy IWM June 195/170 put spread for $3.90 (IWM 200.48 Fri close ref)
- Buying the June put spread following 17% rally off the April lows
- Put spread starts 2.7% below spot and is capped to the downside just below the April lows
- Trade offers a nearly 5.5x to 1 max payoff on the limited-risk hedge
- Trade captures 8 points of vol skew (selling 34 vol on the 170p vs buying 26 vol on the 195 puts)
- Trade has a 28-delta to start
- Please contact me or the 22V sales desk for updated pricing and execution capabilities
IWM with a 17% rally off the lows. The GREEN area shows the range pf the June put spread relative to the rally we just had
Buy IWM June 189 puts outright for $3.20 (IWM 200.48 Fri close ref)
- Buying the June 25-delta puts following the 17% rally off the April lows
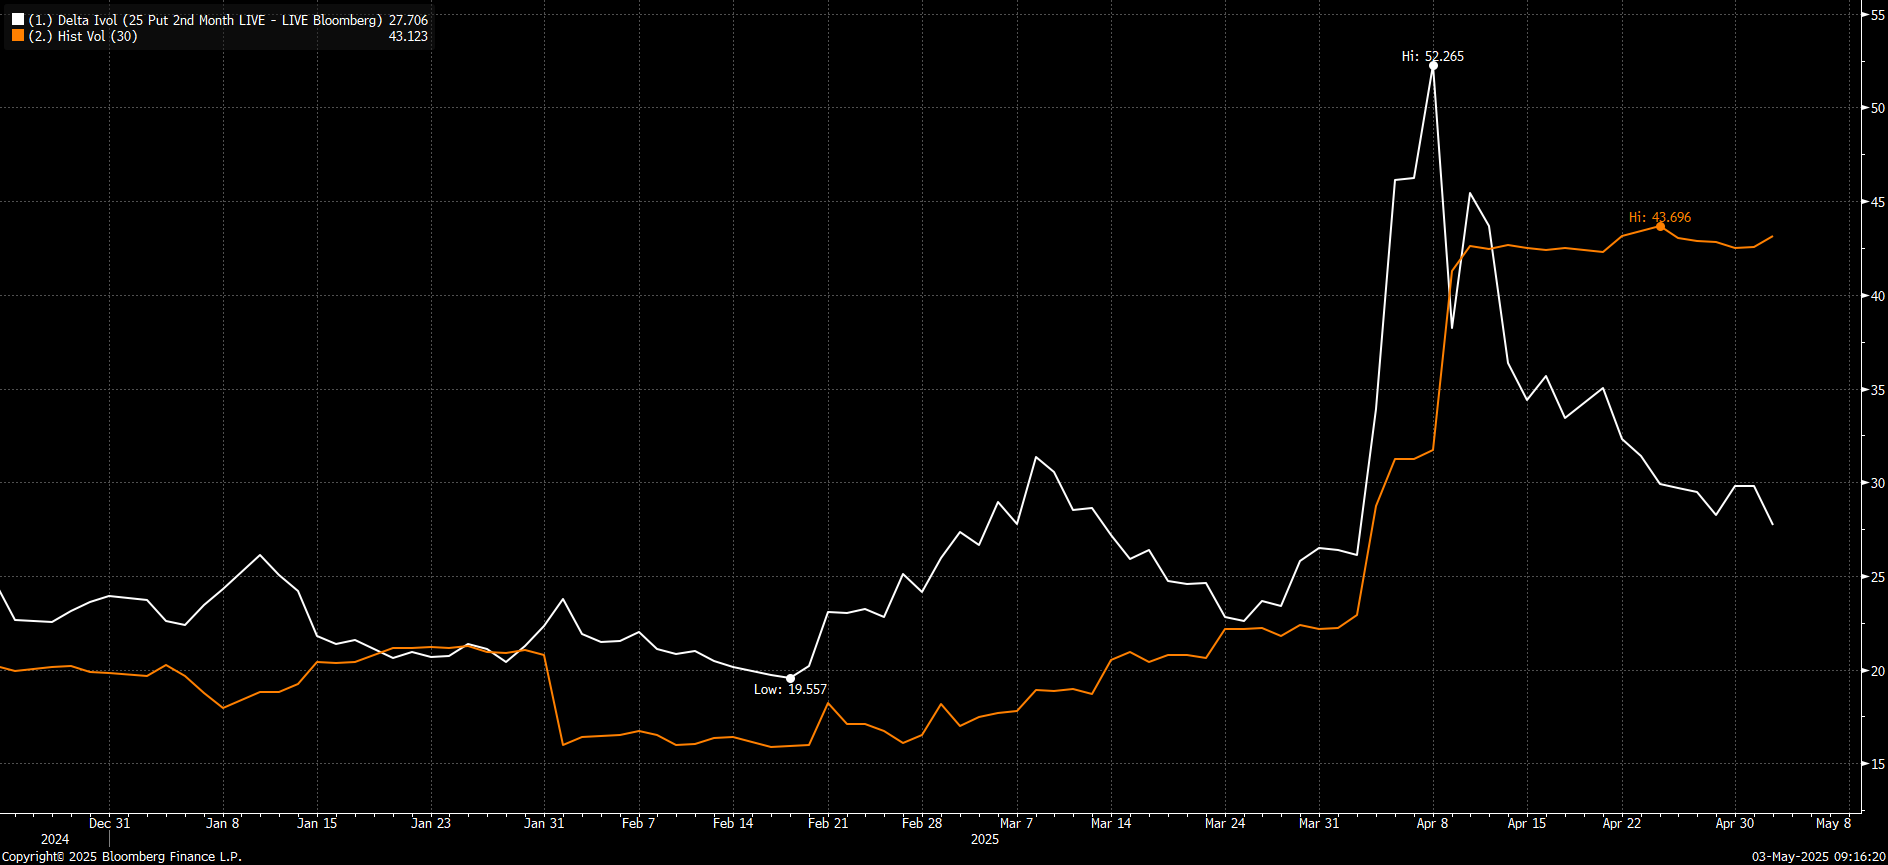
- IWM put vol has been cut in half from the highs and trades at a sharp discount to 30-day realized vol
- IWM puts trading near cheapest skew to SPY puts
- Would expect to see a move back higher in implied vol should we see market turn lower
- Please contact me or the 22V sales desk for updated pricing and execution capabilities
IWM 25-delta put vol in June is ~ 50% below the recent highs and now trades at a substantial discount to 30-day realized vol