

Time to double-down on energy stocks
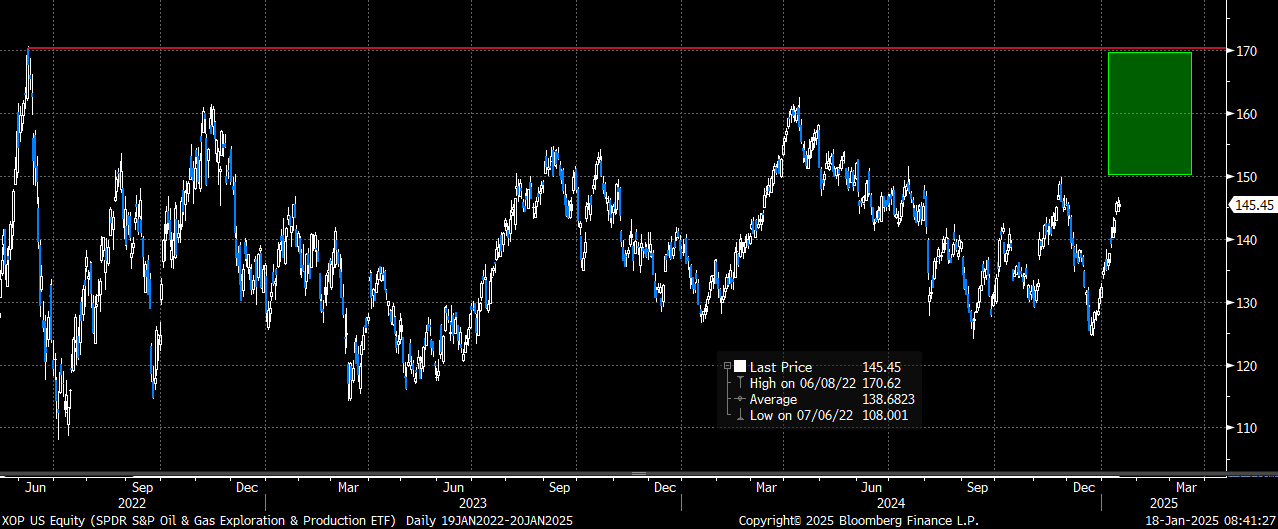
A few weeks ago I suggested adding upside exposure in energy stocks via XOP March options (https://22vresearch.com/2024/12/22/use-xop-options-to-add-upside-energy-exposure-following-sharp-pullback-and-underperformance-to-oil/). Since then, XOP has rallied ~ 16% and has reversed nearly all the sell off from the November highs to the December lows. I still believe energy stocks, and specifically XOP, are poised to move higher from here. First, 22V Head of Commodity Research, Colin Fenton, remains bullish on both oil and energy stocks. Here is his “What Glut” report from earlier this year (https://22vresearch.com/2025/01/02/what-glut-u-s-crude-oil-inventories-are-below-normal-and-falling/) as well as his recent “Abandoned Alpha” video (https://22vresearch.com/2025/01/08/video-abandoned-alpha-and-the-key-commodity-levers-for-2025/). Second, even with the sharp rebound in the XOP share price from the December lows, it still is trading historically cheap to the current price of crude oil.
XOP with a sharp rally off the December lows. Now targeting a possible move back to the 2022 highs
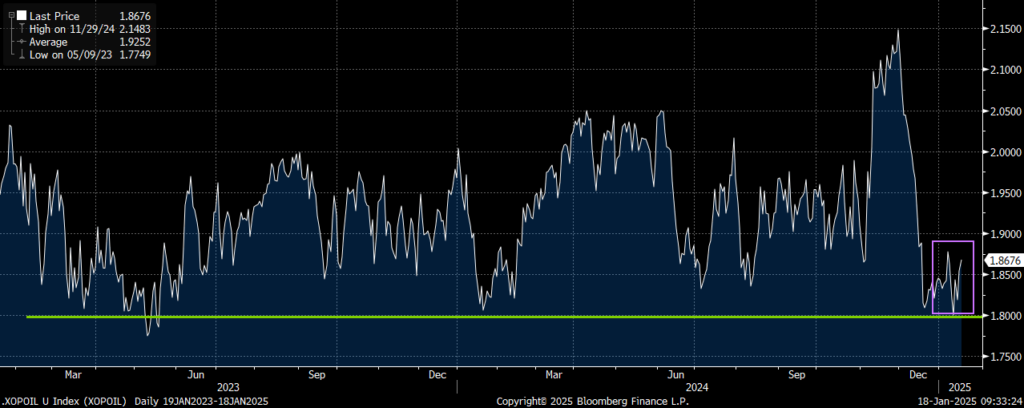
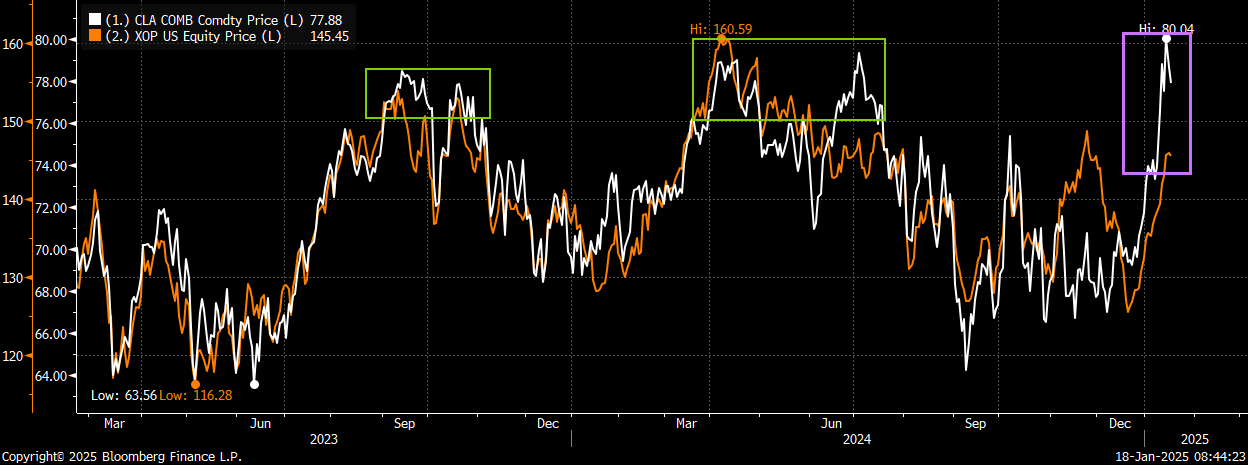
A big reason why I suggested adding upside XOP structures into year-end, besides Colin’s bullish (out of consensus) call, was that the XOP/Crude oil spread was trading at the 2-year supportive lows. Now, because oil has also had a sharp climb higher to start the year as well, that same XOP/Crude spread is still towards the lower end of that two-year spread. Over the last two years, on the four times when oil has traded above $77 (like it does now), XOP has traded between $152 and $160 on three of those four occasions. With XOP closing on Friday at $145.45, that would still imply considerable upside from here and that is assuming oil only stays here and doesn’t move higher (not Colin’s base case).
XOP/Oil spread still near the lower-end of the 2-year range
On 3 of the last 4 times oil was above $77 XOP traded between $152 and $160. Still seeing a huge divergence currently between oil (white) and XOP (orange)
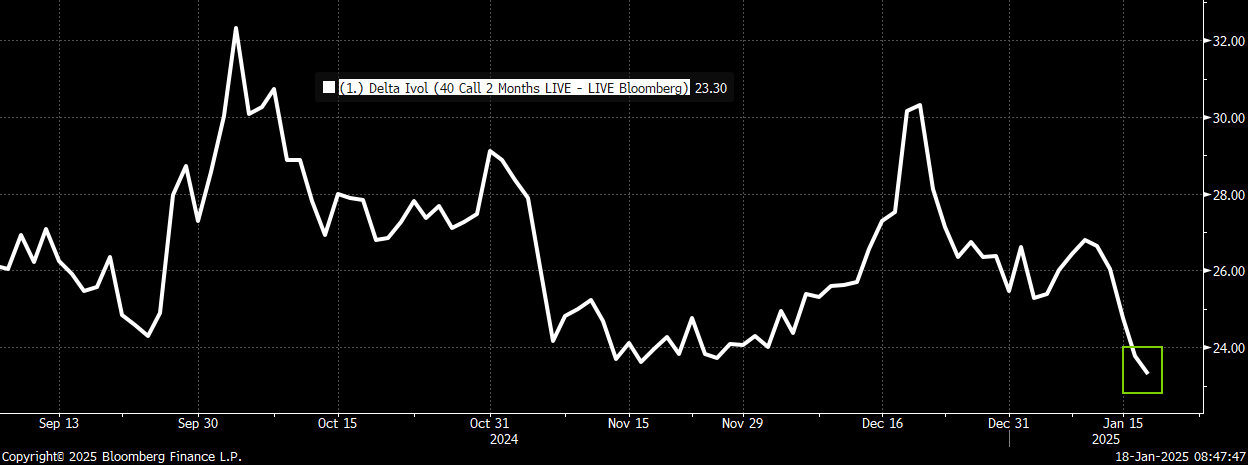
Another reason I still favor adding upsides in XOP is that as the stocks have been rallying, implied volatility on the 40-delta calls has come in sharply. In fact, 2-month (March) call vol is not at a 40-month low. With the upside 10-delta calls trading at a higher vol to the “cheaper” 40-delta calls, this sets up a very attractive opportunity to add additional upside for the sector for the next few months.
XOP 2-month (March) 40-delta call implied volatility at a fresh 4-month low
Trade:
Buy XOP March 150/170 Call Spread for $3.65 (XOP 145.45 stock ref)
Trade Details:
- Buying the XOP March call spread as a way to add more upside exposure in the sector
- Call spread starts 3% above current levels and is capped to the upside at the 2022 highs
- Trade offers a 4.5x to 1 max payoff at March expiry on a limited-risk basis
- March expiry also captures earnings for most of the top-weighted names in the sector
Gold acts very well in the face of a rising US$
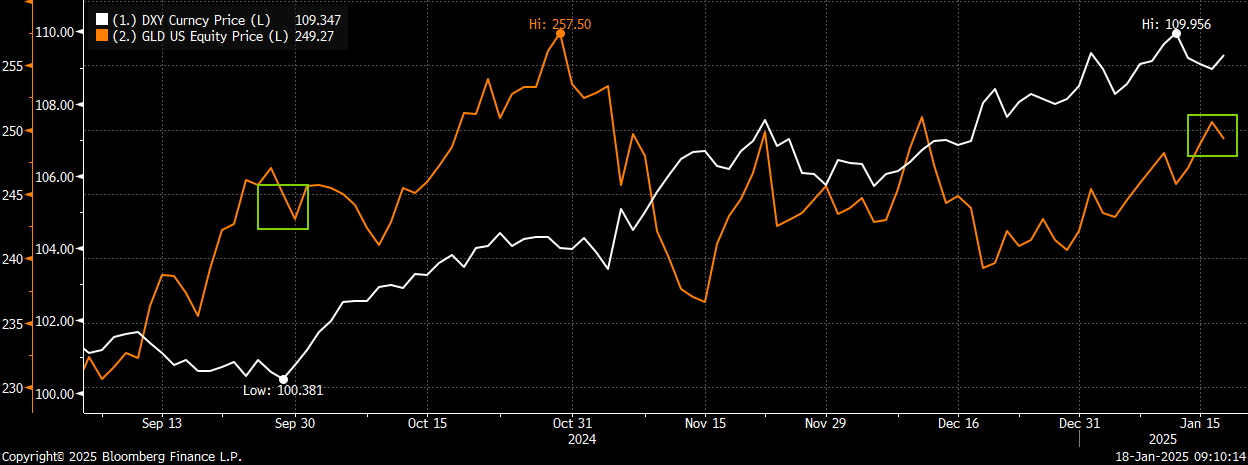
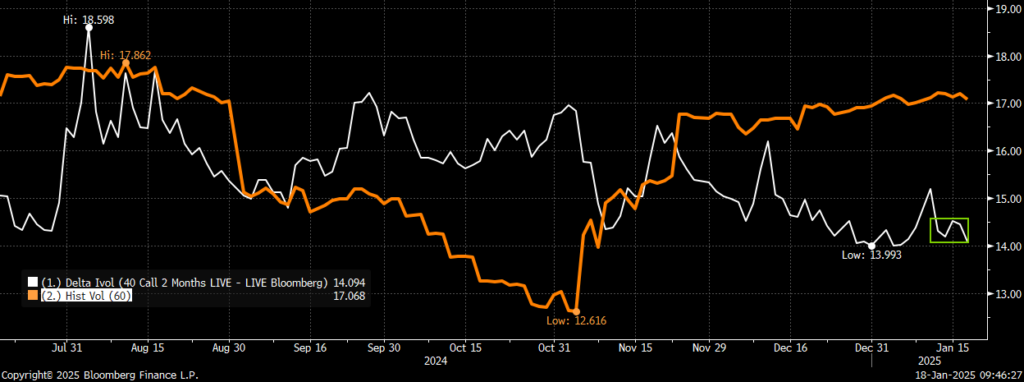
Really interesting technical and fundamental setup here in gold to position for a possible breakout above the recent range and play for a new high. As a backdrop, gold (GLD) has traded in a very narrow range between 237 and 251 since right after the election. Perhaps the most bullish aspect about gold is that it is higher today than where it closed on Sept 27th, even though the US$ index (DXY) is up over 9% over that time (from just above 100 to over 109). The fact that gold is still higher than where it was at the end of September, even as the US$ has had a massive rally, speaks to the underlying bid for gold (as a rising $ is usually a large headwind). Should we see any pullback in the $ then it seems rather plausible we can not only see gold breakout above this recent range, but perhaps challenge or eclipse the old highs from the end of October. Making this setup even more attractive is that 2-month (March) upside 40-delta call vol for GLD is back at the 6-month lows while trading at a sharp discount to 60-day realized vol. With call skew still bid (upside calls trading at a decided vol premium to the closer to the money calls) I favor adding low-cost/high payout Feb call spreads at this time.
GLD has been trading in a narrow range since after the election. Appears poised to eventually breakout to the upside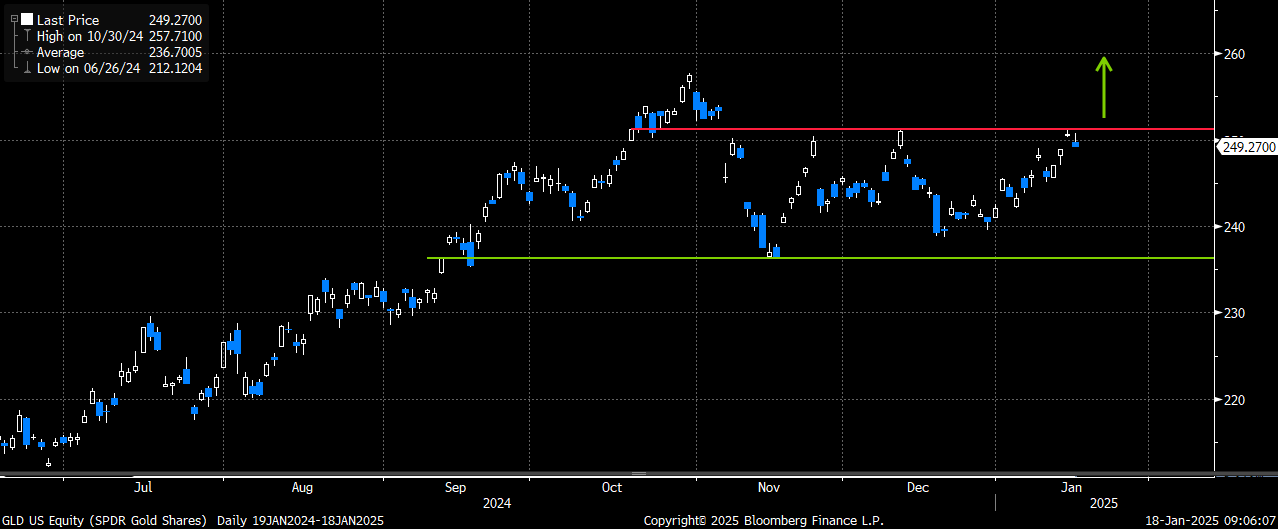
Gold (orange) is HIGHER now than at the end of September even as the US$ index (DXY) has climbed from 100 to over 109
GLD 2-month (March) 40-delta call vol back to the lows as 60-day realized vol remains elevated
Trade:
Buy GLD March 255/275 call spread for $3.40 (GLD 249.27 ref)
Trade Details:
- Buying the 2-month (March) upside call spread in GLD to position for a possible breakout to new all-time highs
- Gold continues to act VERY well as it has managed to trade higher even as the US$ index has climbed by 9% since the end of September
- Should we see any pullback in the $, that could be the catalyst for gold to make new highs
- Call spread starts ~ 3% higher (at the October highs) and offers a nearly 5x to 1 max payout at March expiry
- Seeing 2-month 40-delta call implied vol back at the lows, even with 60-day realized vol near the recent highs
- 22V baseline price target for cash gold at year-end is $2,900. We estimate 75% probability that year-end cash price is higher than Jan 13th close.
- Low-cost way to position for new highs in the next two months
Please contact me or the trading desk for updated pricing and execution capabilities.

