

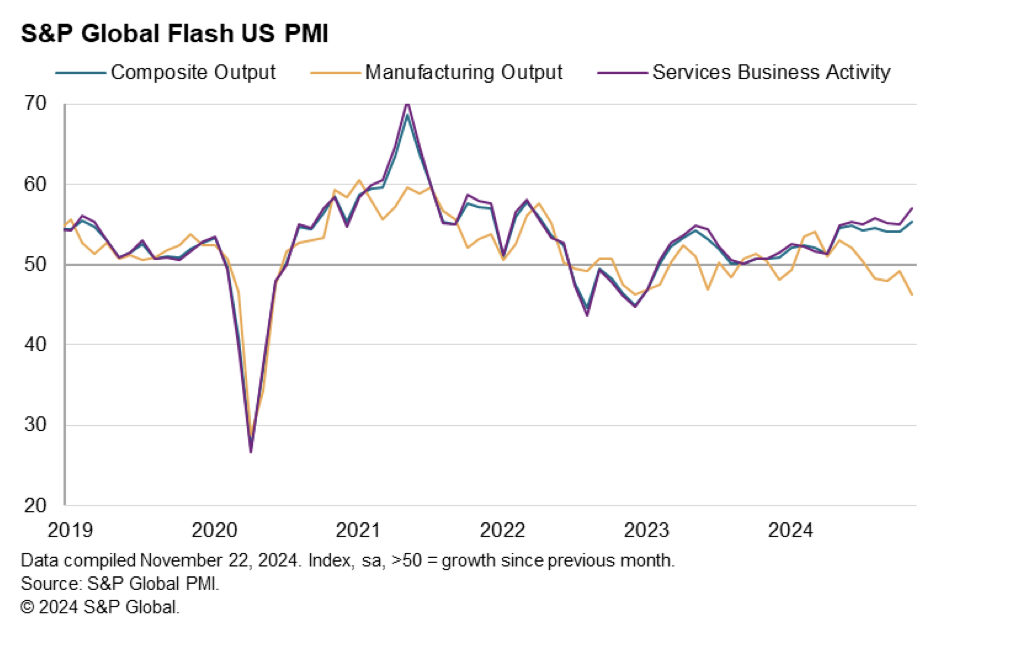
The overall index beat, entirely because of services, which rose meaningfully from a strong level. The (current period) manufacturing index was weak on a headline basis, and weaker on the production side. Within manufacturing, expectations moved strongly higher, seemingly imitating the pattern in yesterday’s Philly Fed.
Manufacturing Detail

Source: S&P Global as linked above
Data are to the November preliminary
Let’s start with manufacturing. The headline index was little changed, rising from 48.5 in the October final to 48.8 in the November preliminary, and missing by just a tenth. The current production series fell to indicate contraction at a “sharply increased rate.” But all other components moved higher, including new orders. The text mentions that supplier delivery times lengthened in response to a desire to build stock ahead of the possible implementation of tariffs. And I can see why people are focused on that because it is a live theme for obvious reasons. But if you look at the actual supplier delivery series, there is not really much of a move there.
The report also notes that sentiment about future prospects rose steeply in November to a 31-month high. That optimism about the future along with sluggish current conditions looks a lot like what we heard from the Philly Fed, which I discussed in a short note yesterday. Here is S&P global on what they take to be the source of that optimism. I assume the word “environmental” came out in editing. I doubt they are looking for less trade protection:
Respondents also often cited a more business friendly incoming administration as beneficial to the outlook, notably in terms of looser regulation and protection measures, the latter helping to boost sentiment particularly in manufacturing.
The service sector data were more upbeat and can be handled more briefly. The service sector output index rose 2 points to 57, a 32-month high. However, the employment index signaled contraction at a quickening pace, according to the Press Release.
This report is mixed in terms of the growth signal, although my own priors are to place a higher weight on services, because it is a larger share of the economy. What I would say with a bit more confidence is that the mood in the business sector has brightened but without a major inflection in overall growth happening right now. The service sector continues its outperformance, and the manufacturing sector its under- performance, in an environment of seemingly slightly above-potential growth. The signals around employment are quite mixed, which puts some focus on the next employment report. The consensus there has not yet formed. The Bloomberg survey still picks up only three guessers, with a median guess (2 of them) at 175, which is a little light when you factor in that there is supposedly some bounceback from the hurricanes factored in there.
Imbalanced, as the say — in favor of services
Data are to the November preliminary

