Back Quantitative

Quant Market in Numbers: Low Correlations Playbook Remains in Place – Fade Vol Spikes and Focus on Internals

Published on March 27, 2024

∙ Download the PDF Report

By

Dennis DeBusschere

Brian Herlihy

Sophia Wang

Kevin Brocks

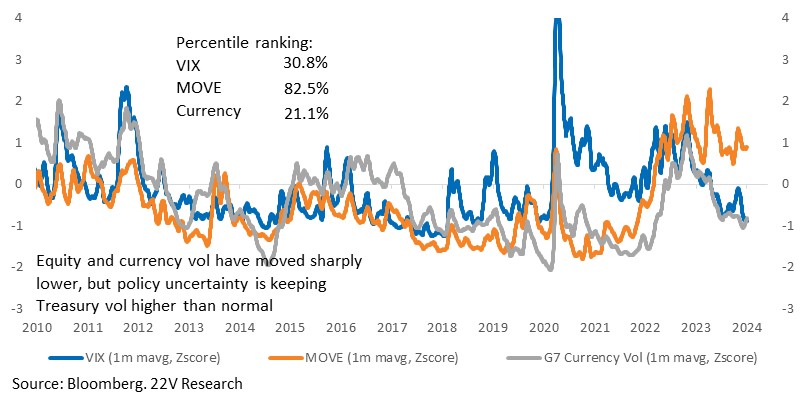
Equity and currency volatility both have dropped since last October as recession odds faded and a soft landing became increasingly likely. Lower asset price vol is to be expected as tail risk fades and the economic backdrop becomes less uncertain (HERE). Equity volatility will remain reactive to inflation releases, Fed speeches, and data that have a large impact on the policy outlook, but a lower level of vol than has been seen over the past few years should be expected.

Bond volatility remains elevated, reflecting uncertainty about the Fed rate path. Treasury vol has eased recently, and spreads are tight, apart from mortgages.

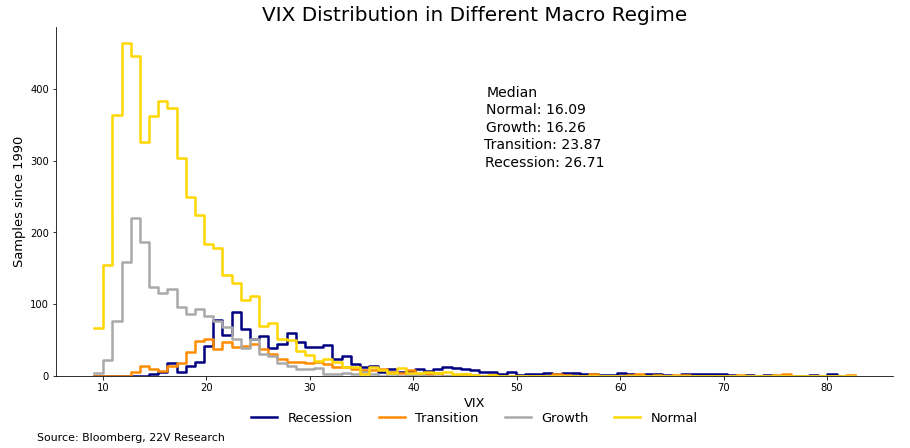
During historical economic expansions, which we sub-classify as Normal and Growth regimes, equity volatility has typically been around 16. In periods of heightened macro uncertainty, median VIX readings are around 23. Macro data that suggest stronger inflation or a crashing in growth could shift implied vol to a higher average level. Vol spikes in the absence of those data remaining opportunities to add to risk.

A graph of blue and orange lines

Description automatically generated

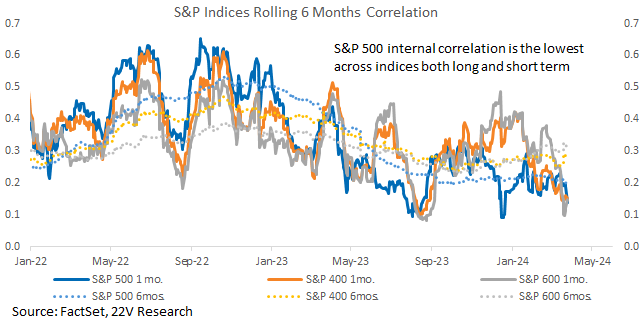
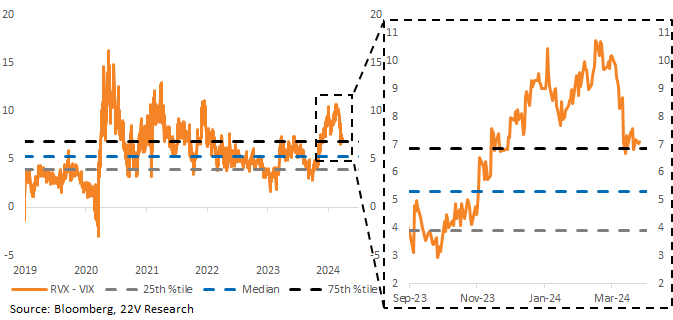
With lower volatility comes lower S&P correlations. S&P 500 correlation has been steadily declining across mid and large caps, and small cap correlations have fallen sharply since late February. At the same time the spread between Russell 2000 volatility and large cap volatility has narrowed rapidly to ~ its 75th %tile. Smaller caps are trading less as a group than they did following the 4Q rally, but there is still more opportunity to find relative out/under performers.

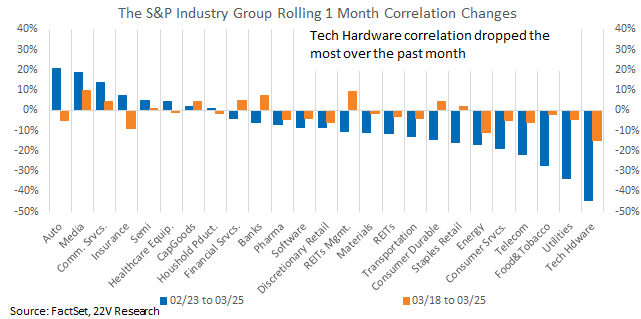
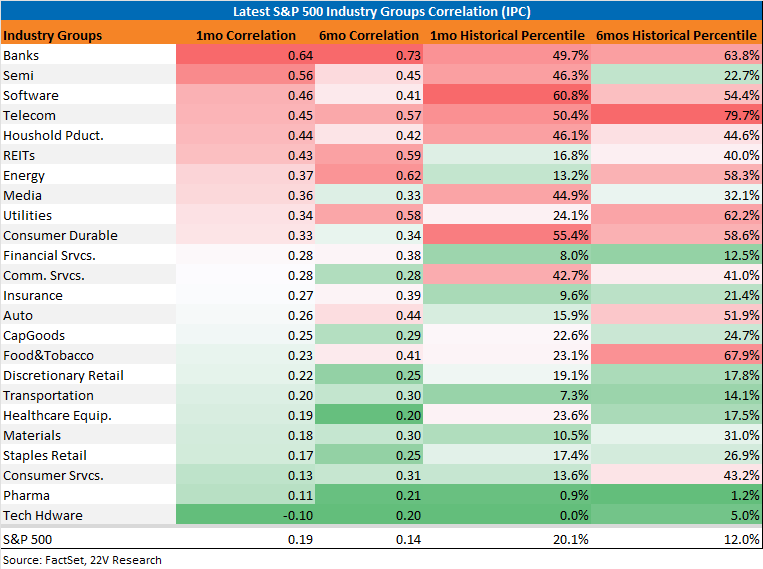
Within S&P industry groups, more than two thirds have seen lower correlations over the past month and week. Tech Hardware correlation dropped most recently, leaving its short-term correlation unusually negative. Within Semis and Software, correlations remain higher than most industry groups, but normal relative to history. Energy correlations have been dropping as well, making stock picking more effective within the group.

Volatility & Correlations Still Biased to Remain Low: Equity and currency volatility both have dropped since last October as recession odds faded and a soft landing became increasingly likely. Lower asset price vol is to be expected as tail risk fades and the economic backdrop becomes less uncertain. Bond volatility remains elevated, reflecting uncertainty about the Fed rate path. Treasury vol has eased recently, and spreads are tight, apart from mortgages. We expect equity volatility to remain lower than over the past few years (HERE). Spikes around major macro data releases (April 5th payroll, April 10th CPI) should be expected. Unless data changes the path of policy, those spikes remain opportunities to add to risk.
Equity volatilities vary wildly under different macro regimes. Under Normal and Growth regimes, which we are currently in, median implied equity volatility has been ~16. Median readings for Transitions and Recessions were >23. Fed rate uncertainty could shift equity vol higher IF data suggest stronger inflation or a crashing in growth, but the current trends support a low avg VIX.
A graph of different stages of growth

Description automatically generated

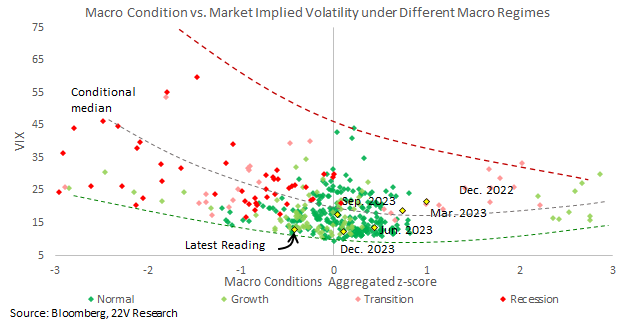
Macro conditions steadily improved over the past few quarters, reducing downside tail risk. Implied vol has gradually moved lower, reflecting reduced uncertainty as growth slowed and inflation shifted lower.
A chart with red and green dots

Description automatically generated

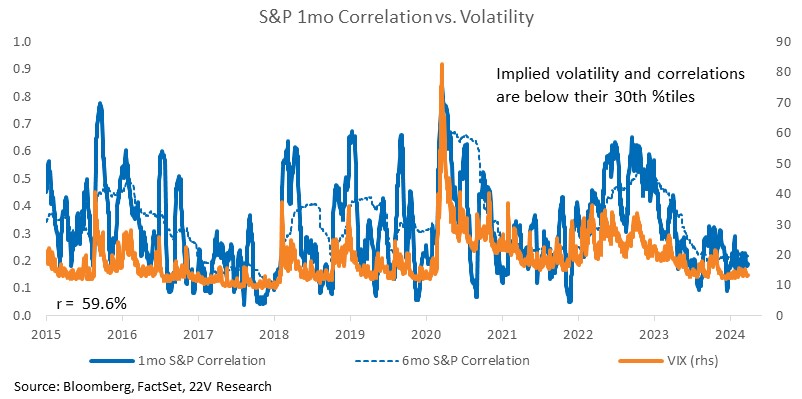
Low implied volatility is partially a function of lower correlations. Both the short- and long-term correlations are low today. With the S&P PE ~22x and yields rising, a lower risk premium is likely needed to drive the overall market meaningfully higher. Lower correlations mean more opportunity to outperform using factor, industry group, and stock selection.
Across different market caps, the S&P 500 now has the lowest correlation on a 1 month and 6 months basis. Short term correlations of small caps have dropped sharply since late February. Over that same time period, a simple strategy of buying profitable small caps and shorting unprofitable names (MS22LPSU Index on bbg) has gained 4.5%.
A graph of blue and orange lines

Description automatically generated

There was an extreme spread between large and small cap volatility earlier this year, measured through the spread between RVX Index and VIX Index). It peaked in mid-February. Small cap volatility dropped more than large cap volatility as well. That suggests investors are growing less concerned about shocks that would impact smaller caps as a group.
A graph of a graph with numbers and lines

Description automatically generated with medium confidence

Within the S&P industry groups, more than two thirds have seen lower correlations over the past month and week. Tech Hardware correlations dropped the most and are now exceptionally low. Auto, Media, and Communication Services correlations have increased but remain at normal levels. The bottom line is stock picking and factor analysis remains much more valuable than it has been over the past few years.
A graph of a company's company's company's company's company's company's company's company's company's company's company's company'

Description automatically generated

Tech Hardware correlations have turned unusually negative, suggesting more stock return divergence within the group and more opportunities for stock picking. The other two Tech industry groups – Semis and Software – still have relatively high correlations, but their absolute level are about at their normal level. Energy, which used to have the highest correlations are now lower as well, reinforcing the opportunities within commodity cyclicals.
A screenshot of a data

Description automatically generated

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.