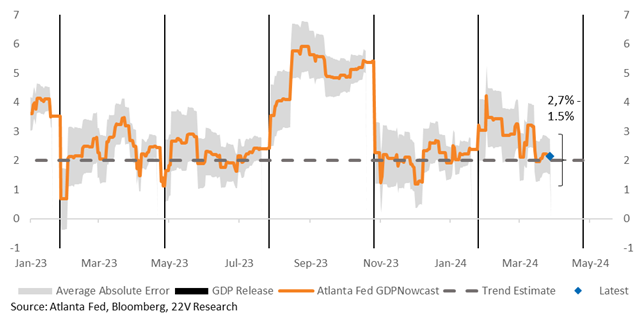
SUMMARY: It’s the end of the quarter and it’s slow, so we are marking some economic and earnings trends today. The New York Fed and Atlanta Fed seem to agree that real GDP growth is growing at an about trend 2% pace. That is a downshift and being driven by the end of the recent consumer boom. The housing and the production sides of the economy have improved, so we are not worried about a sharp deceleration in economic growth (Peter Williams has been all over this). We expect demand growth to remain around the 2-2.5% range and 2 or 3 cuts by the Fed. Our base case is basically priced at this point, so being long UST yields and positioning for tighter financial conditions make much sense right now.
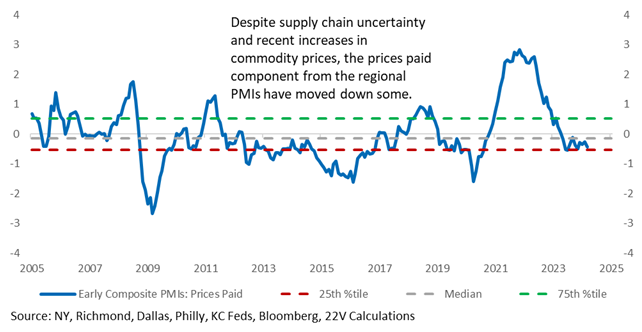
When looking at the prices paid components of the regional PMIs, it is interesting that prices paid have NOT accelerated, which many hawks thought WOULD happen, given supply chain uncertainty and recent commodity price moves. The opposite has happened. That reinforces that inflation getting stuck at too high of a level is a risk, but not the base case for positioning. We remain long Deep Cyclicals, GARP, and Small/Mid cap stocks.
Earnings Trends into Quarter End: EPS guidance has improved dramatically heading into 1Q reporting. Top Line guidance is not great, but margins continued to surprise to the upside last quarter (continuing a year+ long trend), beating estimates by 60bps. For now, some weakening of top line is being offset by higher profitability, translating into better EPS guidance.
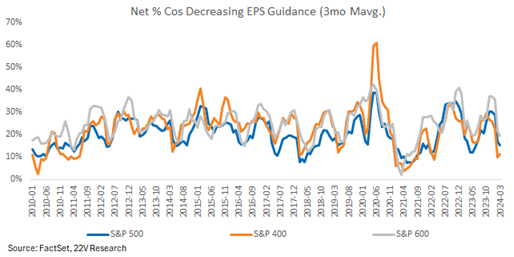
The Net % of companies decreasing EPS guidance has collapsed across market caps. Small and mid cap stock earnings bouncing back from last year’s weakness will be an important step in justifying the recent broadening out of market leadership.

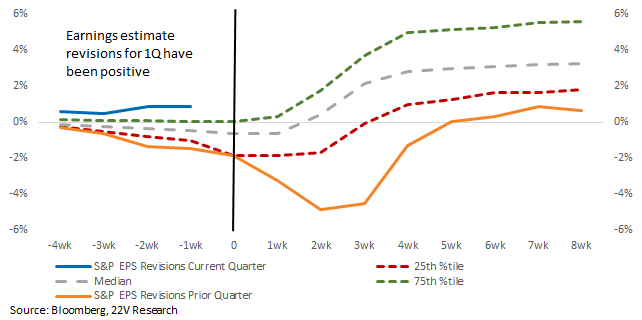
Revisions have been oddly strong heading into the start of reporting in a couple of weeks. There are two big takeaways from that. First, it suggests that analysts are starting to catch-up their forecasts to the improvement in macro conditions. Second, it means the bar for earnings season will be higher at the index/sector levels. That means a likely lower beat rate and better returns to positive surprises.
Full report below…
MARKET VIEWS: It is a slow week, so we are going to mark to market some data and earnings trends. First, as Gerard noted yesterday (HERE), “the New York Fed and Atlanta Fed seem to agree that GDP growth has decelerated to around trend (2%ish) in the first quarter….to the extent that the two regional banks provide detail on the components of demand, it looks as though most of the deceleration is (believed to be) due to the end of the earlier consumer spending boom.” Housing and the production side of the economy have improved, so we are not worried about a sharp deceleration in economic growth. We expect demand growth to remain around the 2-2.5% range and 2 or 3 cuts from the Fed. Our base case is basically priced at this point, so being long UST yields doesn’t seem to make much sense to us.
Looking at the prices paid components of the regional PMIs we have received so far doesn’t suggest much upside risk to inflation. Wages are a much bigger swing factor to expected core inflation and we will learn more next Friday. But the good news is that prices paid have not accelerated as many inflation hawks thought WOULD happen, given supply chain uncertainty, recent commodity price moves, etc., The opposite has happened. This reinforces that while the risk of inflation staying too high is very real, but not the base case.
Earnings & Sales Guidance into 1Q24: A large spread has opened between sales and EPS guidance. Net negative guidance toward sales remains at a high level and indicates some top line weakness. That seems consistent with the recent downshift in demand growth noted above. EPS guidance, on the other hand, has improved dramatically. Margins continued to surprise to the upside last quarter, beating estimates by 60bps. For now, some weakening of top line is being offset by higher profitability, translating into better EPS guidance.
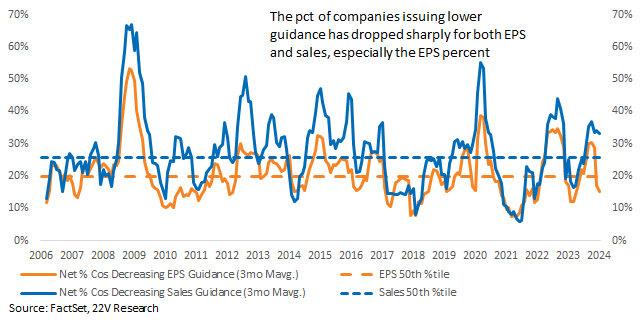
FYI – The Net % of companies decreasing EPS guidance has collapsed across market caps. Small and Mid cap stocks have clearly suffered from uncertainty around interest rates and growth trends. But small and mid cap stocks also had poor relative earnings last year. Small and mid cap stocks earnings bouncing back will be an important step in justifying the recent broadening out of market leadership.
Revisions have been oddly strong heading into the start of reporting in a couple of weeks. There are two big takeaways from that. First, it suggests that analysts are starting to catch up their forecasts to the improvement in macro conditions. Second, it means the bar for earnings season will be higher at the index/sector levels. That means a likely lower beat rate and better returns to positive surprises.
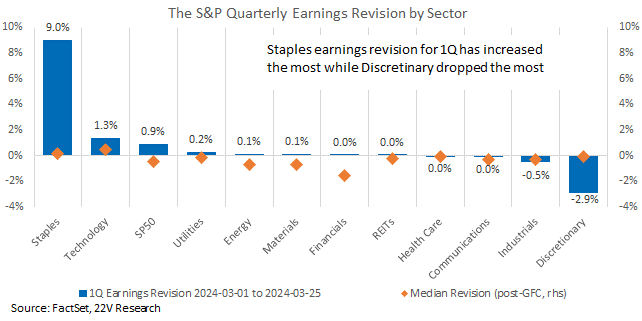
Staples 1Q revision increased the most while Discretionary dropped the most. Staples are a tough short right now given the revisions and lack of clear upside risk to UST yields. We are not long them either, but pressing the short Staple call, FROM HERE, seems more difficult. FYI – We have been negative on staples for a long time
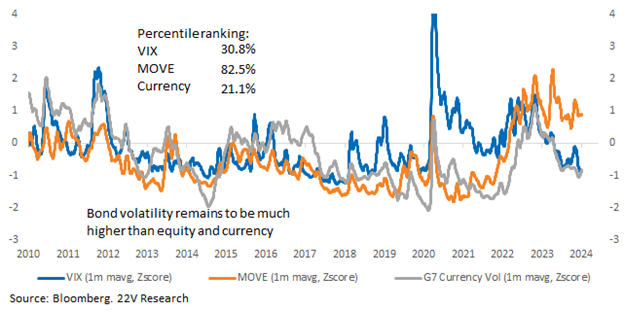
Bond Vol Still Elevated: Bond volatility has dropped some from its peak, remains high on the Fed cut uncertainty. We expect equity volatility to remain at the current relative lower range even as internal rotations (HERE) will continue, especially around major macro data releases (the latest April 5th payroll and April 10th inflation). If demand growth remains around 2% and the Fed can cut in 2024, bond vol is highly likely to decline significantly.