

Bottom Line: The burden of proof on inflation has shifted after a string of hot inflation readings. Investors will need to SEE March inflation data come back down rather than assuming it WILL come back down as seasonal factors fade, as many economists have suggested it will. A month ago, investors seemed more willing to wait and see if the seasonal influence would fade.
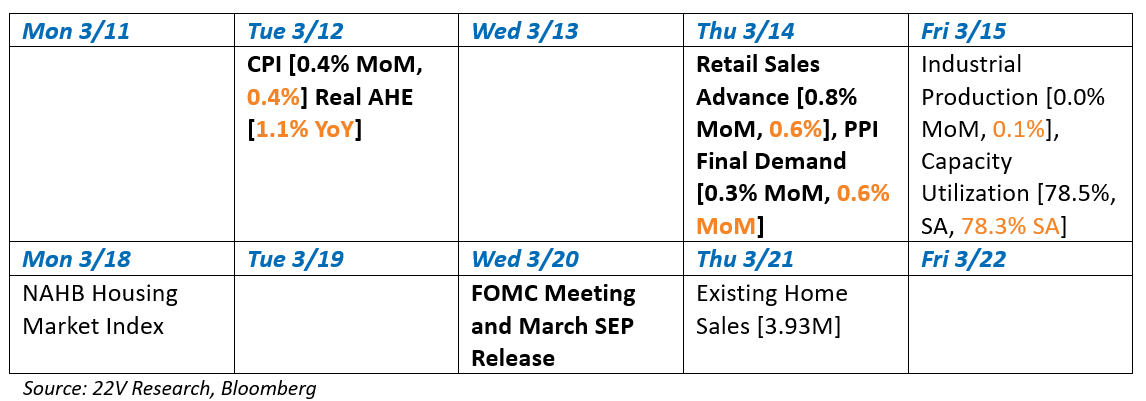
Relevant News: Seasonals were expected to have an upside influence on January and February inflation. The seasonal influence should be gone in March. March is a no-excuse month, inflation readings heading into that number are higher than expected.
Things to Watch [Consensus, Results]:
Economics: Details On PPI & Inflation are Less Disturbing, but Won’t Matter Until March
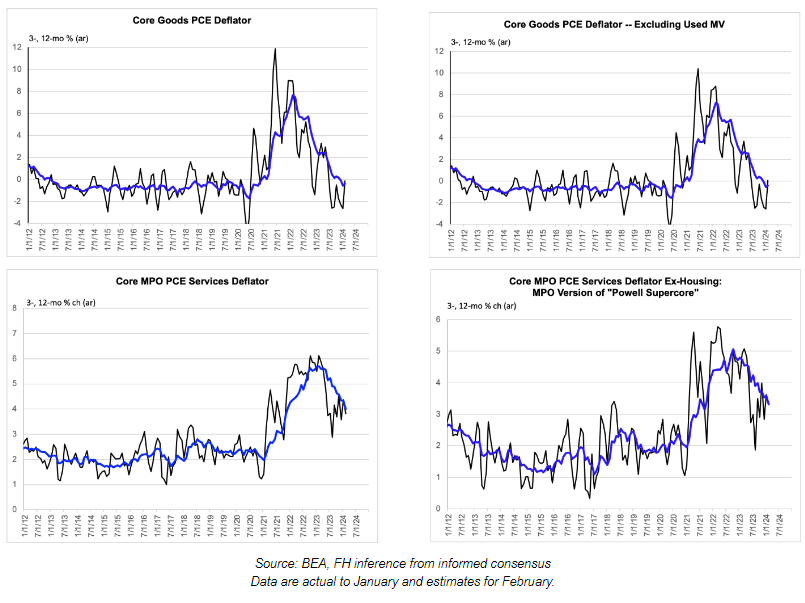
From 22V’s economist “The distribution of inflation across goods and services ex-housing was interesting this month, in the sense that all the strength was in goods. The fact that this month was dominated by goods is probably net dovish in isolation, because goods prices shed less light into the state of the labor market and are noisier, at least typically.”
On wages, the Atlanta Fed’s main indicator ticked down from 5.2% in January (where it had remained for six months) to 5.1% in February. That’s probably what consensus will focus on, but the version we like to look at actually ticked up 20 basis points. That points to the potential that the moderation in wage growth may have stalled, and that would be a problem. This is a slower developing theme though.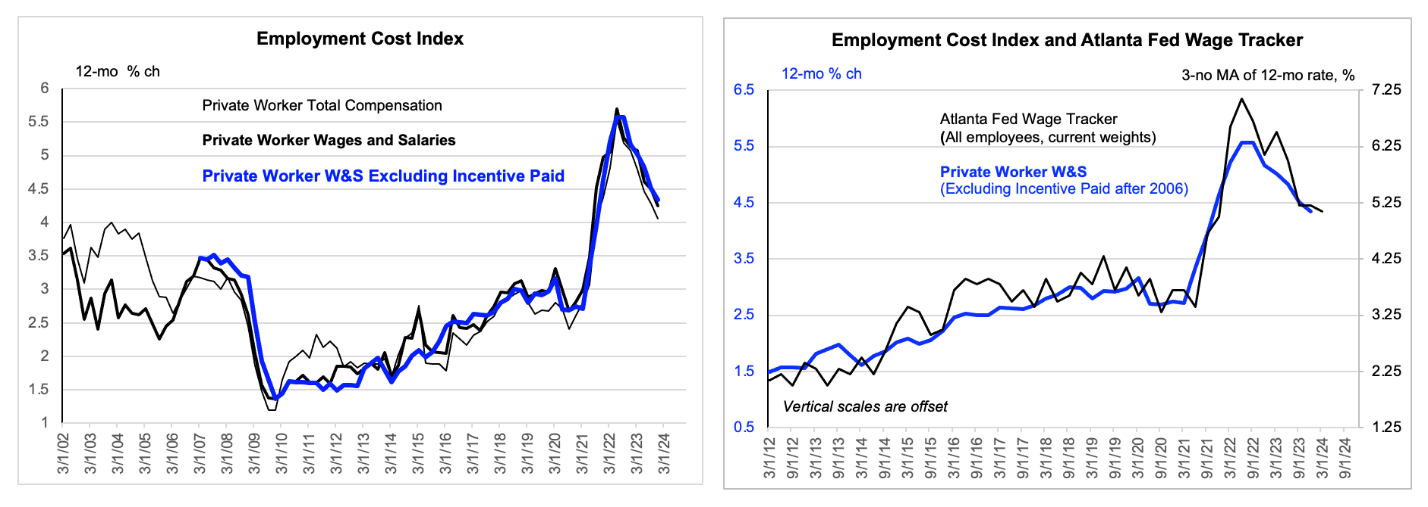 Source: Federal Reserve Banks of Atlanta and St. Louis (FRED), FH calculations. ECI and measures of core ECI are actual to December, recorded as Q4. The Wage Tracker is actual to February, recorded as Q1.
Portfolio Strategy: Burden of Proof has Shifted
We are not changing our call on 2-2.5% GDP growth and 3 cuts. The Atlanta Fed GDPNowcast moved lower again yesterday and consumer spending is now running at a roughly trend pace (see detailed report HERE). If economic growth stays around current levels, inflation data will likely be “good enough” for the Fed to start cutting. That will be good for small caps, risk factors and Value. Unfortunately, that call will be tough to monetize in the near term, given the shifting burden of proof on inflation.

Technical Analysis: Chart Spotlight: Copper
Copper – Daily w/ 50 and 200-Day MAs, MACD and Relative to Bloomberg Commodity Spot Index. Technical Score = 3; BASE / BASING since April 2023, above 50- and 200-Day MAs, positive daily momentum, strong relative price action vs. the Bloomberg Commodity Spot Index. A breakout above $4 would imply a target of $4.50. A definitive turn upward in the 50- and 200-Day MAs would make the $4.50 idea more important.
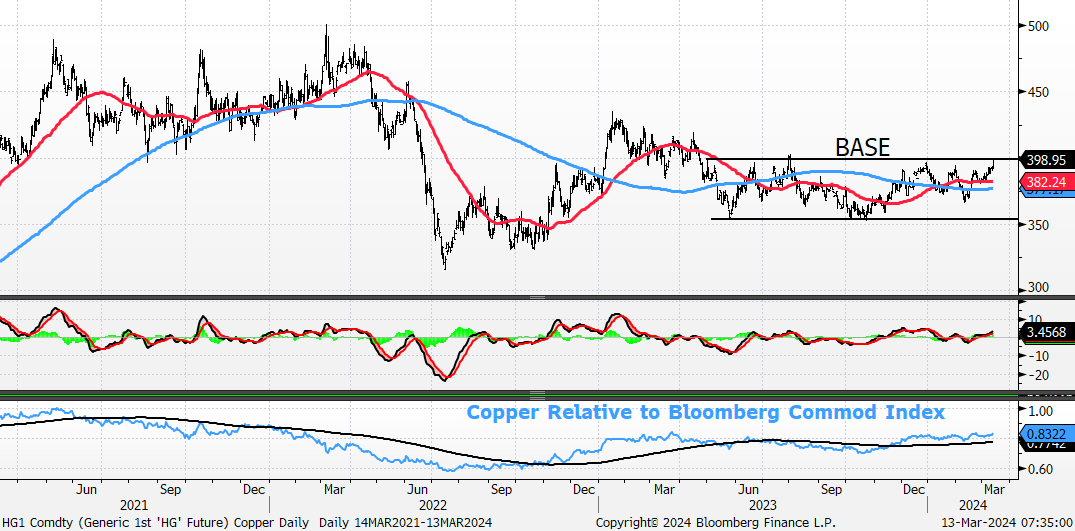
Source: Bloomberg, 22V Research
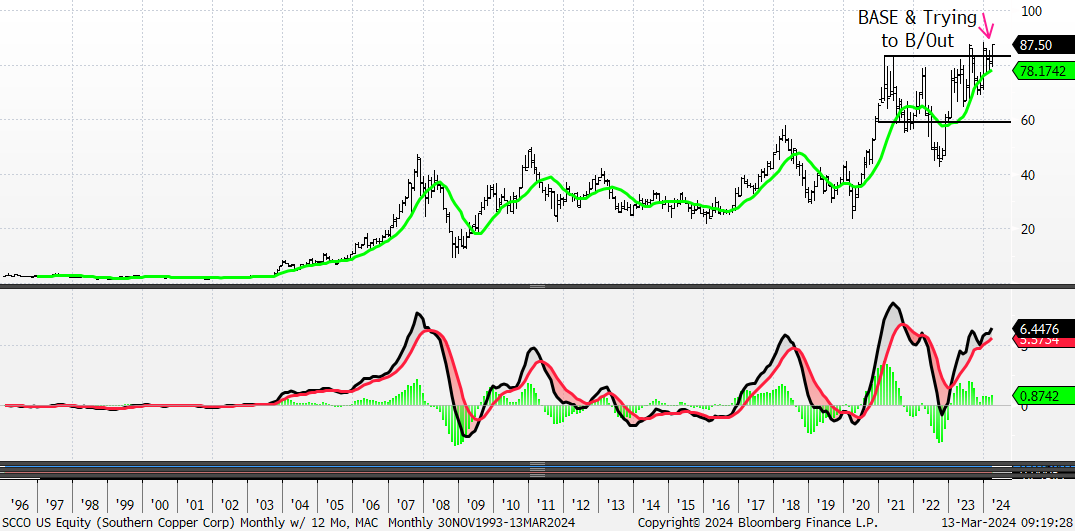
Within the equity space his favorite name is Southern Copper. Southern Copper (SCCO) – Monthly w/ 12-Month MA and MACD, Technical Score = 4.
Source: Bloomberg, 22V Research

