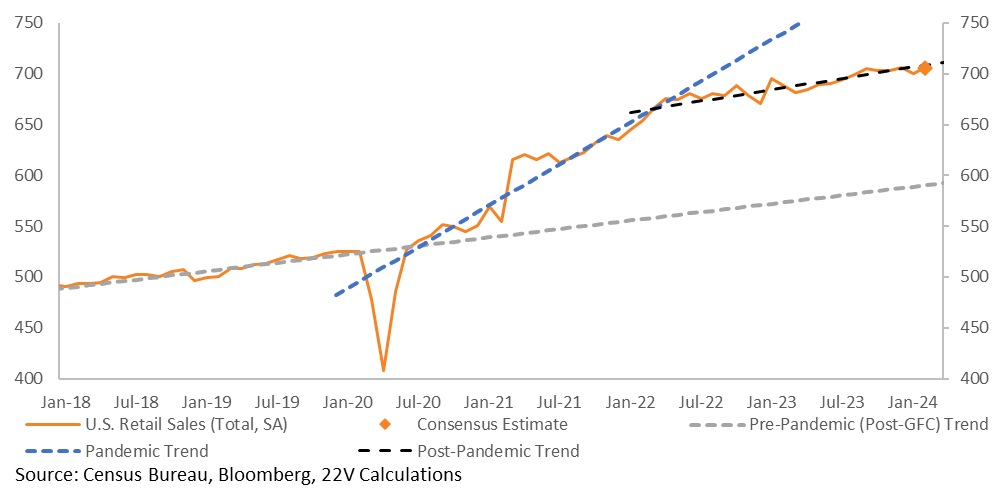
SUMMARY: PPI this morning will provide the final input into PCE estimates. Those PCE estimates will drive the conversation for the next few weeks. Last Jan PPI had a big one-off spike. If there is not a big decline, at least vs. consensus, it will be another point of inflationary concern. Retail sales (also this morning) will help refine estimates for real PCE growth. As of last month, real personal consumption expenditure growth looked to be in a 2-2.5% range following the retail sales miss. Assuming retail sales data are in line with consensus estimates today, that trend should remain. 2-2.5% real personal consumption expenditure growth is much less concerning, from a strong demand leading to higher inflation risk point of view, than the current 3%+ trend.
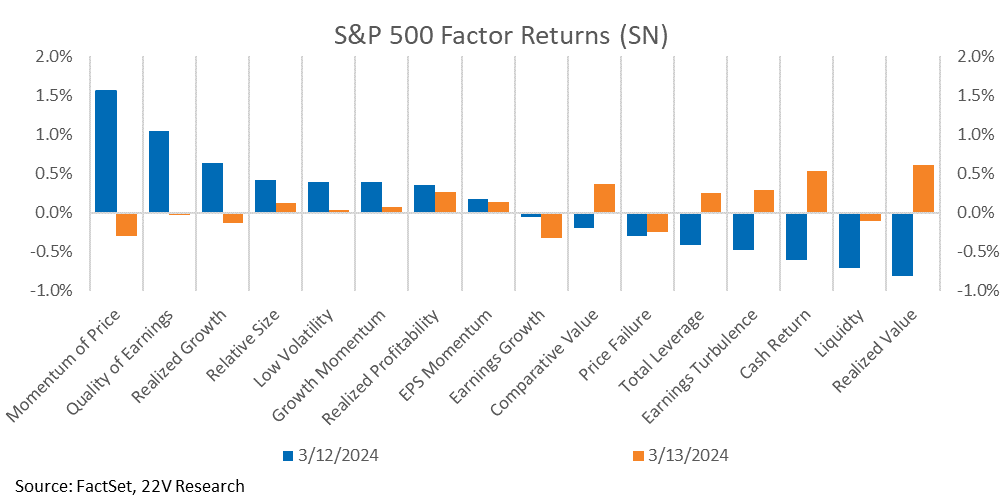
Yesterday’s market internals were a modest reversal of Tuesday’s CPI reaction, despite yields increasing again. Expect Price Momentum, small caps, and risk-on factors to be volatile but range-bound over the coming weeks. There are a few data points to get through before investors have a better understanding of how sticky, or not, core inflation will be.
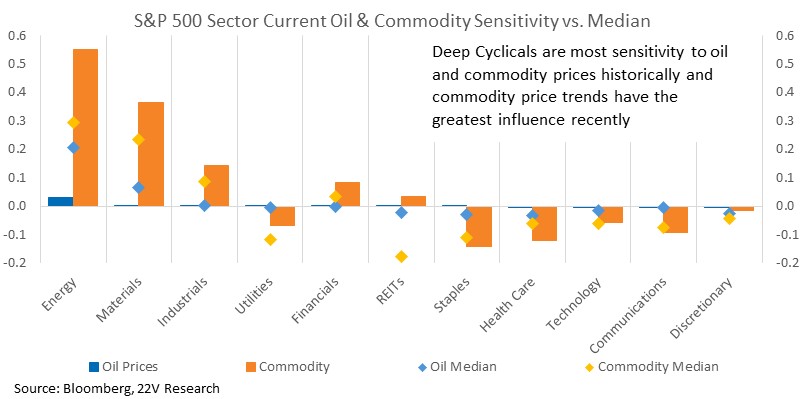
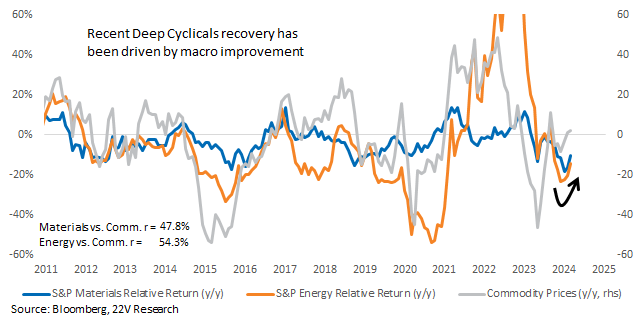
COMMODITY CYCLICALS: Deep Cyclicals are catching up to commodity trends (HERE). While inflation is stable/trending lower, as it is now, sensitivities to non-policy macro trends should increase. Deep Cyclicals are now outperforming Early Cyclicals YTD on an equally weighted basis. We continue to like an Energy NOW.
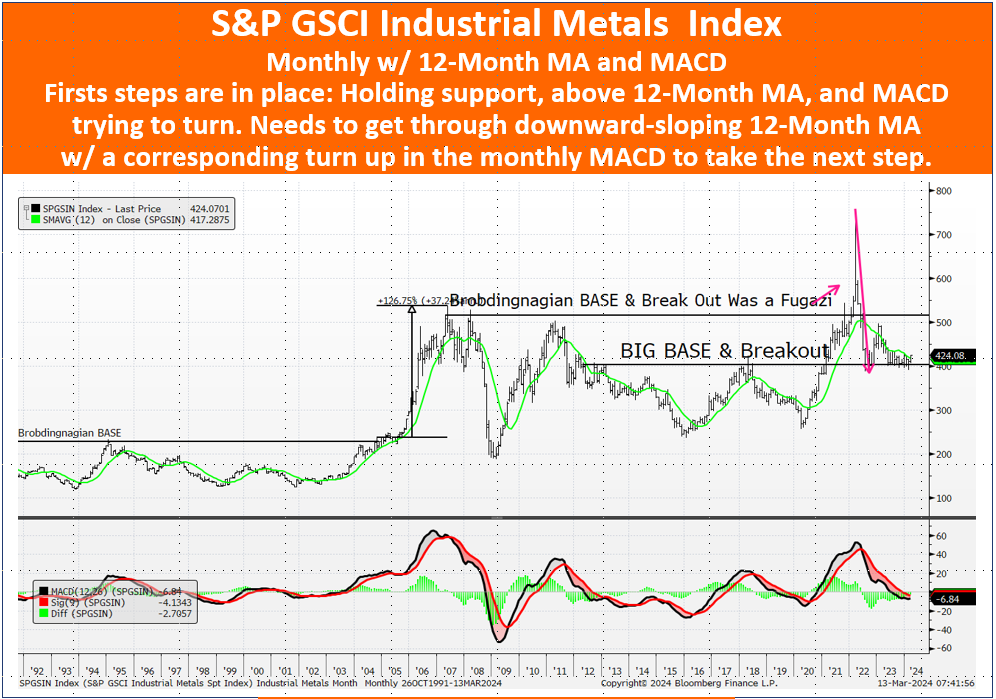
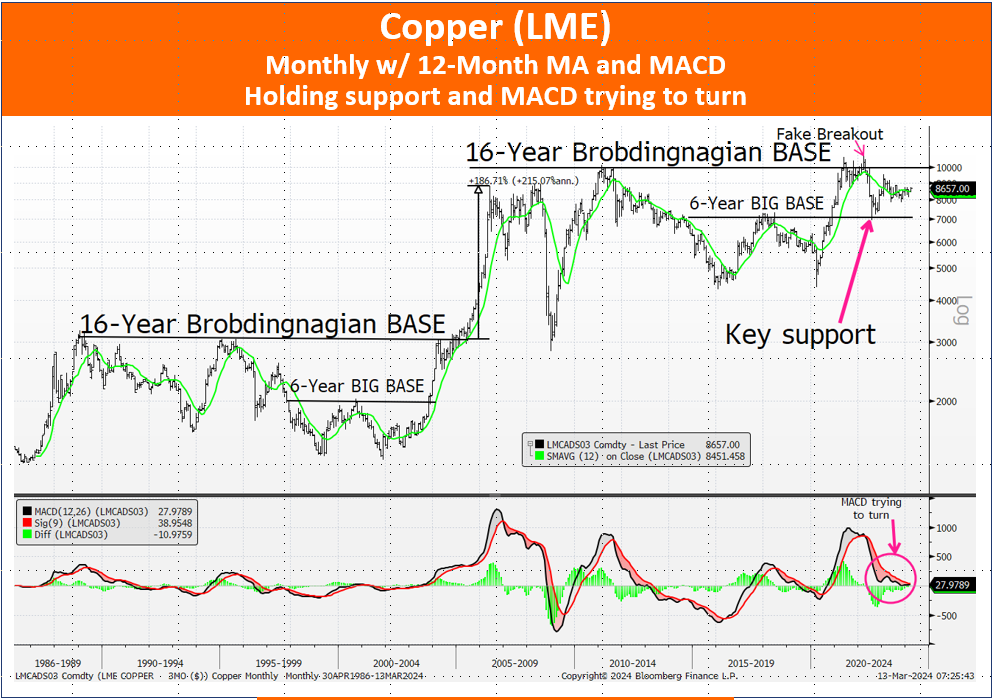
John Roque is bullish on industrial metals (see the full report below for details). Colin Fenton thinks the fundamental case is consistent with the quant and technicals. Per Colin, the mining equities don’t need to wait for further confirmation from the commodity.
Full report below…
MARKET VIEWS: PPI this morning will provide the final input into PCE estimates. Airfares and the portfolio management piece both directly flow into PCE. PPI final demand measures are best for the general inflationary read-through. Retail sales (also this morning) will help refine estimates for real PCE growth. As of last month, real PCE growth looked to be in a range of 2-2.5% following the retail sales miss. That’s a healthy level that does not imply recessionary tail risk.
Yesterday’s market internals were a modest reversal of Tuesday’s CPI reaction, despite yields increasing again. We expect Price Momentum, small caps, and risk-on factors to be volatile, but range bound, over the coming weeks. We have a few data points to get through before investors have a better understanding of how sticky high core inflation will be or not.
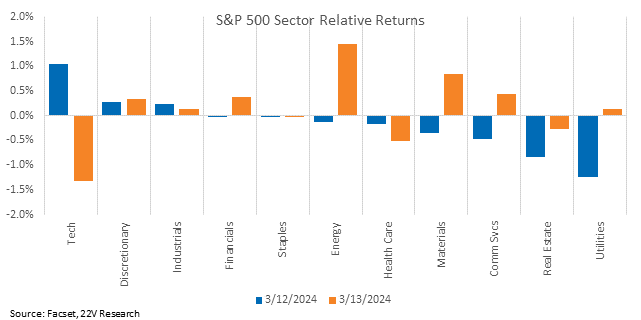
COMMODITY CYCLICALS: Deep Cyclicals are catching up to commodity trends (HERE). While inflation is stable/trending lower, as it is now, sensitivities to non-policy macro trends should increase. This week’s inflation data shifted rate cut odds further out of May and into June, which isn’t a scene changer for recession tail risk. Economic data has been consistent with lower macro influences (not necessarily pre-COVID low, but lower than the last few years).

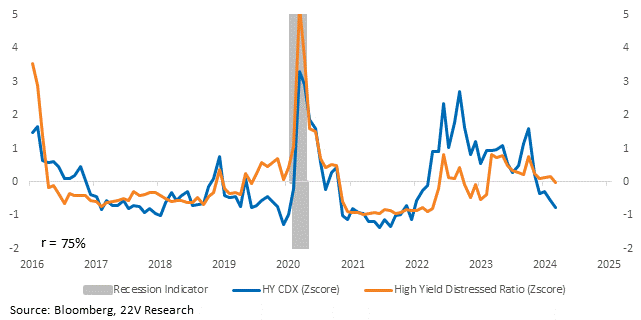
HY CDX keeps on tightening and the percent of high yield trading as distressed (>1000 OAS) keeps on declining. This is not consistent with a higher recessionary tail risk. Equity internals are very sensitive to the length of the economic cycle, and the incremental odds therein, but deep recessionary tail risk is still not being priced in.
John Roque is bullish on industrial metals…
…and copper, which looks strong relative to Bloomberg’s Commodity Spot Index and is holding support on its own. FYI Colin Fenton thinks the fundamental case is consistent with the quant and technicals. Per Colin, the mining equities don’t need to wait for further confirmation from the commodity.
Interesting that the sensitivities are even higher than normal.