Back Economics

The received nonsense around QE has shifted, probably helpfully

Published on March 13, 2024

∙ Download the PDF Report

By

Gerard MacDonell

Former New York Fed chief Bill Dudley has an opinion piece on Bloomberg arguing that it will be important where the Fed decides to stop its quantitative tightening (QT) (article HERE).  The piece argues that the main objective here is to avoid undershooting the level of reserves that would allow the Fed to hit its objectives for the money market: the target funds rate, target SOFR, etc. Dudley was ultimately and earlier effectively in charge of the trading desk at the New York Fed and so he is particularly well positioned to comment on these issues.  

His views are consistent with my intuition which must come as a relief to him, although I suspect he overstates the drama around the need to be particularly careful sticking the landing for the balance sheet. That would be a PR issue, not an economic or even enduring financial issue. And it is not really like “landing an airplane without an altimeter,” unless we imagine an airport at which you are allowed to touch the runway five times and then pick which touch was the most comfortable. On the technical issues, he knows much more than I do. 

What attracts me to his piece is his insistence that the effect of QT on the bond market will be trivial. So now they tell us! Guys, sorry to break it to you but your obsession for the past decade+ has been a distraction.   Revenge is a dish best served cold, so I have come to the table 20 times with the same course, just to make sure, as you may have noticed.  Anyhow, he has the right conclusion.

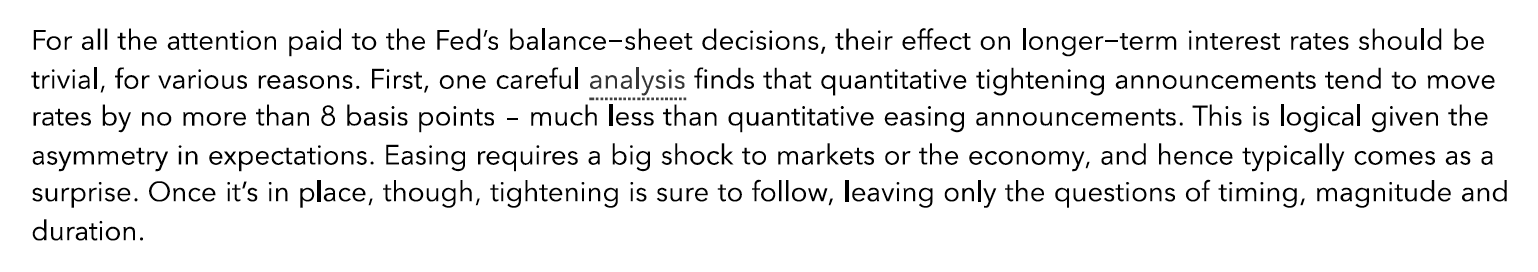
But the received reason why QT does not matter is the new source of hilarity.   The reason is that QE and QT work “asymmetrically.”Ahhhhhhh. I see. What a beautiful immunizing stratagem.  QE was important, but like God it works in mysterious ways!  Here is Dudley with the new riff going around:
Source: Bbg, Dudley, as linked above

I will grant that the announcement effects this time around will be minimal, even if QE / QT were important to yields, which it is not. But the reason is that this stuff is so well telegraphed by Fed commentary, not that QT follows QE as reliably as night follows day.  In fact, if that false claim were true, QE itself would be largely impotent, which it is, but just for a different reason.

The real debate here is not the announcement effects, but the enduring effects. And to see why this new claim is nonsense, consider a situation where the Fed surprise announces $3 trillion of QT. What would be the effect of this on yields? Short answer: not much, beyond the immediate announcement effect, as we have seen.  But the argument presented above is that once the QE announcement is made, then QT is sure to follow with the timing being only a “trivial” consideration, as a simple matter of “logic.” Really? I thought the Fed leadership had repeatedly insisted that it was the expected path of the balance sheet over time, and not its spot value, that was important to the bond market. Nope, the new story is that it would not matter to markets if the $3 trillion were withdrawn tomorrow or in 10 years. So good.

Dudley concludes by pointing out that one value of shrinking the balance sheet now is that it creates “room” for renewed QE later.   But when the Fed next does QE, it will be “trivial” how long the Fed suggests the injection might last. I will bet you 3 trillion dollars they would not characterize it that way in real time.  If these folks (i.e., central bankers) did not have the ability to ruin your quarter, your year and your career, through other means, they would be laughed off Wall Street for this nonsense. And the media hang on every word, although it is not quite as cringe inducing as how they cover Jamie Dimon.

Anyhow, bottom line: QT won’t matter much for yields, because QE did not matter much for yields. We can keep it simple, without going into these gymnastics.

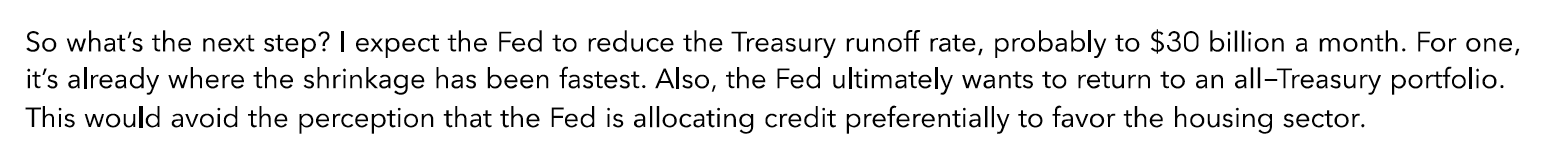
Totally off topic, but this was also very good:
Source: Bbg, Dudley, as linked above

The Fed would not want to leave an impression that mortgage purchases were designed to help the mortgage market.  And I think Dudley is smart. As I have said before, the balance sheet is intellectual kryptonite. Its main effect is to turn observers of it into fools. 

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.