

Bottom Line: S&P gains have been PE driven this year, and the internal rotation taking place now does little to drive the overall market higher. Last week, the S&P was down slightly, but the equally weighted index rose 90bps. Investors getting comfortable with an extended economic cycle is critical for the equally weighted index to continue outperforming, small caps to work, and risk-on factors to move higher. Economic data last week was consistent with higher odds of a longer economic cycle.
Relevant News: An accumulation of hotter than expected CPI data points are needed, specifically driven by Powell’s preferred Core Services Ex Housing, before markets start pricing in much higher odds of zero cuts. That seems unlikely unless core CPI is much stronger than expected.
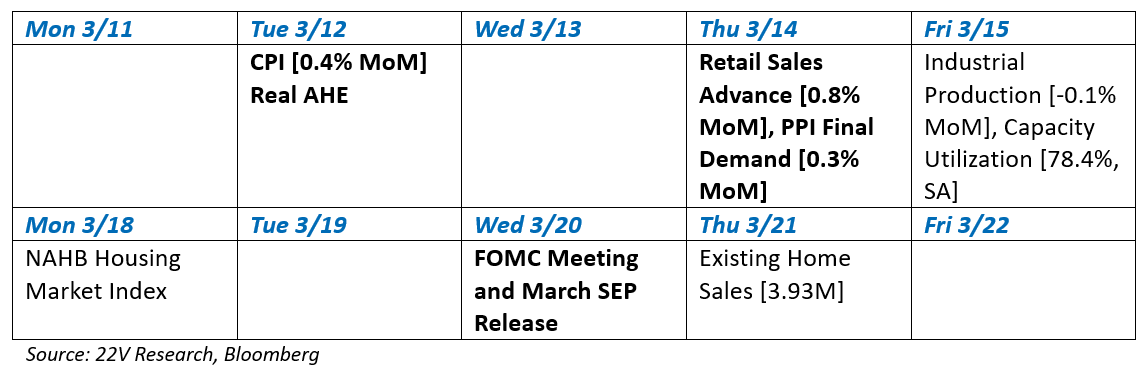
Things to Watch [Consensus, Results]:
Portfolio Strategy/ Economics: Increasing Odds of an Extended Economic Cycle
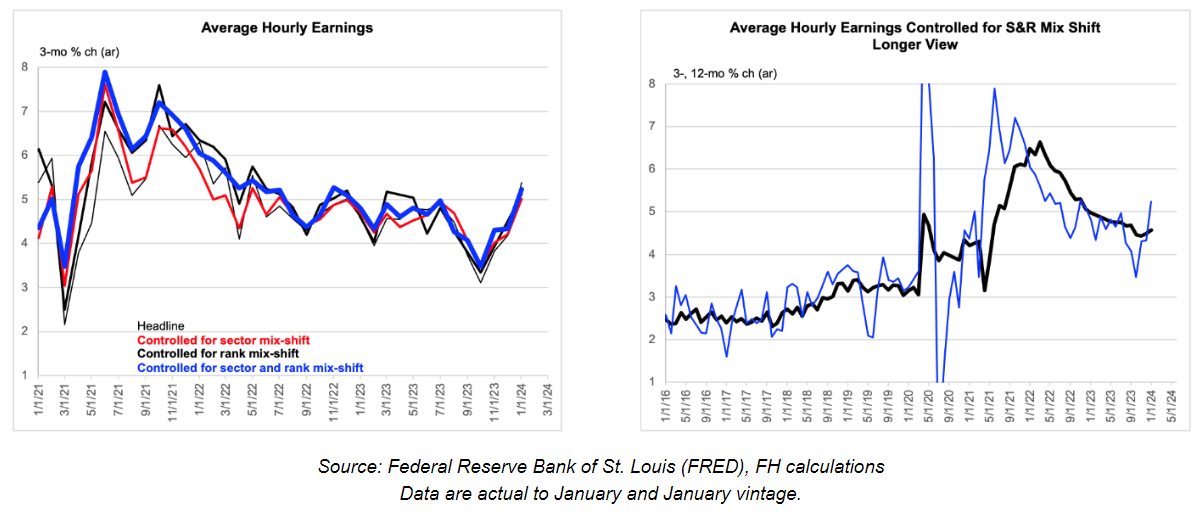
Wage growth is still too high for the Fed, but the trends in broader employment data and underlying demand suggest more downside than upside risk to wage growth moving forward (HERE). To be fair, it’s still a close call on how the wage growth/core CPI picture will play out, but as 22V’s economist has highlighted, given the dovish payroll report, 0.3m/m (i.e. including a low 0.4 as it prints on BBG) on Core CPI might not kill May cut odds on its own (currently 25%). A bit on the hotter side would lead toward a June cut. An accumulation of hotter-than-expected CPI data points is needed, specifically driven by Powell’s preferred Core Services Ex Housing, before markets start pricing in much higher odds of zero cuts. That seems unlikely unless core CPI is much stronger than expected.
Quant: 4Q Post Earnings Drift
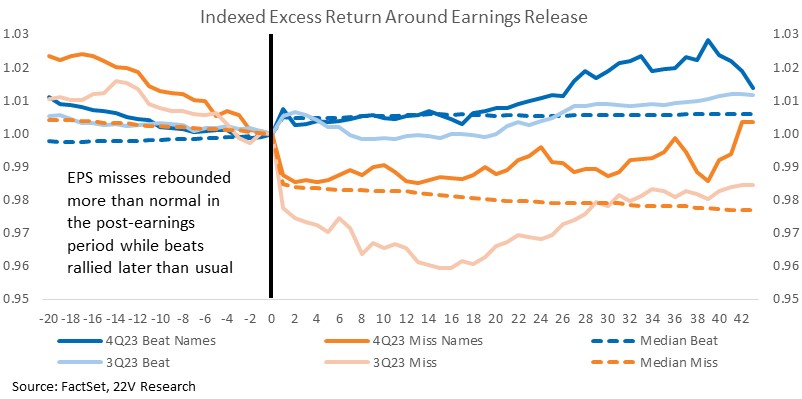
Continuing the pattern of the past several quarters, 4Q earnings were MUCH stronger than expected. Upward revisions were broad and strong, but names that beat estimates were rewarded less than normal and names that missed underperformed more than normal (details HERE). Post earnings drift, the lingering impact of earnings surprises, was more pronounced than usual though. During 4Q reporting, beats continued to gain, peaking ~40 trading days after earnings releases. Misses saw typical declines but rebounded more than normal.
Though earnings growth for Deep Cyclicals (Energy, Industrials, Materials) were weak (HERE), the group had the best post earnings release performance. Early Cyclicals (Tech, Discretionary, Comm Svcs) post earnings drift has been weaker than in 3Q and lagged even Defensives. The outperformance of Deep Cyclicals is consistent with the steady improvement of the macro backdrop and the catchup trade as policy vol eases.

Technical Analysis: Technical Scoring on S&P Tech Sector
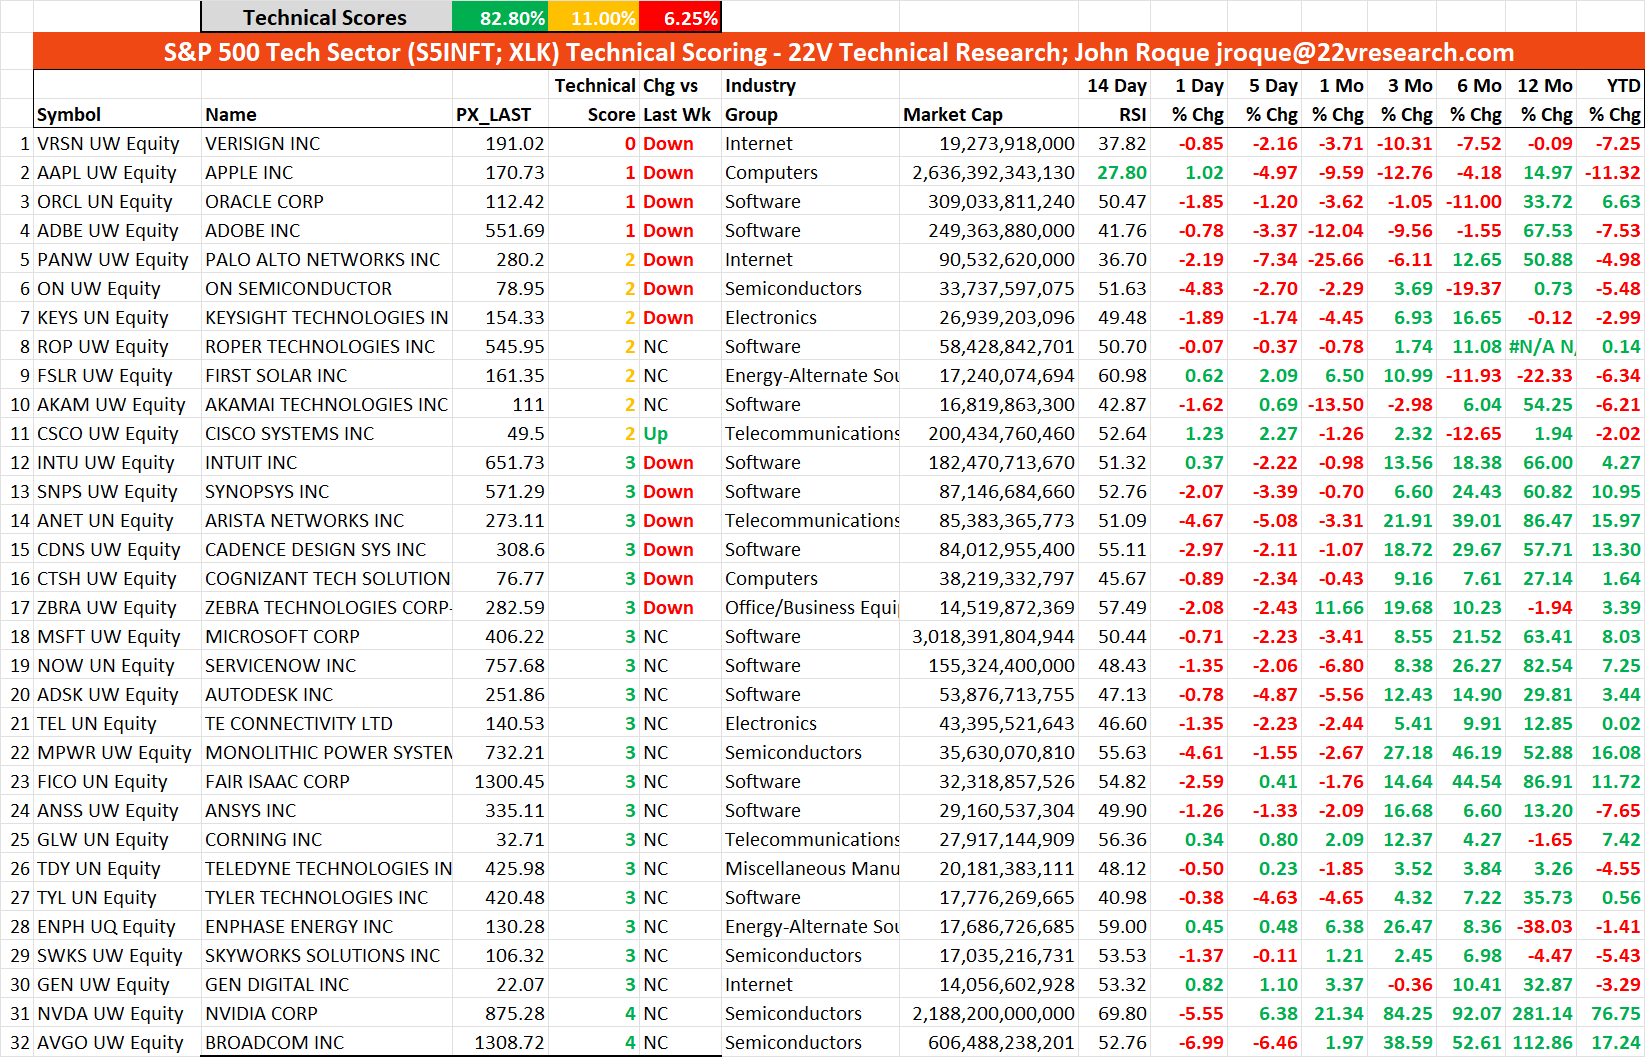
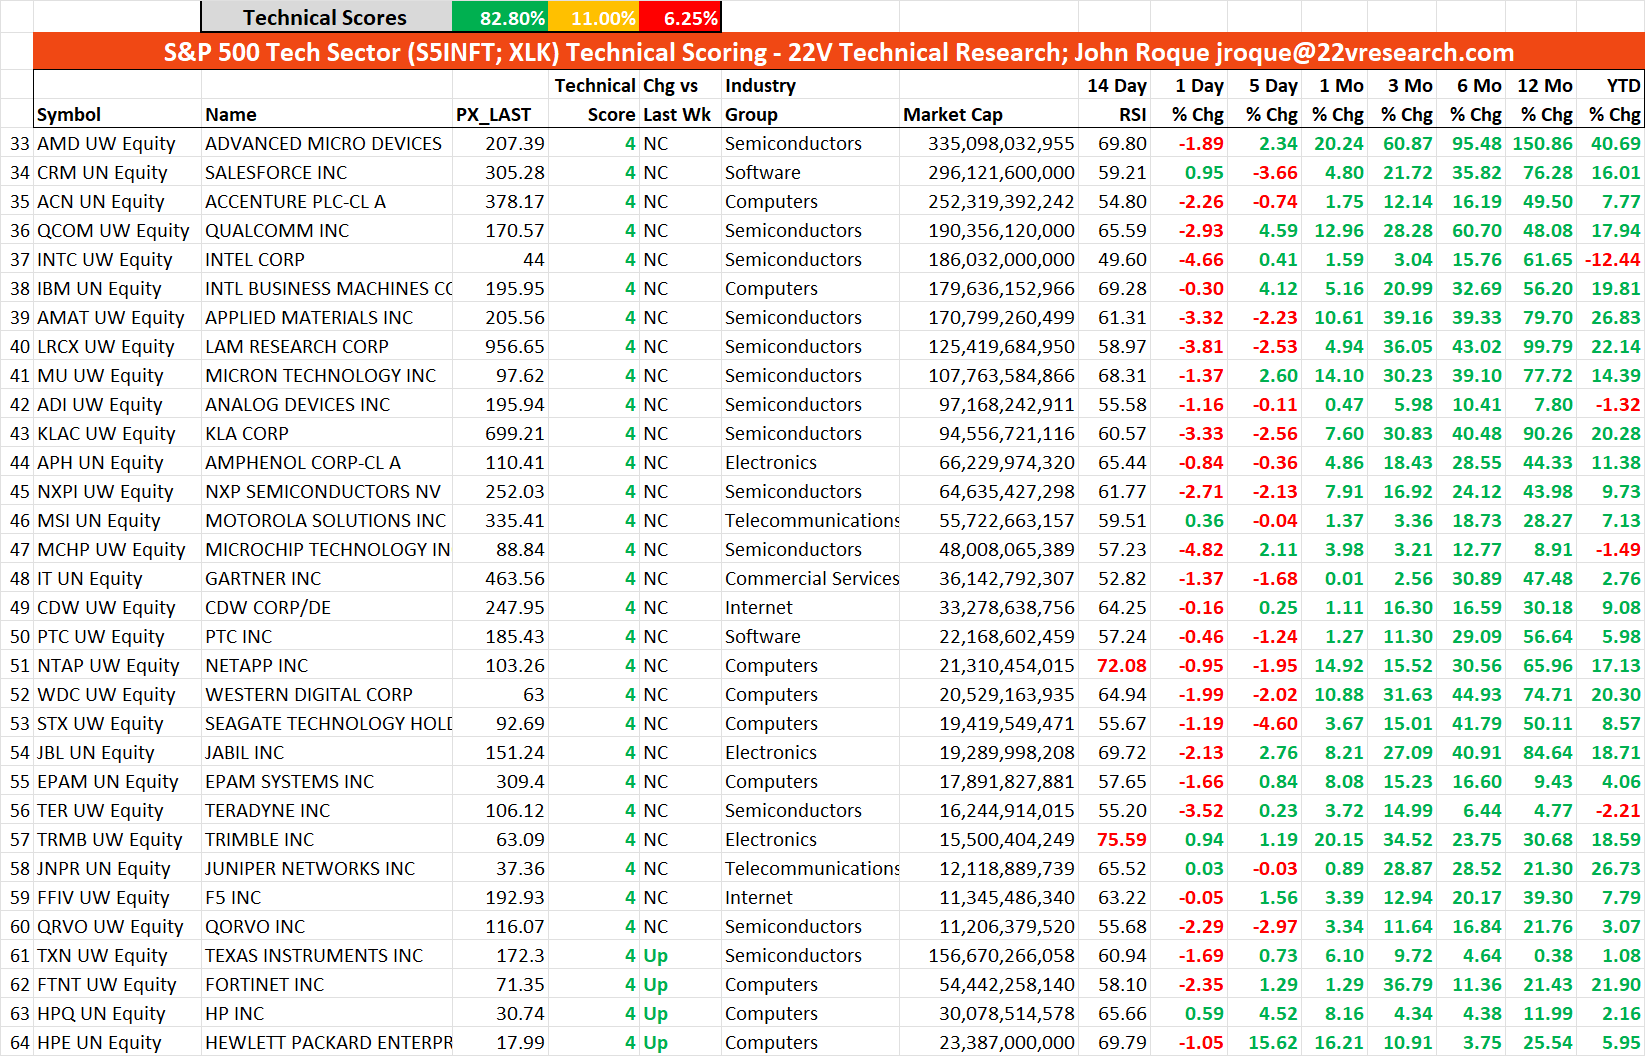
What follows is the overall Technical Scoring for the S&P Information Technology Sector (XLK). While the overall Scores are still stellar with 83% Good / Strong and only 6% Weak, the Scores are presented to focus on the Change vs. Last Week column because 20% of the stocks had Scores move lower in the last week. In addition to expecting lower levels for AAPL, GOOGL, and TSLA, 22V’s technical analyst thinks VeriSign (VRSN) has been bearish and investors should be ready for Oracle (ORCL) and Adobe (ADBE) to move down, too. Also, in his view, it seems right to say that Palo Alto Networks (PANW) is on its way to retesting its upward-sloping 200-Day MA with key support @ 250. PANW closed @ 280 on Friday. ON Semi (ON) is a better sale on my work with risk to Oct low; it closed just under 79 Friday. Intuit (INTU) looks like it can follow Adobe and that’s not a compliment. And, lastly, Cognizant (CTSH) has big resistance @ 80.
 Source: 22V Research
 Source: 22V Research

