Back Economics

Market now arguably prices fewer rate cuts than Fed as modal view

Published on March 1, 2024

∙ Download the PDF Report

By

Gerard MacDonell

Bloomberg’s WIRP function suggests that, abstracting from term premia, the mean of the probability distribution has the Fed cutting the funds rate just over 3 times (assuming 25 bps a pop) during 2024.  On this basis, we might say that the market is still slightly ahead of the Fed.  Of course, the Fed is not guiding, but you know what I mean.
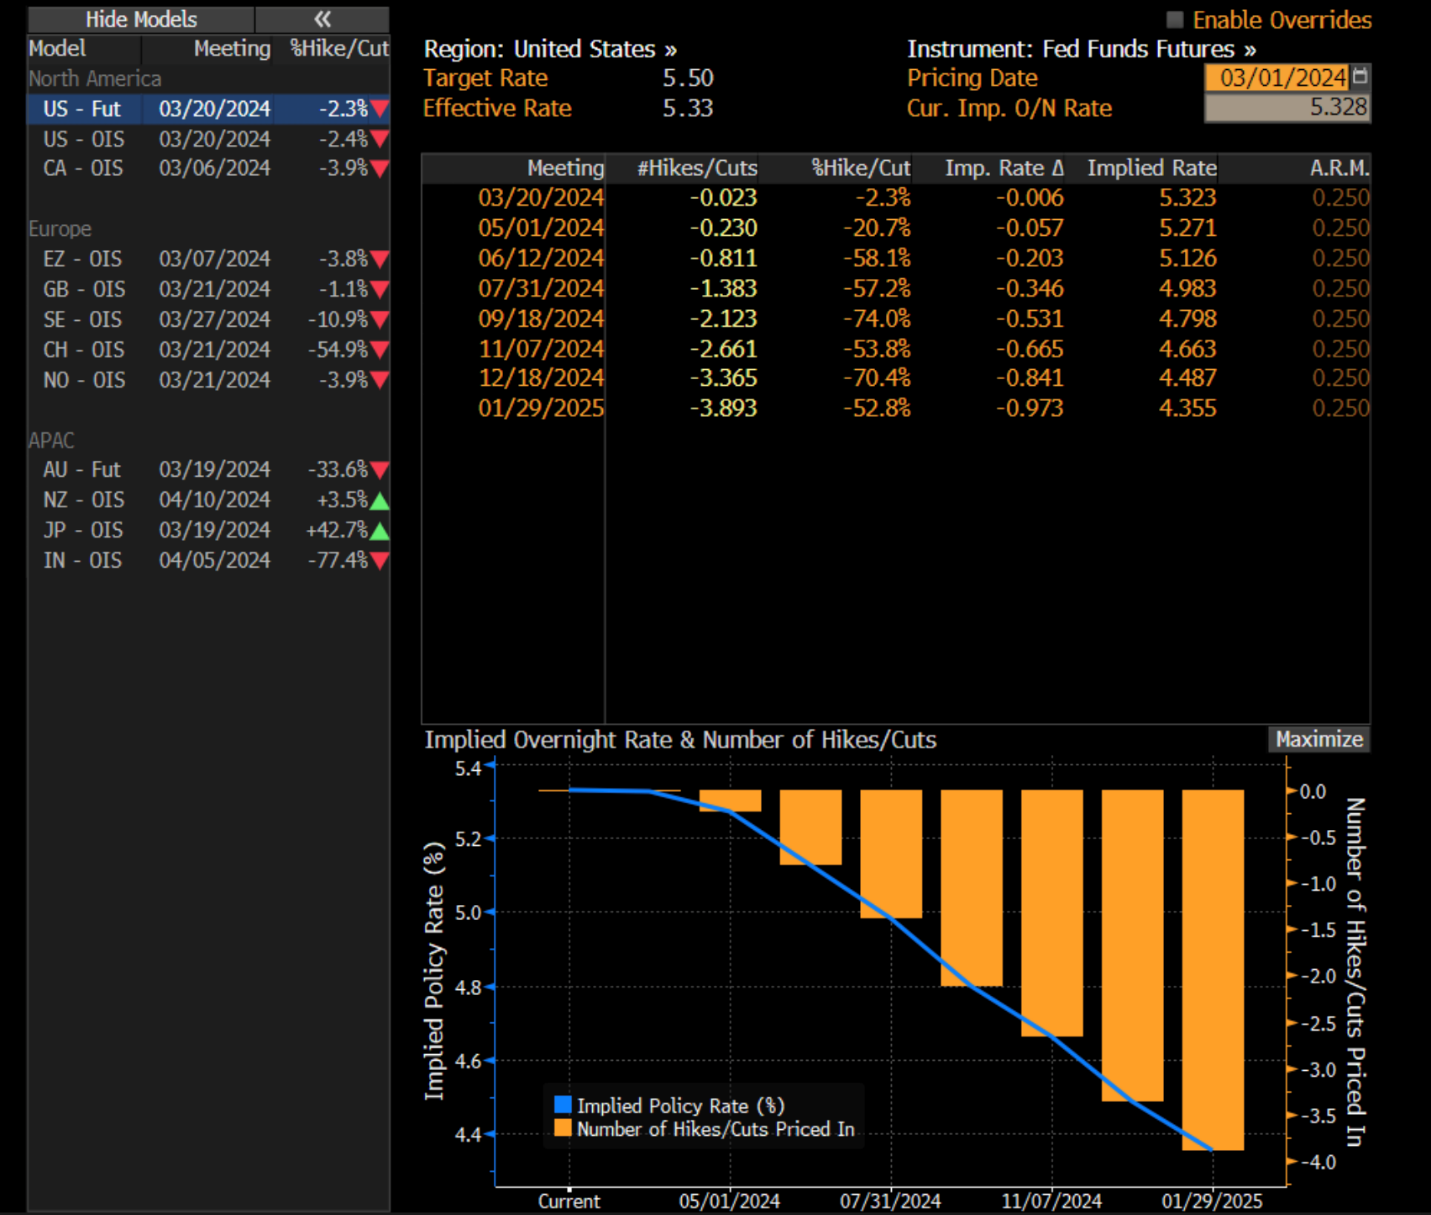
A screenshot of a computer

Description automatically generated
Source: Bloomberg

The problem with the WIRP function, though, is that it traces out the mean of the probability distribution, not the mode, again abstracting from term premia. But what the Fed writes down in its dot plot and talks about in speeches relates to the modal views among FOMC participants.  So, to do an apples to apples comparison, we might want some proxy of what the market prices as the mode.  Because the skew in rates is to the left, we have reason to suspect that the mode is higher than the mean and therefore “prices” less rate cutting.

This evening I have been familiarizing myself with that Bloomberg function that allows us to trace out the entire probability distribution for the priced funds path, which relies on options, not just futures.  That function cannot identify the mode per se, and what is being forward priced is the 3-month SOFR rate, rather than the funds rate at specific Fed dates. Still, we can get a good sense.  For example, the gap between the SOFR rate and the 50th percentile of the distribution is about 20 bps in late 2024.  The table under the attached chart below implies a slightly narrower spread, but that is because it is comparing one figure for the beginning of December and another figure for the end.  If we do apple to apples time wise, the gap is about 20 basis points.  Indeed, the SOFR futures strip runs entirely below the 40th percentile of the distribution implied by options prices.  If I had to guess, I would say the 35th percentile overlaps with the mean, implying leftward skew.

If we brazenly take the 50th percentile, i.e., median, to be what the market considers as most likely, i.e., mode, then we need to add about 20 bps to the central rate in WIRP function for the end of the year.  And that would map to fewer than 3 funds rate cuts by the end of the year as the priced modal case.  (Incidentally, ignore the distinction between Feb 29 and March 1 pricing. The Feb 29 is apparently the close and what they call March 1 is roughly live.  I think.)

A screen shot of a computer

Description automatically generated
Source: Bloomberg

I like the idea of using Bloomberg data because many clients can follow along by using the same utility, which is quite flexible.  Just follow the instructions I sent out earlier today.  Also, Bloomberg does not impose the same long reporting lag that we find with the Atlanta Fed utility.  My problem is that I cannot actually vouch for the numeracy of the Bloomberg analysts. I assume it is high, but this is not my area.  Having said that, this does fit with my suspicion that the mode is to the right of the mean and that markets may actually now have a central case (i.e. mode) that is no more dovish than what the Fed is suggesting.  I am happy to be corrected by folks closer to these issues. But I thought this was somewhat interesting. 

I think the barrage of seemingly coordinated hawkish Fed rhetoric over the past couple weeks has helped to deliver this view, rather than, say, markets coming to my sense of the economics involved here.  At the margin, that would weaken the case for being short rates here, if true. But it is not something I can prove. 

As an aside, I would mention that I learned of this utility from Bloomberg’s David Wilcox who wrote an opinion piece  leaning into the view that the Fed might actually hike rates.  The 90th percentile actually slopes up from here, he noted.  But my interpretation is the opposite of his. The skew is clearly to the left, not the right, as not even the 80th percentile slopes up.  So, I believe the more relevant point is the one I emphasize.  The market may have got slightly to the hawkish side of the Fed as the mode.

Comments most welcome. I am new to all this. 

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.