

SUMMARY: Even though 80-85% of the inputs into Core PCE come from CPI/PPI, making out of consensus readings much less likely, yesterday’s PCE reading was an inflation data point that didn’t come in obviously hawkish. That helps explain the relief rally after the PCE release. The much larger market moving numbers are Payroll on 3/8 and CPI on 3/12. Wage growth needs to slow more (the 0.3 MoM expected would be ok), and CPI needs to show that January effects (some companies’ propensity to wait until the new year to raise prices) were a real issue.
For now, investors are assuming a decline in inflation and 3-4 rate cuts. 10yr yields are assumed to be higher on better economic growth prospects. That would change (i.e. inflation driving 10yr yields) if 1) wages remain sticky at too high of a level and 2) January effects are proven to not be the main driver of last month’s CPI increase.
67% of the investors we surveyed yesterday think 10yr yields will end March higher (HERE). The median expectation for the 10yr yield at the end of March is 4.35%, and the median for the end of June is 4.17%. 30% think the 10yr yield could reach the 4.4%-4.6% range by the end of March. Investors appear to be set up for hotter, but not too hot, data over the coming weeks.
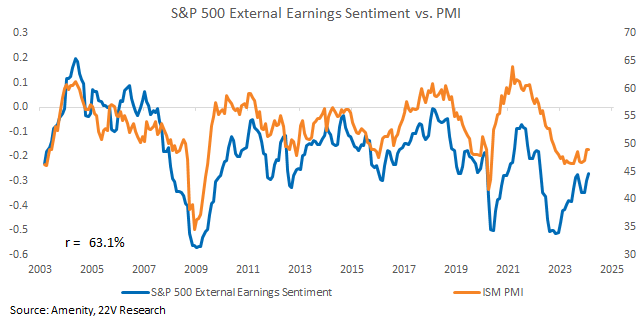
When we look at what companies say about the broader macro environment (We use an NLP tool to measure what companies say about the external macro backdrop), companies should continue to sound more positive about the outside macro world as PMIs continue to stabilize/improve. Improving corporate sentiment should be a positive for future Capex trends. If inflation remains stuck at too high of a level and the Fed must tighten, corporate macro sentiment would likely decline. That is not our base case, but it is a risk if wage growth remains too high.

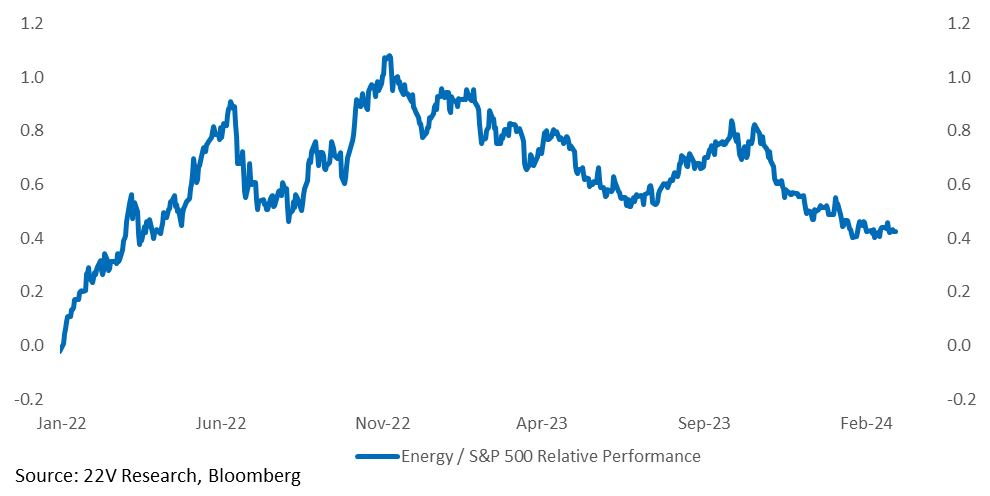
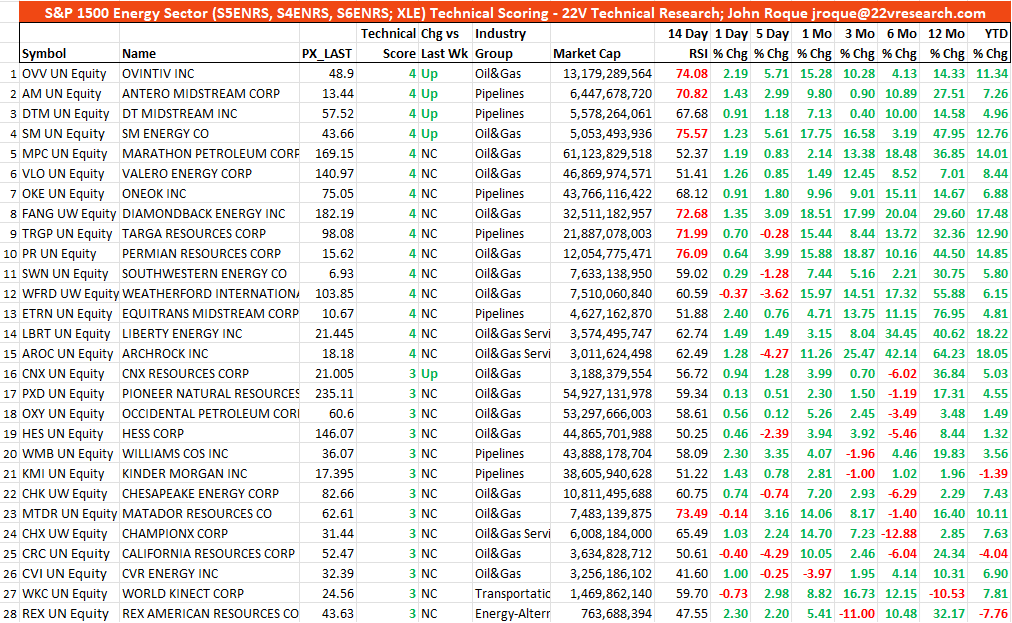
Cyclicals are significantly outperforming Defensives, but Energy has lagged. In a normal economic expansion, which we are in now, you should expect all Cyclicals to benefit over time, so some Energy catchup should be expected. John Roque highlighted the top 28 Energy stocks within the S&P 1500 Energy sector Yesterday (S&P 500 + S&P 400 + S&P 600). According to John, “within this list (39% of the S&P 1500 Energy Sector), please notice the 5 stocks that are benefitting from a pickup in their Scores: OVV, AM, DTM, SM, and CNX.”
Full report below….
MARKET VIEWS: Core PCE was in line with expectations and Powell’s preferred metric (Core services ex housing) hit expectations of 0.6% MoM. Even though we have 80-85% of the inputs into Core PCE from the CPI/PPI, so out of consensus readings are much less likely, for the first time in a while, an inflation data point didn’t come in obviously on the hawkish side. That helps explain the relief rally post the number. Interestingly, European CPI came in higher than expected and yields are lower (both in Europe and the US). At the same time, 67% of the investors we surveyed yesterday think 10yr yields will end March higher (HERE). The median expectation for the 10yr yield at the end of March is 4.35%, and the median for the end of June is 4.17%. 30% think the 10yr yield could reach the 4.4%-4.6% range by the end of March.
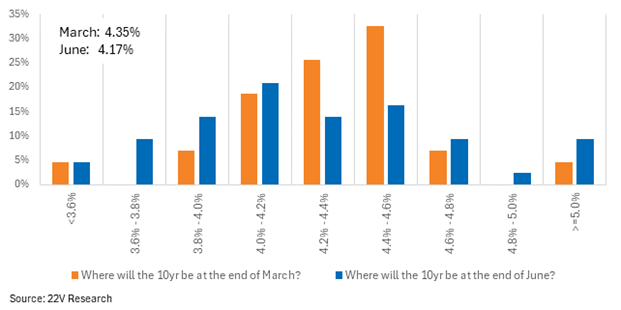
We get US PMI data today and it is likely to continue to stabilize/slightly improve over the coming quarters. See Peter Williams note on the coming improvement in the goods economy. When we look at what companies say about the broader macro environment, we should expect companies to continue to sound more positive, about the outside macro world, as the PMI continues to stabilize/improve. Improving corporate sentiment should be a positive for future Capex trends. If inflation remains stuck at too high of a level and the Fed needs to tighten, corporate macro sentiment would likely decline. That is not our base case, but it is a risk if wage growth remains too strong.
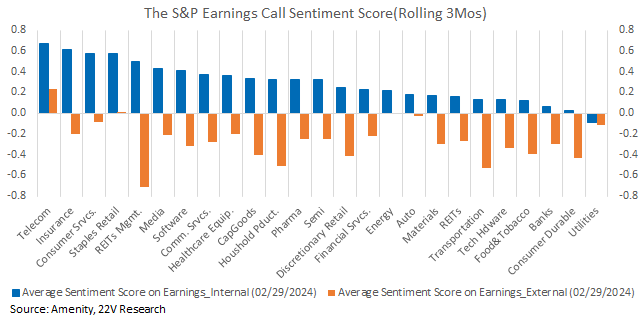
Below we highlight industry groups with the best internal (what they are saying about their own profitability, earnings etc.,) vs. external sentiment (what they are saying about the broader macro backdrop) coming out of 4Q. Telecom has the highest earnings sentiment both internally and externally. Transports have one of the largest spreads (good internals, deeply negative macro).
Energy: Cyclicals are significantly outperforming Defensives, but one Cyclical that has lagged is Energy. In a normal economic expansion, which we are in now, you should expect all Cyclicals to benefit over time. Energy has been a Cyclical laggard and some catch should be expected.
John Roque highlighted the top 28 Energy stocks within the S&P 1500 Energy sector Yesterday (S&P 500 + S&P 400 + S&P 600). According to John, “within this list (39% of the S&P 1500 Energy Sector), please notice the 5 stocks that are benefitting from a pickup in their Scores: OVV, AM, DTM, SM, and CNX. Without engaging in hyperbole, these 5 are in good buy / add spots.” The rest of the list shows the energy stocks with positive Technical scores.
Source: Bloomberg, 22V Research

