Back Economics

Quick note on forward Fed pricing

Published on February 26, 2024

∙ Download the PDF Report

By

Gerard MacDonell

Interest rate futures continued to weaken last week and now price as the mean of the probability distribution that the Fed will cut just 3 ¼ times (assuming 25 bps each time) by the end of the year.  The implied modal outlook is probably lower, given that the skew presumably remains to the left.  So, the market is now in line with what the Fed dots said in December and what senior Fed officials continue to imply is likely to be the best guess as of the March 20 FOMC Summary of Economic Projections.  As recently as early January, the market was looking for the Fed to go about twice as fast this year, as the chart below shows.

Expected 2024 rate cut has been cut in half
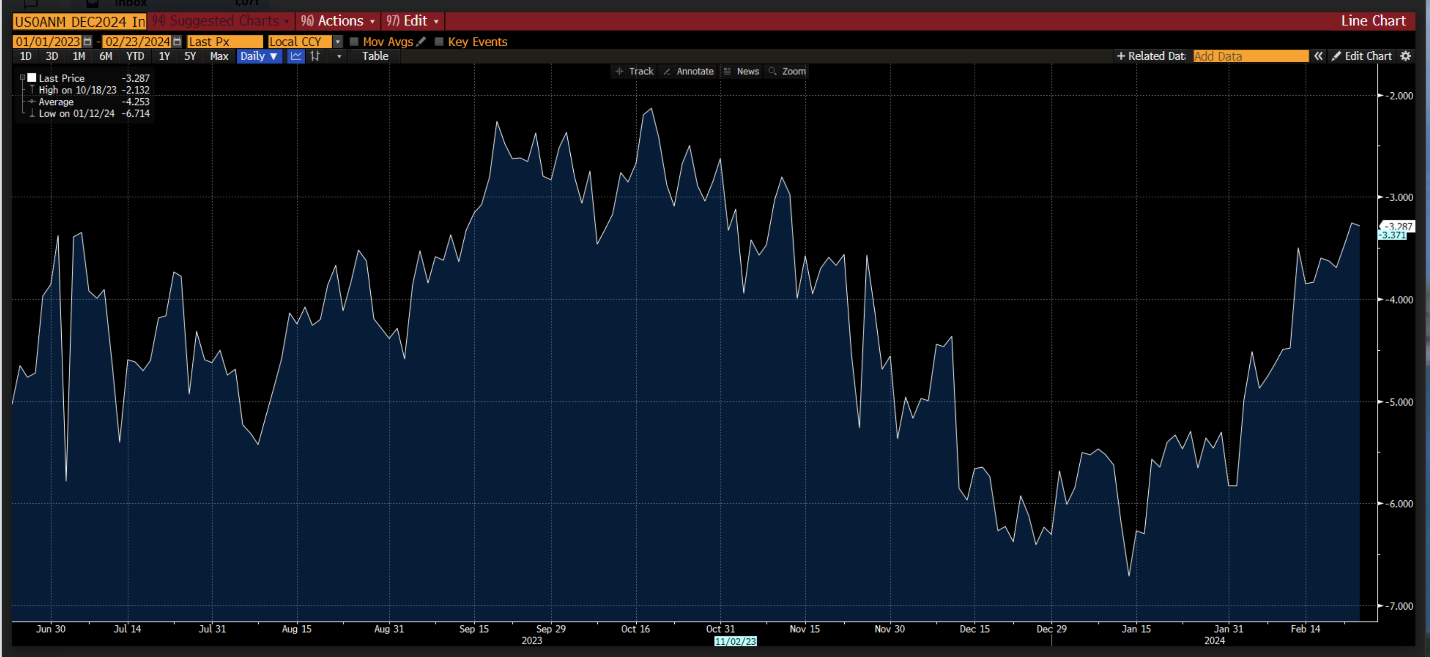
A screen shot of a graph

Description automatically generated
Source: Bloomberg
Data are to close Friday. 

Financial conditions have not tightened much in response to repricing of the Fed.  Indeed, both the daily version of the Fed’s FCI-G, which I work up, and Goldman’s FCI are near their easiest points for this episode, although the Goldman formulation looks slightly easier in level terms, relative to its own longer history.  There are two reasons for this. First, risk asset prices have remained strong, despite the repricing. This fits my earlier view that lower inflation, relative to say six months ago, raises the speed limit for growth and thus perhaps the fair-value of risk asset prices for any given funds rate path.  The recently stronger price data reduce the urgency for Fed ease, but don’t move the speed limit much, as I have been emphasizing. Moreover, the growth data themselves have recently been generally strong. So, this fits, although it may be a bit bold to tell a story to rationalize a two week move – or non-move – in asset prices. Fluke is usually the best answer.

Second, the beta of longer-duration interest rates to the nearby funds rate path is simply not very high. So, even without the strength in risk asset prices we should not have expected much movement of measures of financial conditions indexes. What excites us on a week to week basis is generally noise when thinking of a horizon that is relevant to the effect of asset prices on economic conditions, which is what these indices try to capture.

Financial conditions seemingly remain easy or at least non-tight practically speaking

A graph of a stock market

Description automatically generated with medium confidence
Source: Bloomberg, Federal Reserve (for formulation), FH calculations of daily version
Data are actual to Friday close.

The most straightforward implication of this is that we should probably continue to look for a further hawkish repricing of the short end in order to nudge financial conditions tighter, as would seem to be required to limit demand growth to its potential rate or to slightly below, as would seem to be the Fed’s preference.  The speed limit is higher than it was, and the Fed has had the luxury for a while now of risk managing against recession as well as against inflation. And that has mattered for risk assets. The speed limit is not that high, and the demand indicators have been generally solid. 

The problem for me, though, is that the repricing at the short end is not likely about the market coming to my view of how things work. Rather, the Fed leadership has apparently been on a mission to prevent a further easing of financial conditions, by insisting that they are likely to ease belatedly and slowly.  That seems right to me. But to state the obvious, investors have been listening to the Fed, not my arguments.  And it seems unlikely that Fed rhetoric will toughen even further from here unless the data surprise to the upside. One reason among several is that the Fed still lets on at least that they view monetary policy as tight. Not sure why, but they do. 

 Separately, but perhaps reinforcing, equities now look about as expensive as they did before the GFC.  So, it is possible they might start acting a bit more sensitive to any incremental rates hawkishness from here. This is not the main point, but it seems worth mentioning.

Finally, last week was quiet on the data front, which allowed Fed talk to dominate.  But this coming week, might be the opposite, as there are several important indicators due, all of which have the potential to surprise. So, it might be prudent to watch, wait, and perhaps hope for a misinterpretation (by my lights) of the news about to come. 

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.