

Bottom Line: While the S&P briefly touched its new all-time high of 5100 last week, internal dynamics suggest less bullish sentiment on the week. Fed speakers continuing to push back on the start of rate cuts is a large part of the reason risk-off names worked. Assuming 3 cuts this year and 2-2.5% real GDP growth, riskier assets will work. For riskier internals to outperform, the expected summer start to rate cuts needs to hold. That will be the case if economic growth remains around trend (2%ish).
Relevant News: Although last week’s internals indicate a risk averse trend, keep in mind that, credit spreads remain exceptionally low, Treasury yields are off their highs, Cyclicals are significantly outperforming Defensives YTD within the S&P and Deep Cyclicals (Energy, Industrials, Materials) are +2.5% YTD (equally weighted) vs Defensives (Staples, Utilities, Healthcare).
Things to Watch [Consensus, Results]:
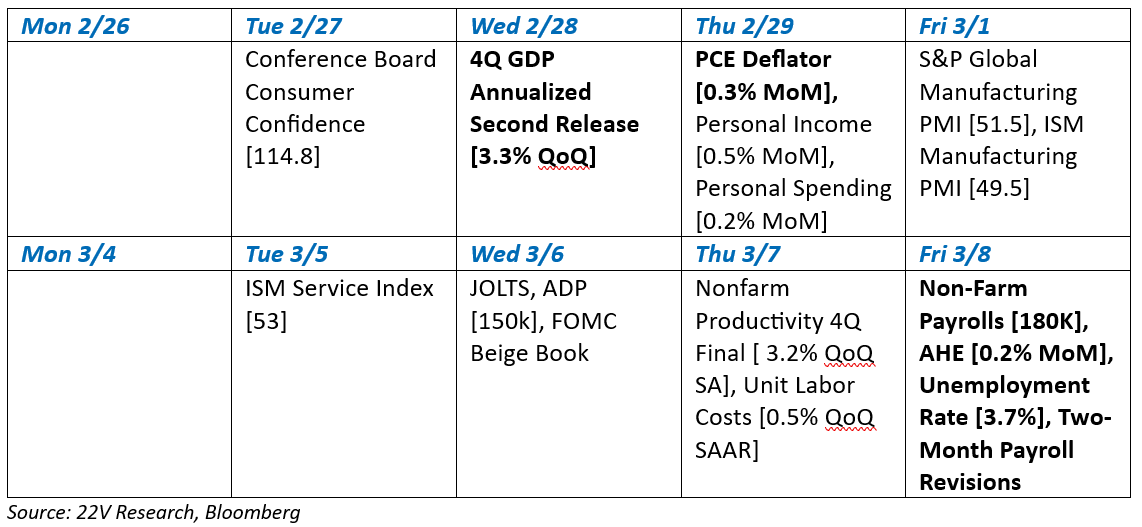
Economics: Commentary on Financial Conditions
Financial conditions have not tightened much in response to repricing of the Fed. The most straightforward implication of this is that we should probably continue to look for a further hawkish repricing of the short end of the curve in order to nudge financial conditions tighter, as would seem to be required to limit demand growth to its potential rate or to slightly below- which is the Fed’s preference. Looking forward, a further tightening of financial conditions may be needed. Equities’ high valuation could heighten sensitivity to rate hawkishness.

Source: Bloomberg, Federal Reserve (for formulation), FH calculations of daily version. Data are actual to Friday close.
Portfolio Strategy & Quant: Value and Growth Divergence Deepening
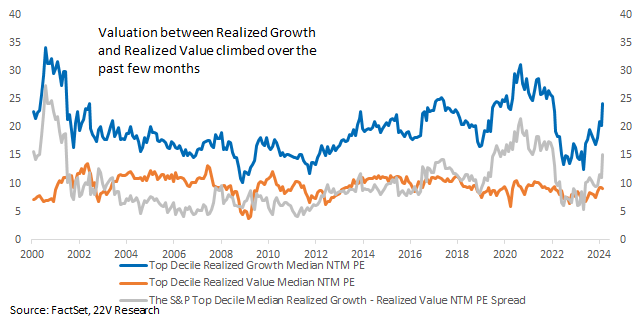
The number of stocks ranked as BOTH high Value and Growth has declined (less overlap) and return correlations to the two factors are easing as well. The divergence between style factors is part of a larger shift away from risk factors and should be expected to continue unless the macro backdrop deteriorates significantly. Return divergence has led to a growing fundamental spread between Value and Growth as well. NTM PEs for Value names remained relatively stable while Growth PEs shot higher. The spread between the two has reached its 85th percentile. PE spreads are not a timing tool, so there isn’t a mean reverting argument to be made here. A macro catalyst is needed to narrow the style factor PE gap.
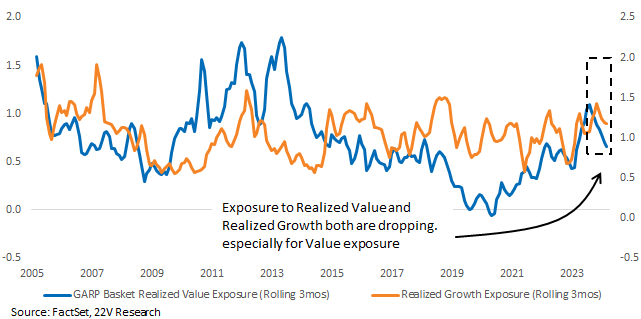
Our GARP (Growth at a Reasonable Price) basket exposure to Realized Value and Realized Growth both dropped since late last year. Though the current basket remains most exposed to Realized Growth, its exposure to Value has dropped behind Relative Size and Earnings Turbulence. In other words, GARP is becoming less of a pure play on style factors. This will increasingly complicate screening for these factors. It will be more important going forward to isolate style factor exposures from others (Size, Risk, etc.,).
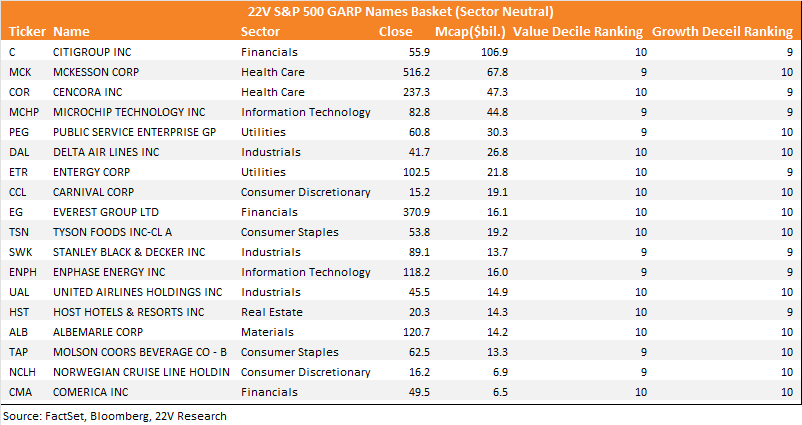
Below, we list the S&P names falling into the GARP basket today. Though increasing divergence between Value and Growth has led to a smaller number of stocks, the selected names are expected to gain from their fundamental exposure.
Technical Analysis: Chart Spotlight: Mid-Caps
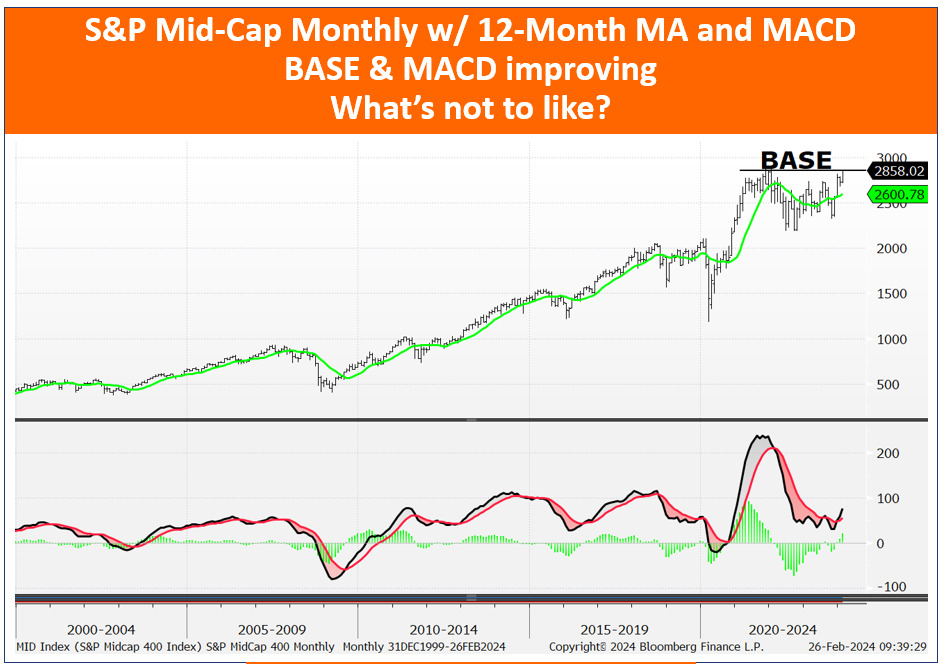
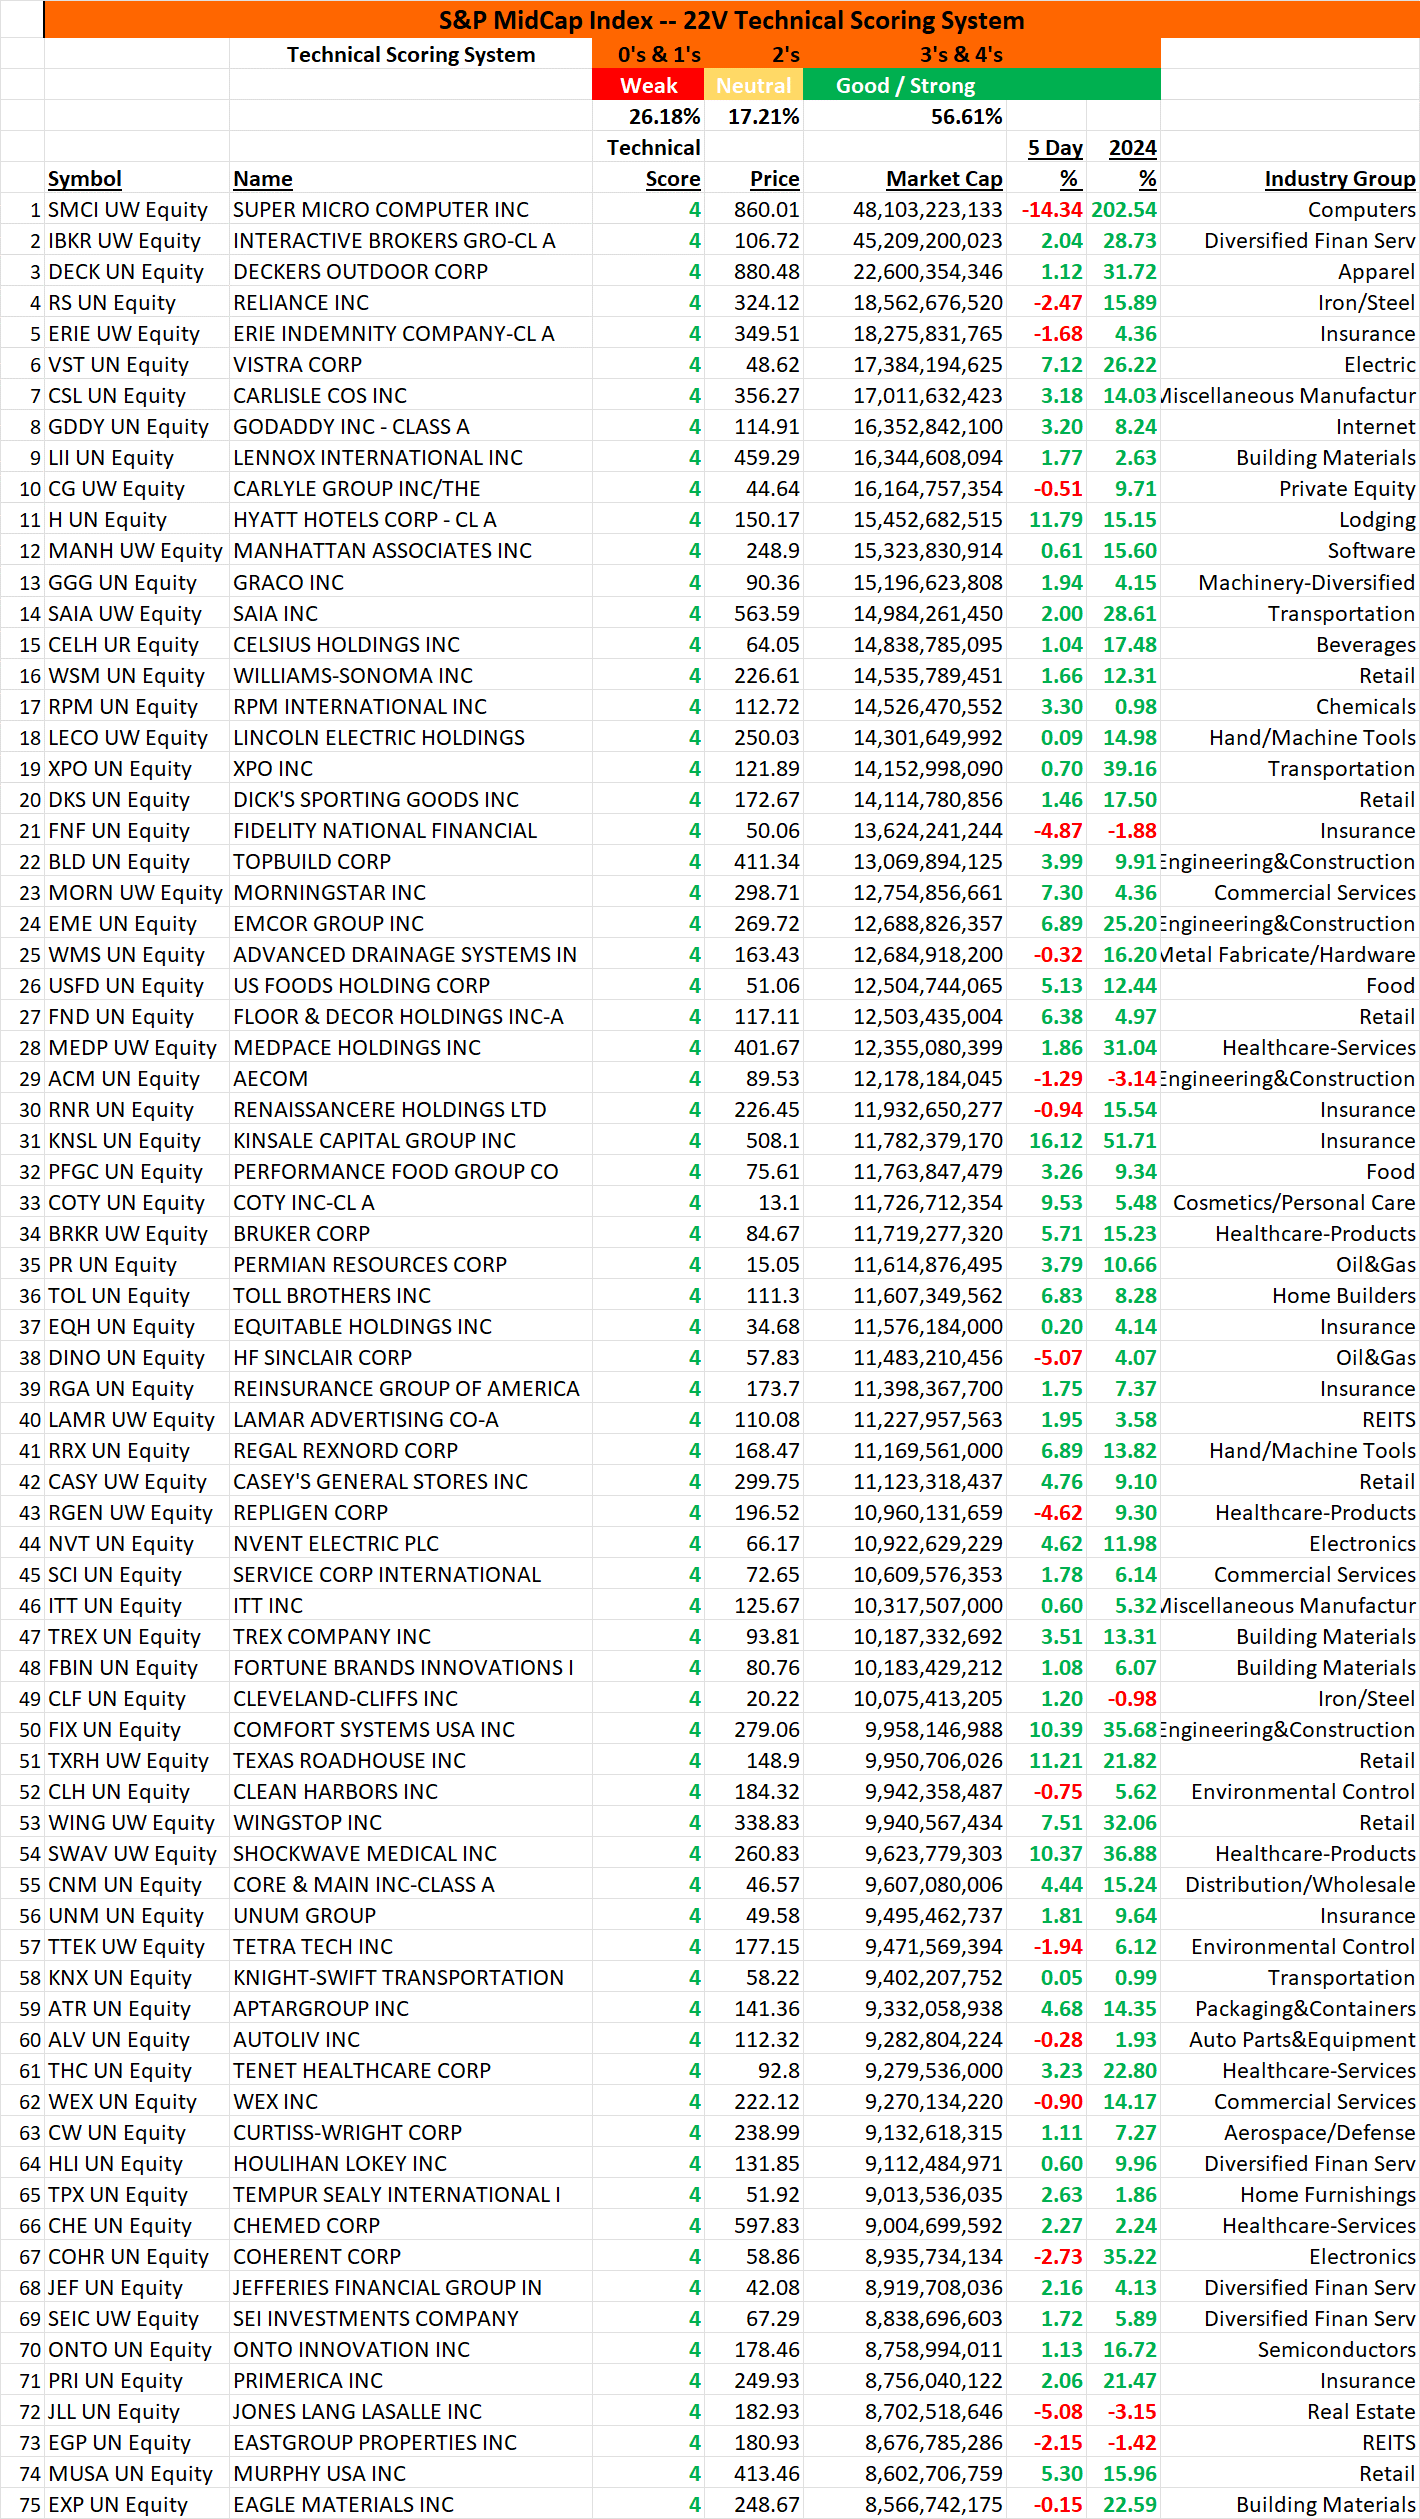
22V’s technical analyst continues to like the S&P Mid-Cap index. Please see chart banner for further commentary and the names with the best technical scores according to his work below.
Source: 22V Research

